

Friends of NFTBC.
In Part I of the PTC deep dive we examined the company’s past, present and future. We also talked about PTC’s varied growth drivers and the durability thereof. Part I was intended to be a largely self-contained overview of the most notable considerations for investors weighing up PTC. But, as promised, there’s a second part.
First we’ll go on a whistle-stop tour of PTC’s most important products. Then we’ll have a look at PTC’s evolving strategy with AI. We’ll conclude by highlighting some of the financial considerations for understanding PTC and its growth drivers.
[NFTBC does not give advice - please do your own research. I currently own shares in PTC].
Products
Under Jim Heppelmann, PTC used to host an annual showcase conference for customers in Boston, called LiveWorx. As successor Neil Barua has decided not to continue LiveWorx, opting instead to make product demos more regionally/locally focussed rather than centralised at a large event that many cannot attend. I’m bringing this up because Heppelmann’s keynote at LiveWorx 2023 is recent enough still to be highly relevant and it was also a helpful overview of PTC’s main products, their capabilities and the digital thread strategy - if you’re investigating PTC and you’re new to the story it’s worth watching.
Rather than attempting painstaking technical detail about these various products, my ambition here is to try to point you in the right direction and provide you with relevant leads on the most important ones. In Part I, I outlined the case for durable long-term growth because I believe that the totality of the evidence supports it - here is the evidence. You’ll notice I have embedded quite a few videos in this post to add further context and complementary visualisation to the text - they are purely optional and to help you with your own investigations.
PLM / Windchill
Some years ago Autodesk’s CEO famously described product lifecycle management software as “a load of crap” and just a way for PTC, Dassault and Siemens to get more money from their customers. Boy, was he wrong - and he eventually changed his mind. But it’s notable that Autodesk isn’t a major PLM player today.
PLM software has three characteristics that make it compelling from the investor’s standpoint:
It’s incredibly sticky - customers are about as likely to replace their PLM system as they are their ERP
Having previously been largely confined to engineering departments, PLM is going forth into the wider enterprise - the market is less mature than CAD and growing faster (from “nice to have” to “must have”)
It’s very dull. Anecdotally, I rarely encounter investors talking about PLM, I assume because it’s not exactly exciting. I wonder if it’s slightly off the radar therefore.
Next, some definitional issues. There’s a degree of contention as to how exactly ‘PLM’ should be defined for the purposes of assessing the market as a whole. Go-to data provider CIMdata defines it expansively:
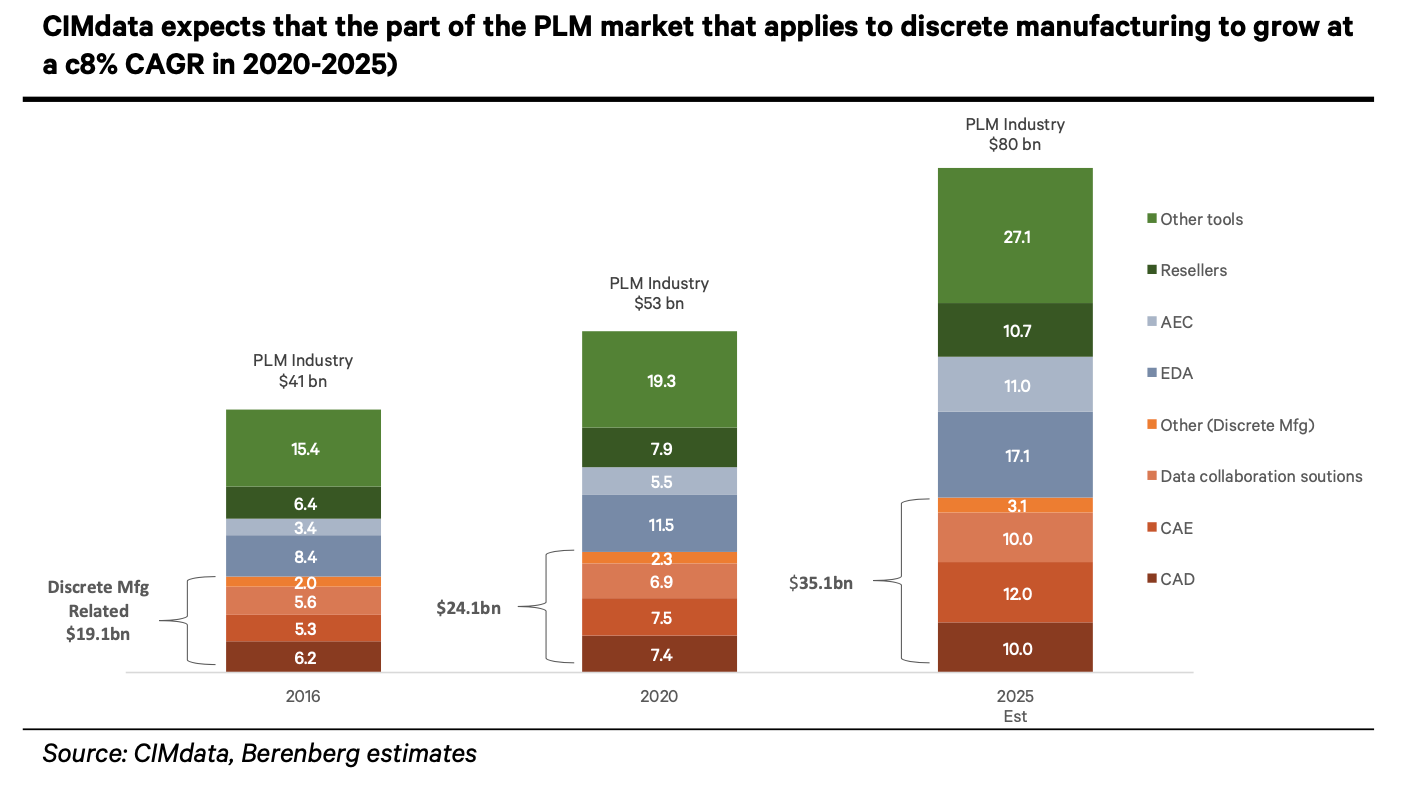
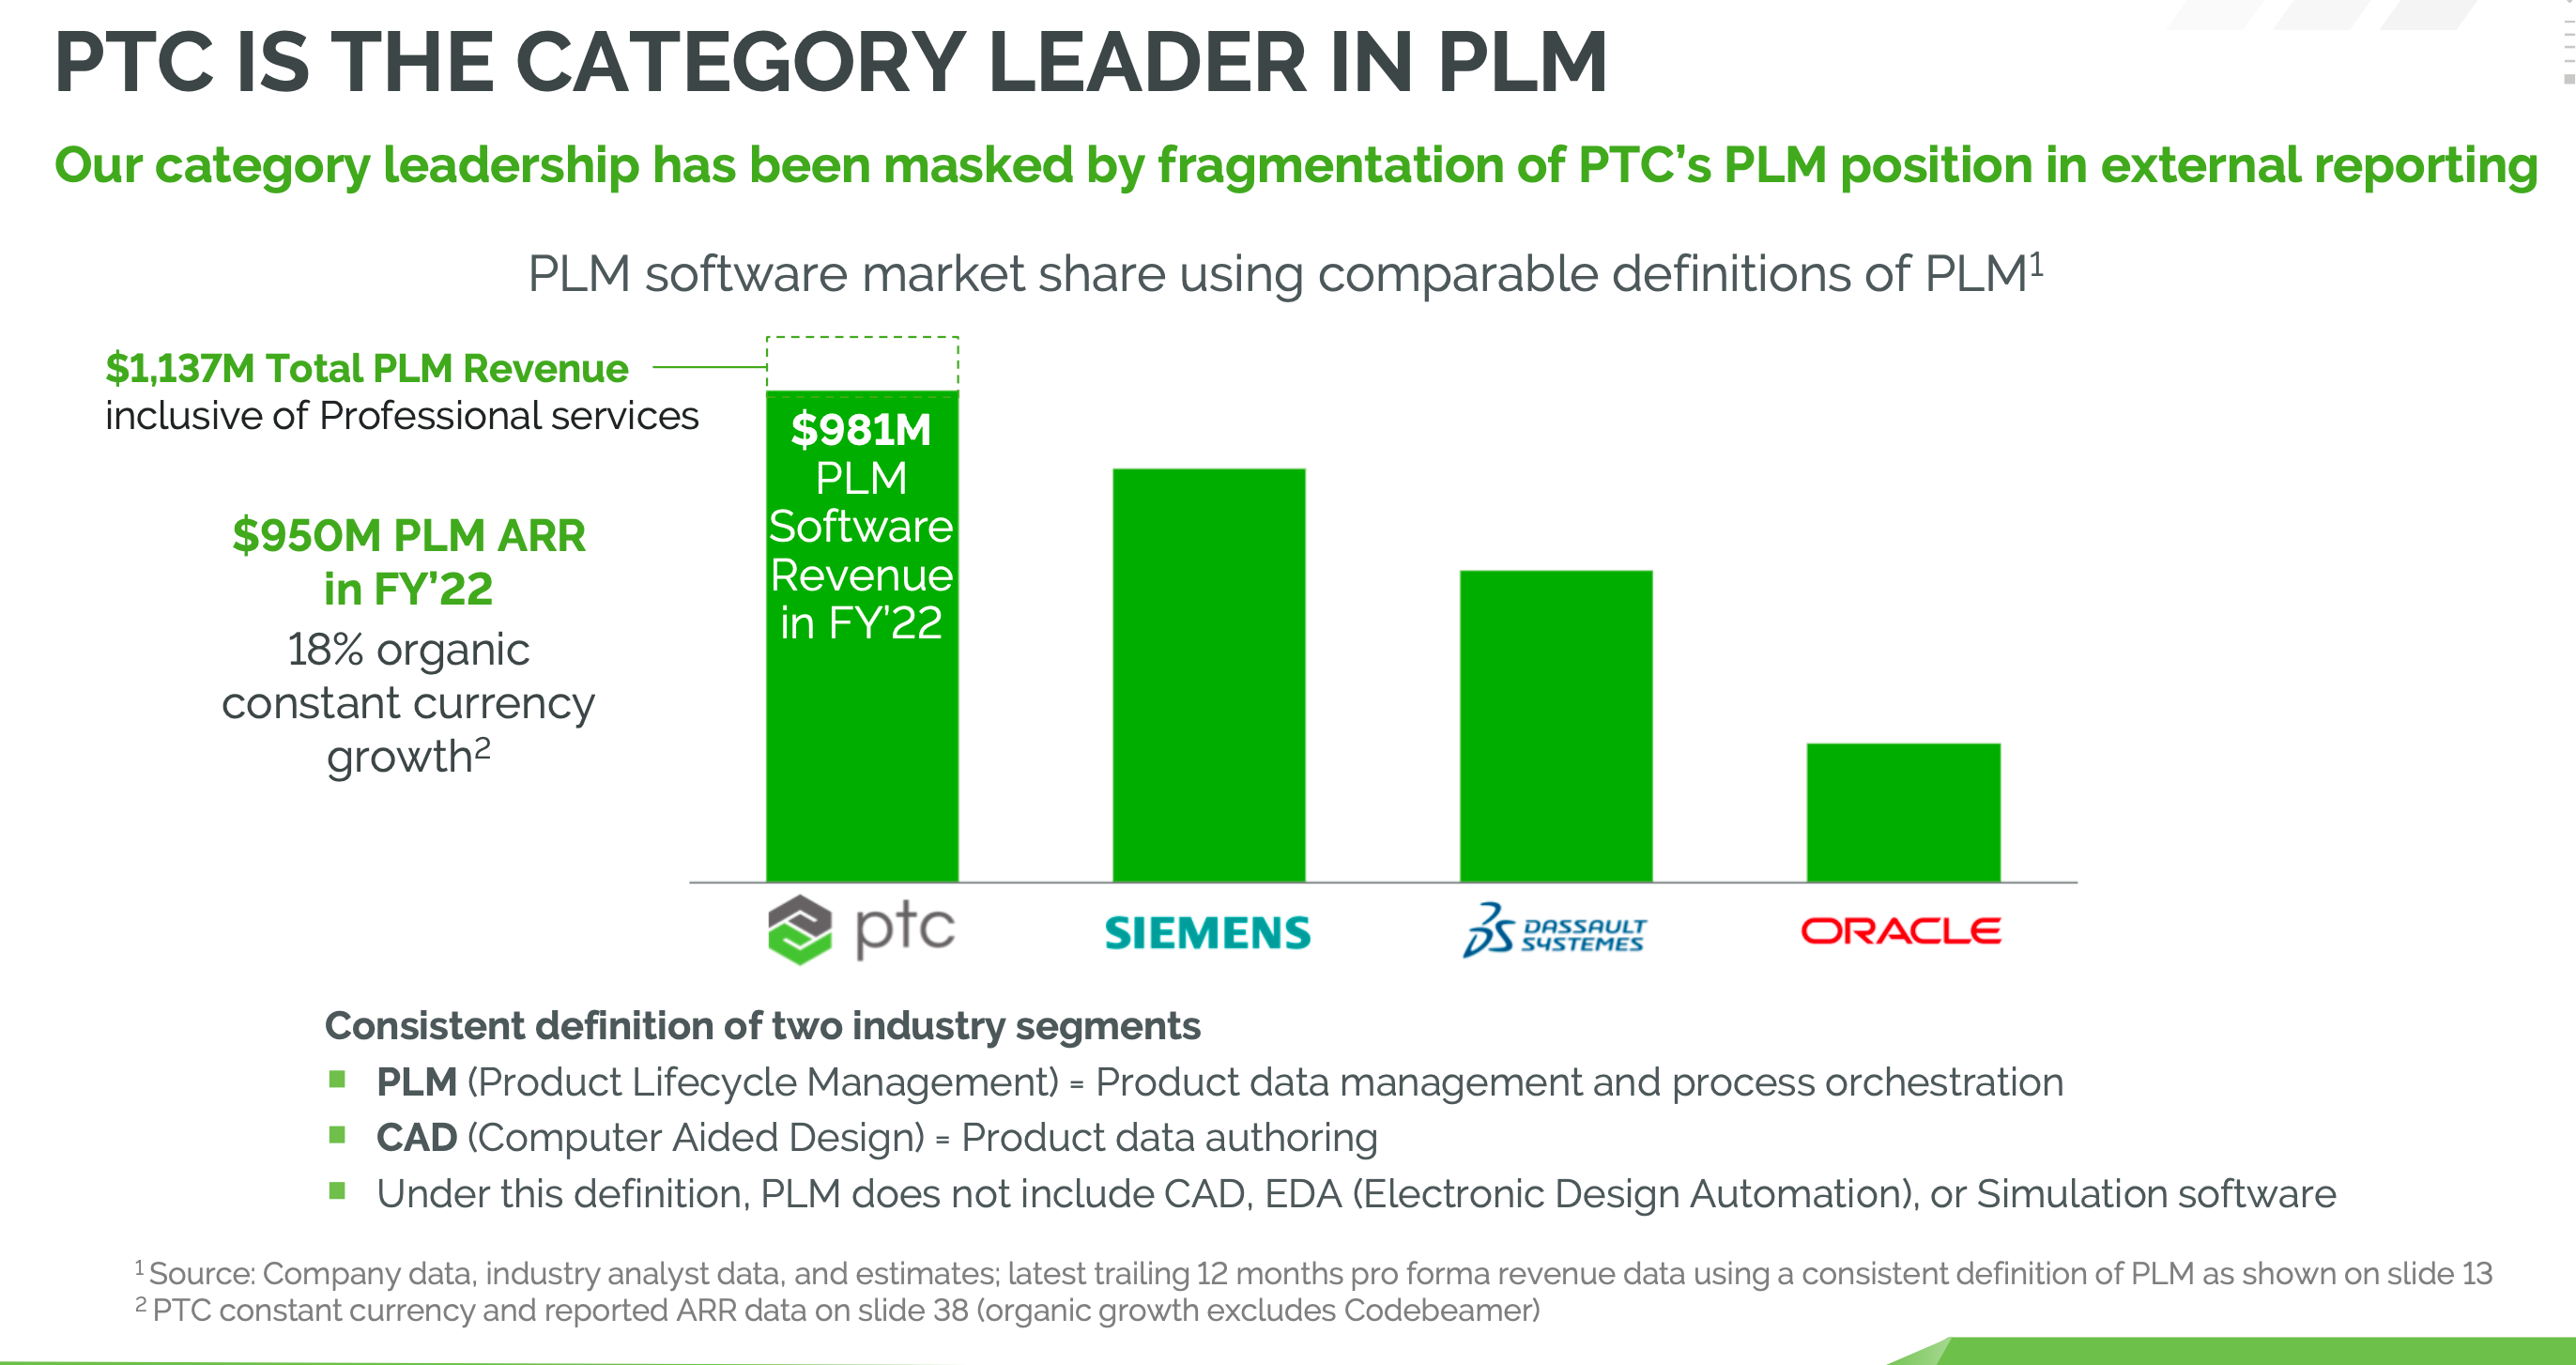
Whereas PTC takes a much more restrictive view - excluding such things as CAD, EDA, AEC etc. I would tend to side with PTC on this, bringing the definition down to PDM/PLM and peripheral software used in process orchestration. On this basis, PTC is actually the biggest player in the space with a high relative exposure to this higher growth segment:
Stickiness
If you go look for examples of companies switching PLM system, you won’t find all that many - churn is incredibly low. Once fully implemented, PLM becomes the ‘source of truth’ across CAD, manufacturing, regulatory, quality, and service etc. For example, here are some of the Windchill features that PTC highlight:
Parts classification
Enterprise software
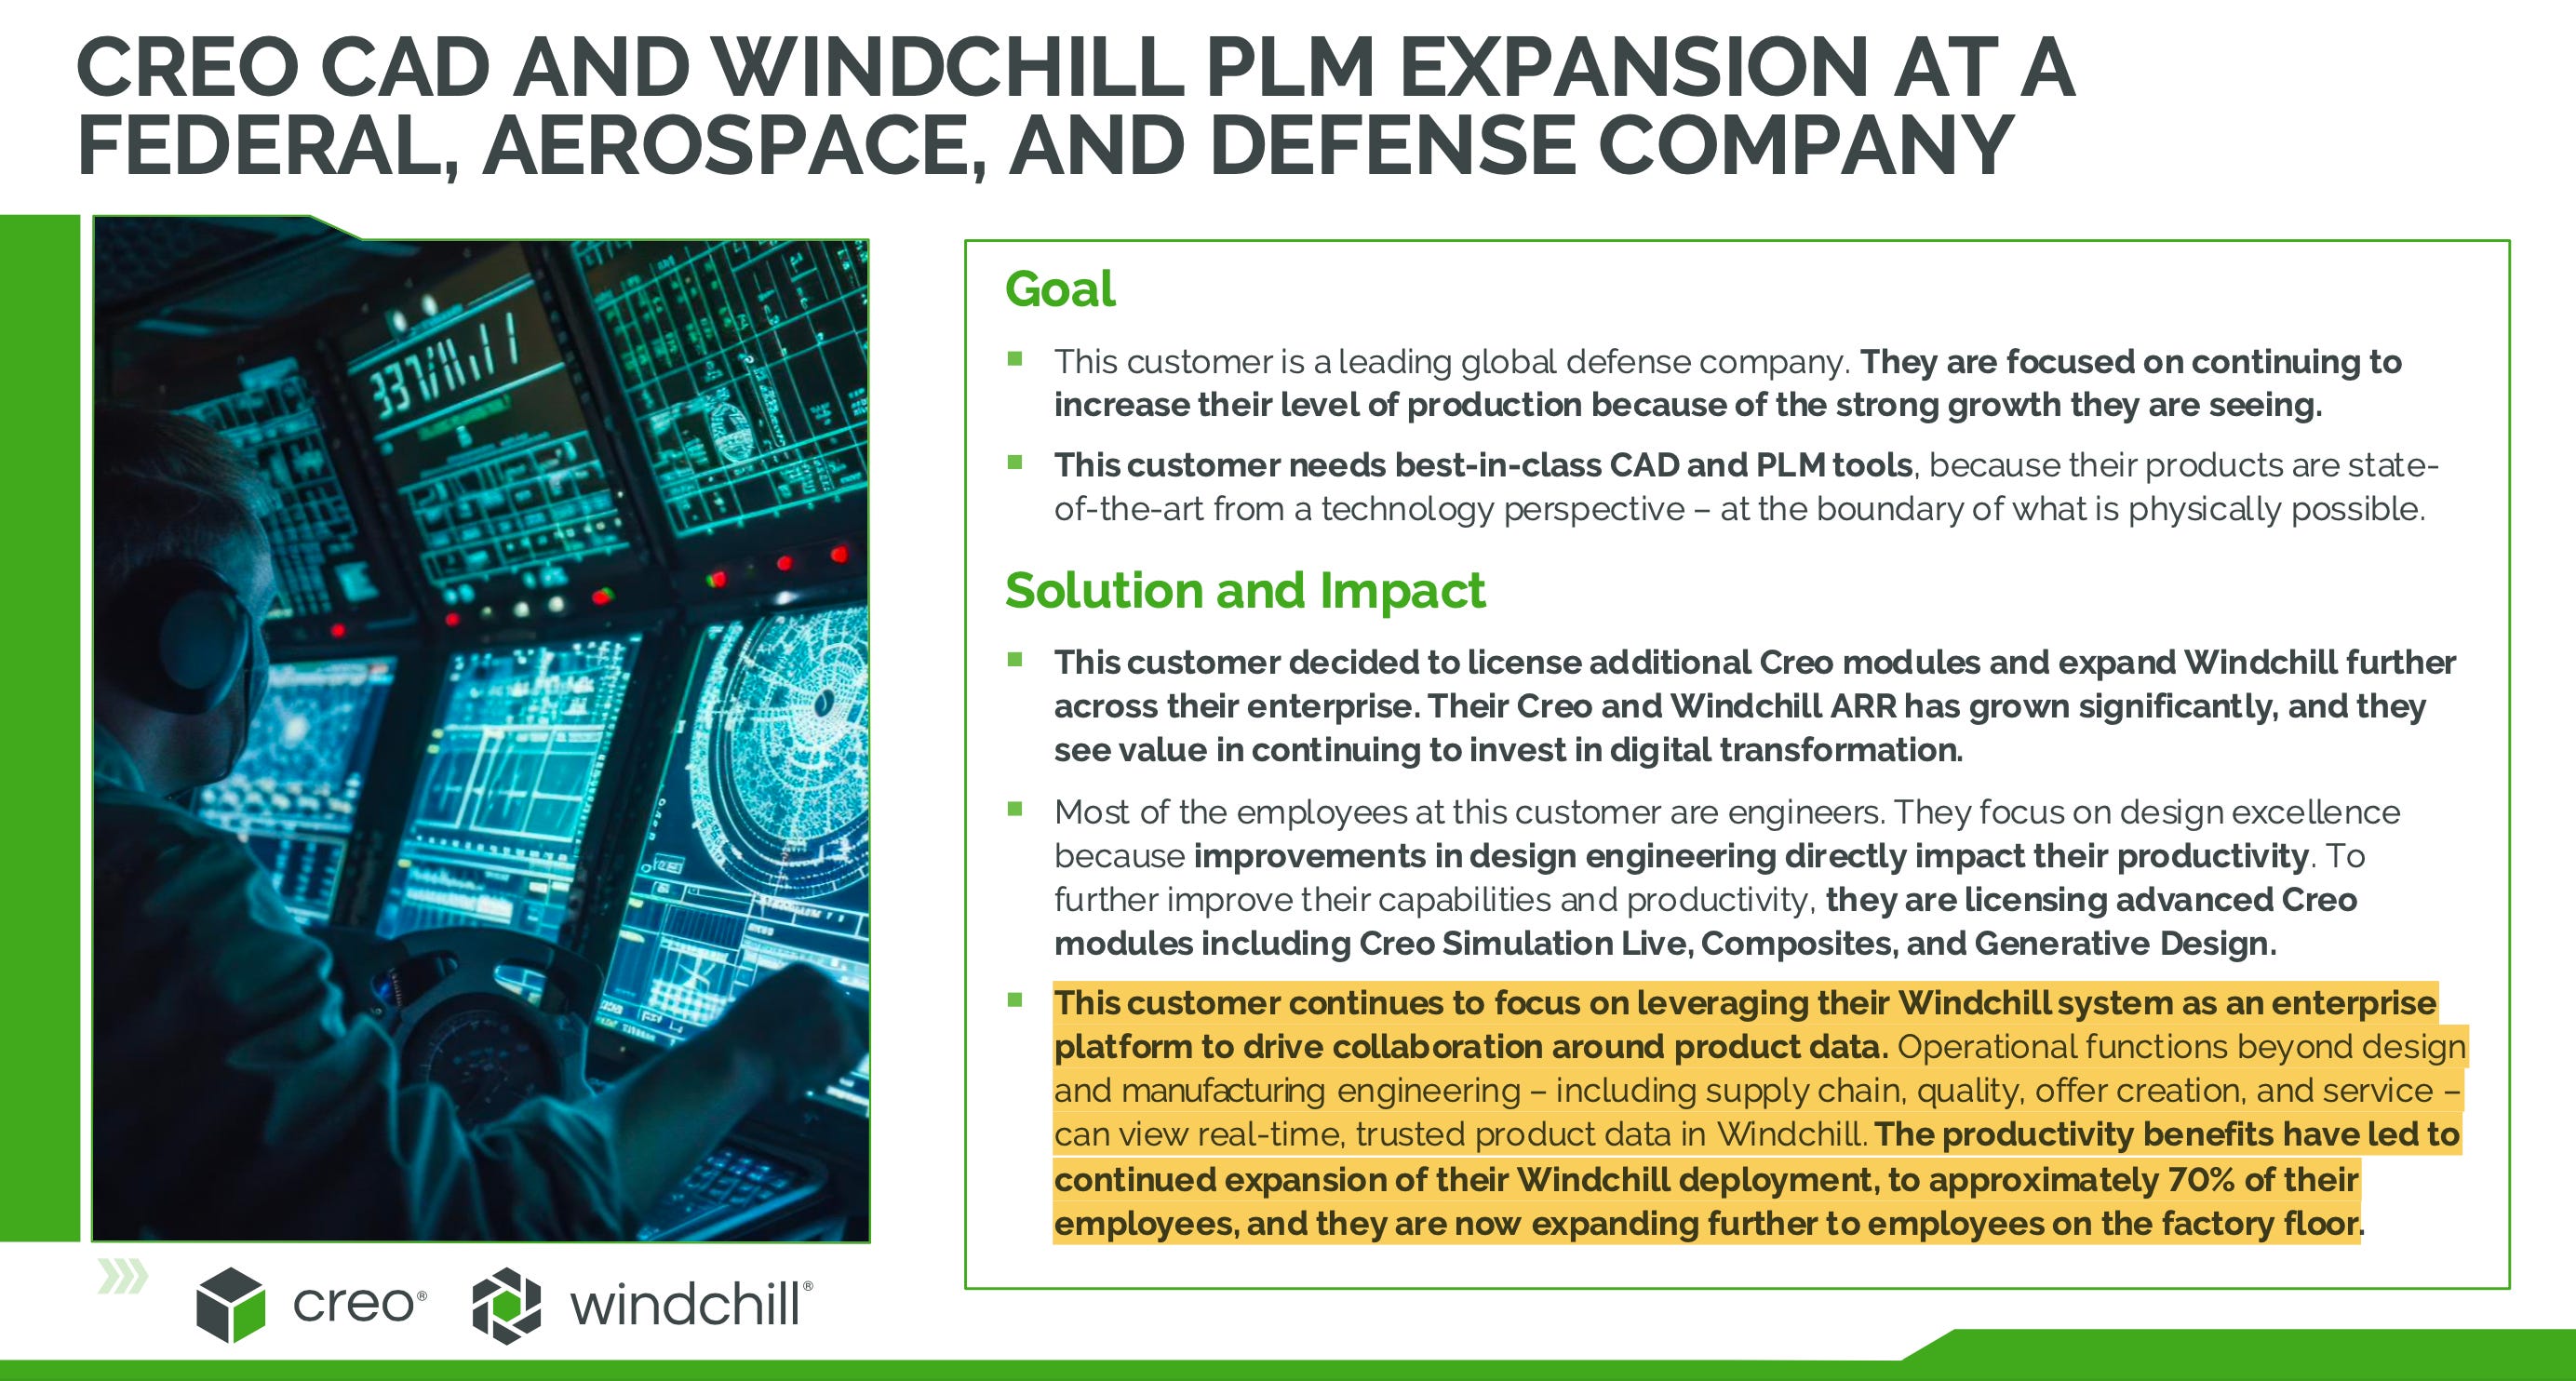
Traditionally, many product companies would start off with PDM as their CAD data vault, but otherwise use spreadsheets, ERP and other point solutions in dealing with lifecycle management. The choice to implement a PLM system is a major one that comes with cost, training and rethinking processes, but ultimately it breaks down silos and allows businesses to deal with complexity that could otherwise be unmanageable. A successful PLM implementation gives the customer greater control over costs and time to market - from ‘nice to have’ to ‘must have’. Each customer and implementation is different - PTC likes to provide case studies. Once implemented, PLM ends up at the very centre of things and deeply integrated with other applications - in effect, essential:
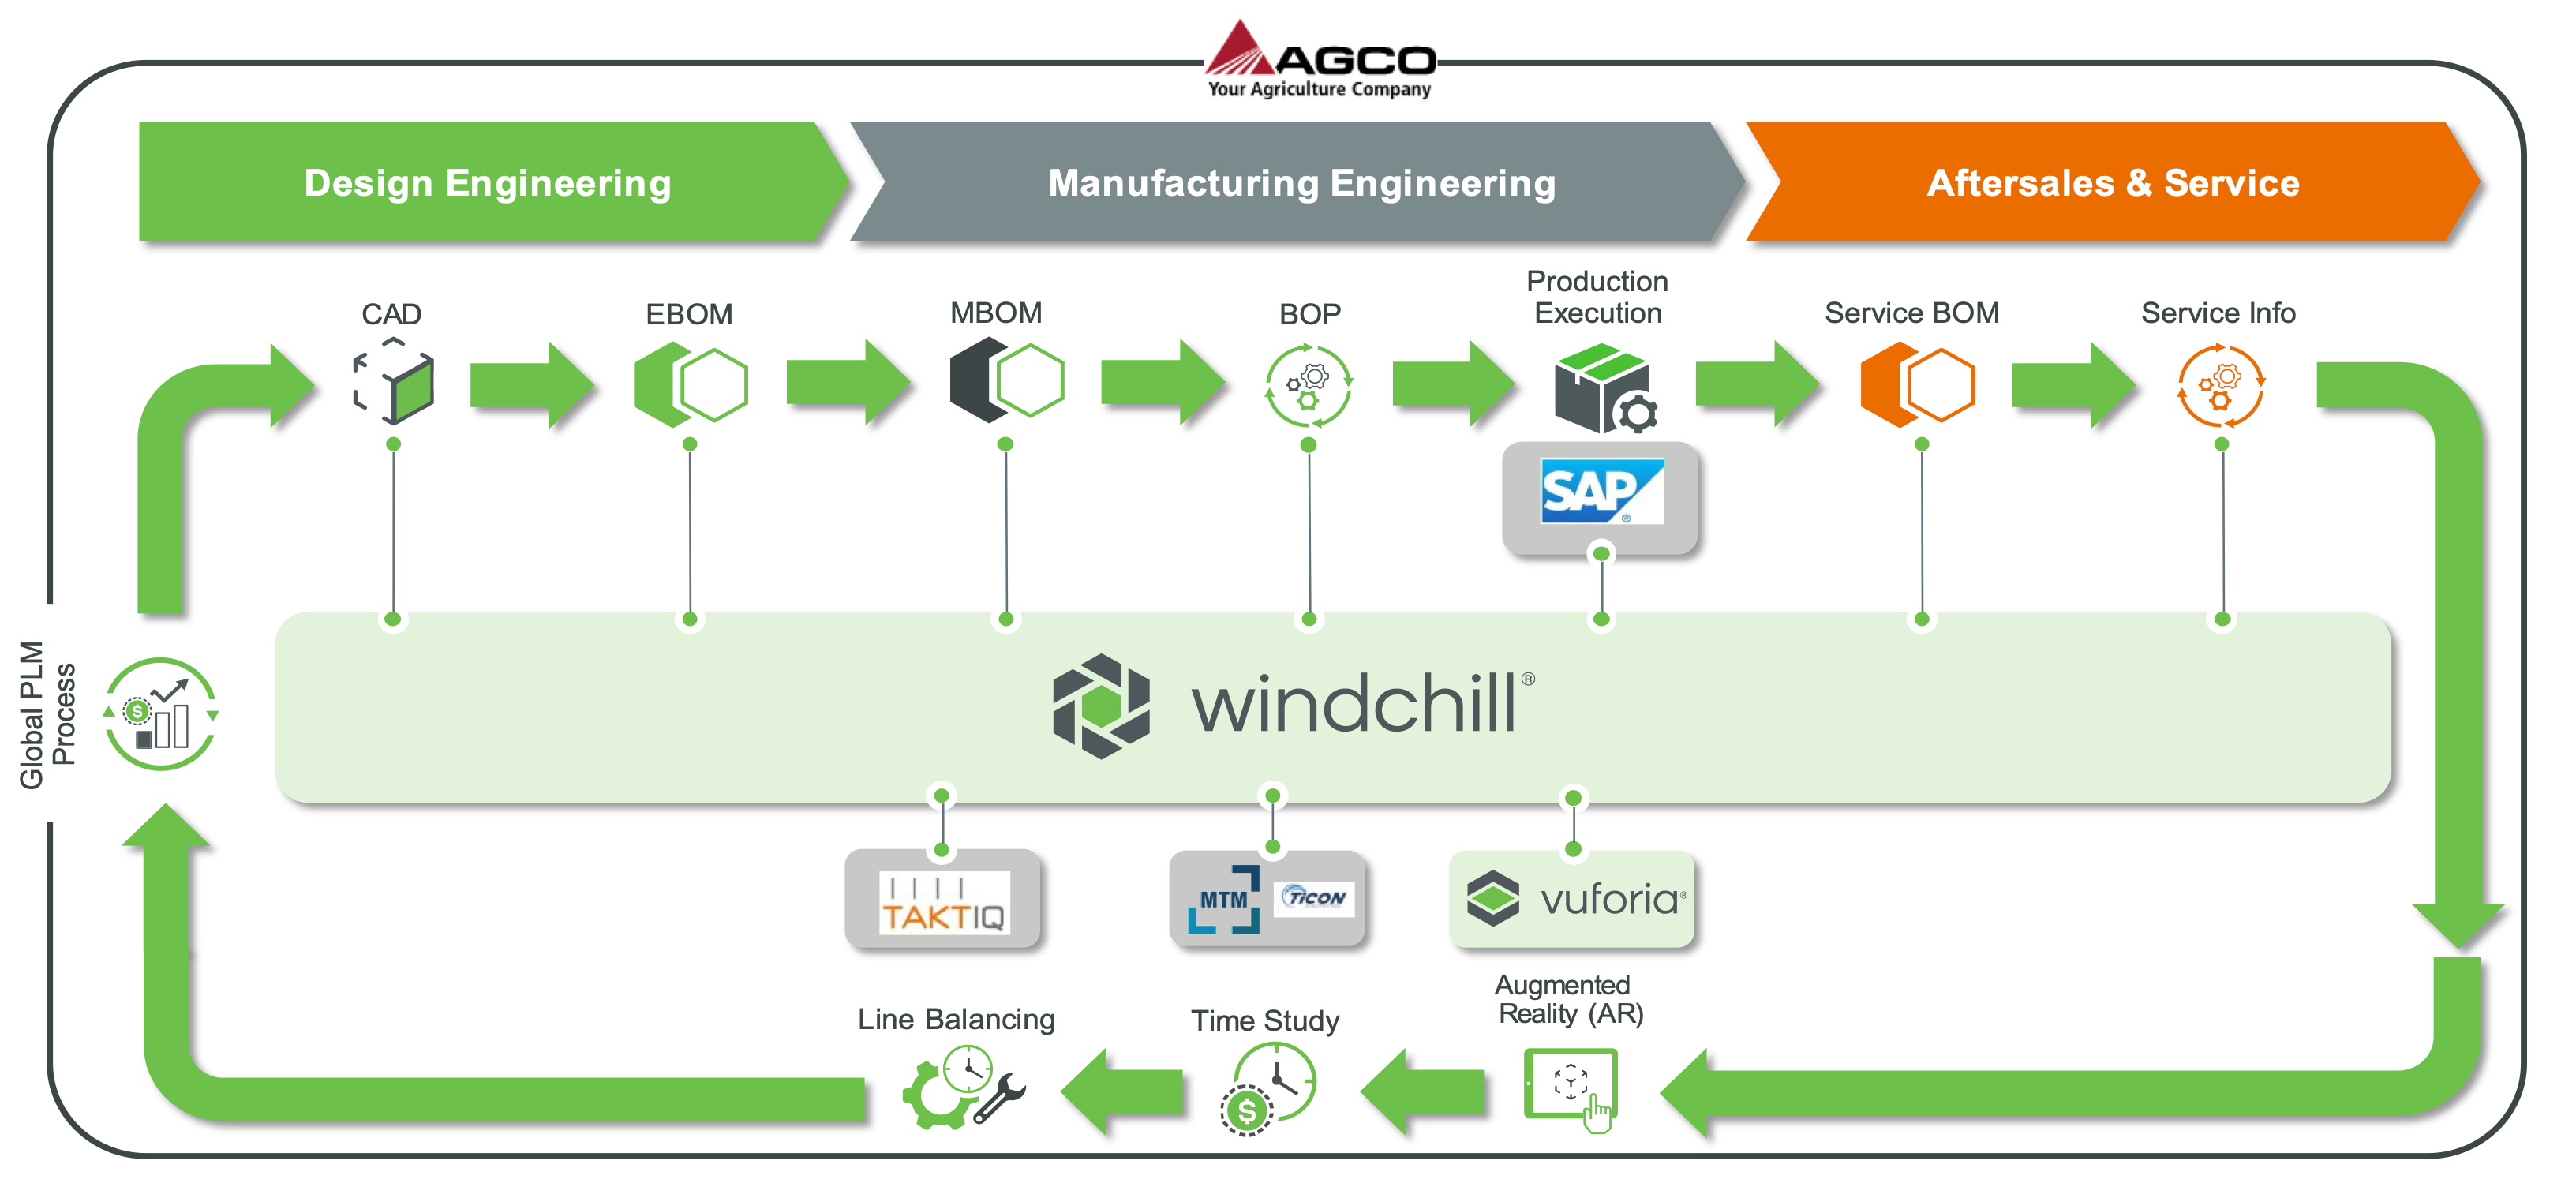
Implementation typically begins with product data management and design engineering, as you might expect. But PTC’s playbook, is to then expand further into the enterprise: manufacturing engineering, supply chain, service etc. This is why PLM is not yet a fully mature product, and the scope for ongoing growth is significant.
If you’re curious to have a look at Windchill in action, check out this PTC webinar and introduction.
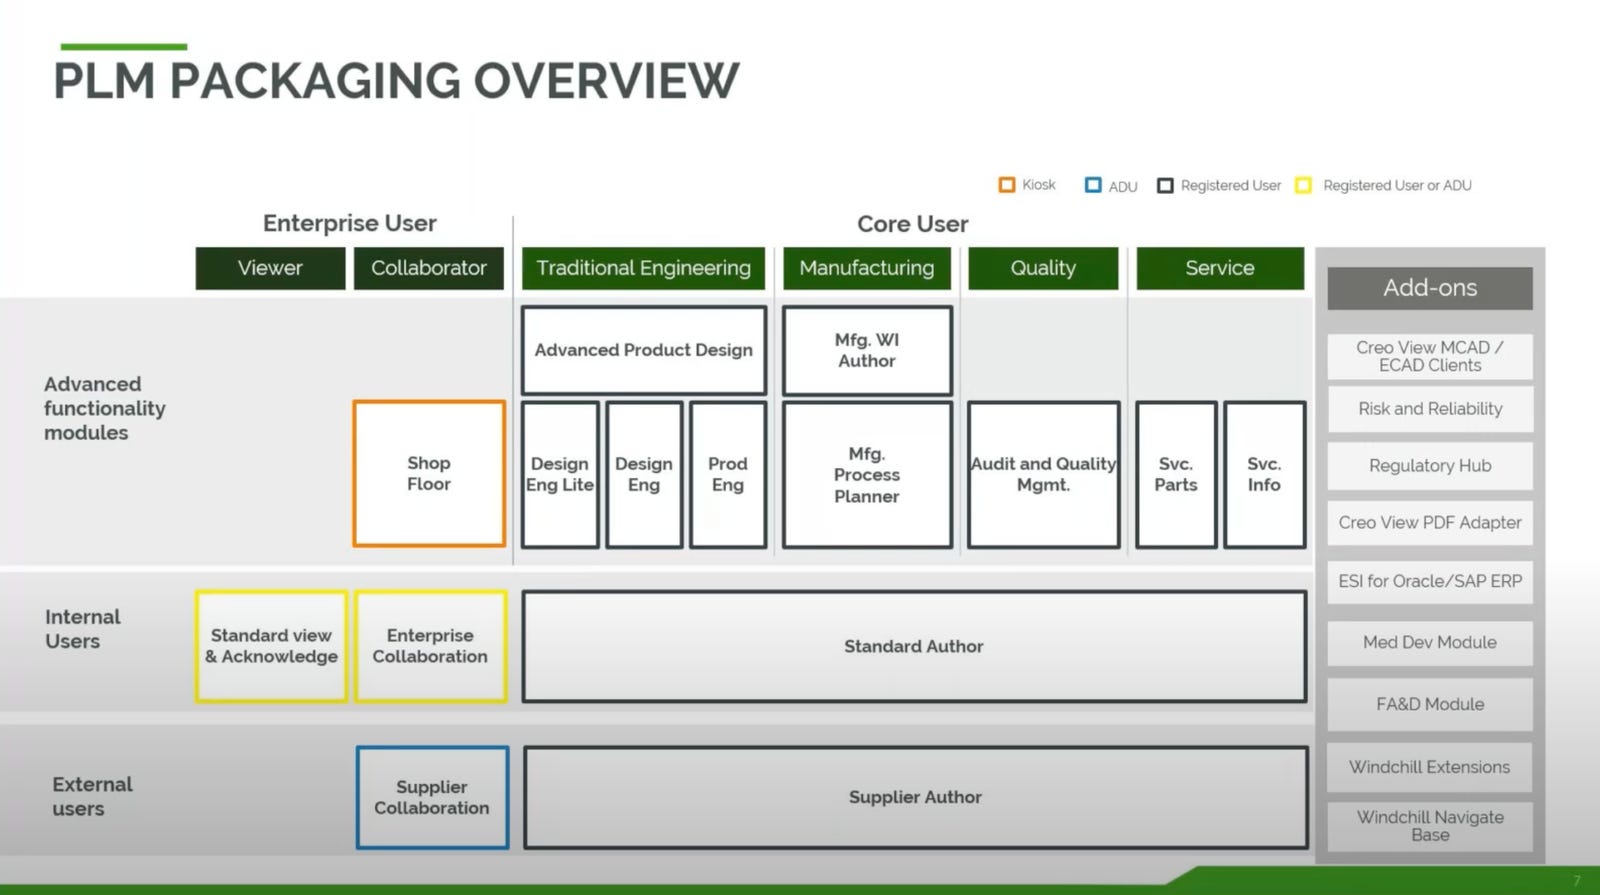
In Barua’s vision of PTC, Windchill is the epicentre of the digital thread. One of his initiatives this year, in conjunction with new CRO Robert Dahdah, has been to repackage Windchill access with the aim of reducing friction and simplifying seat expansion. In the process they’ve eliminated 85% license types, and reduced Windchill to two principal tiers: core users and enterprise users:
One of the over-arching selling points for Windchill (and indeed other PTC software) is inter-operability, open standards and out-of-the box integration. In the real world, and particularly at large manufacturing companies, it’s very common to see environments that are multi-CAD, multi-PLM and maybe even multi-ERP - PTC’s philosophy is not to try to provide everything, but instead to try to be compatible with everything. In terms of competition - Dassault is arguably at the other end of the spectrum and Siemens somewhere in the middle:1
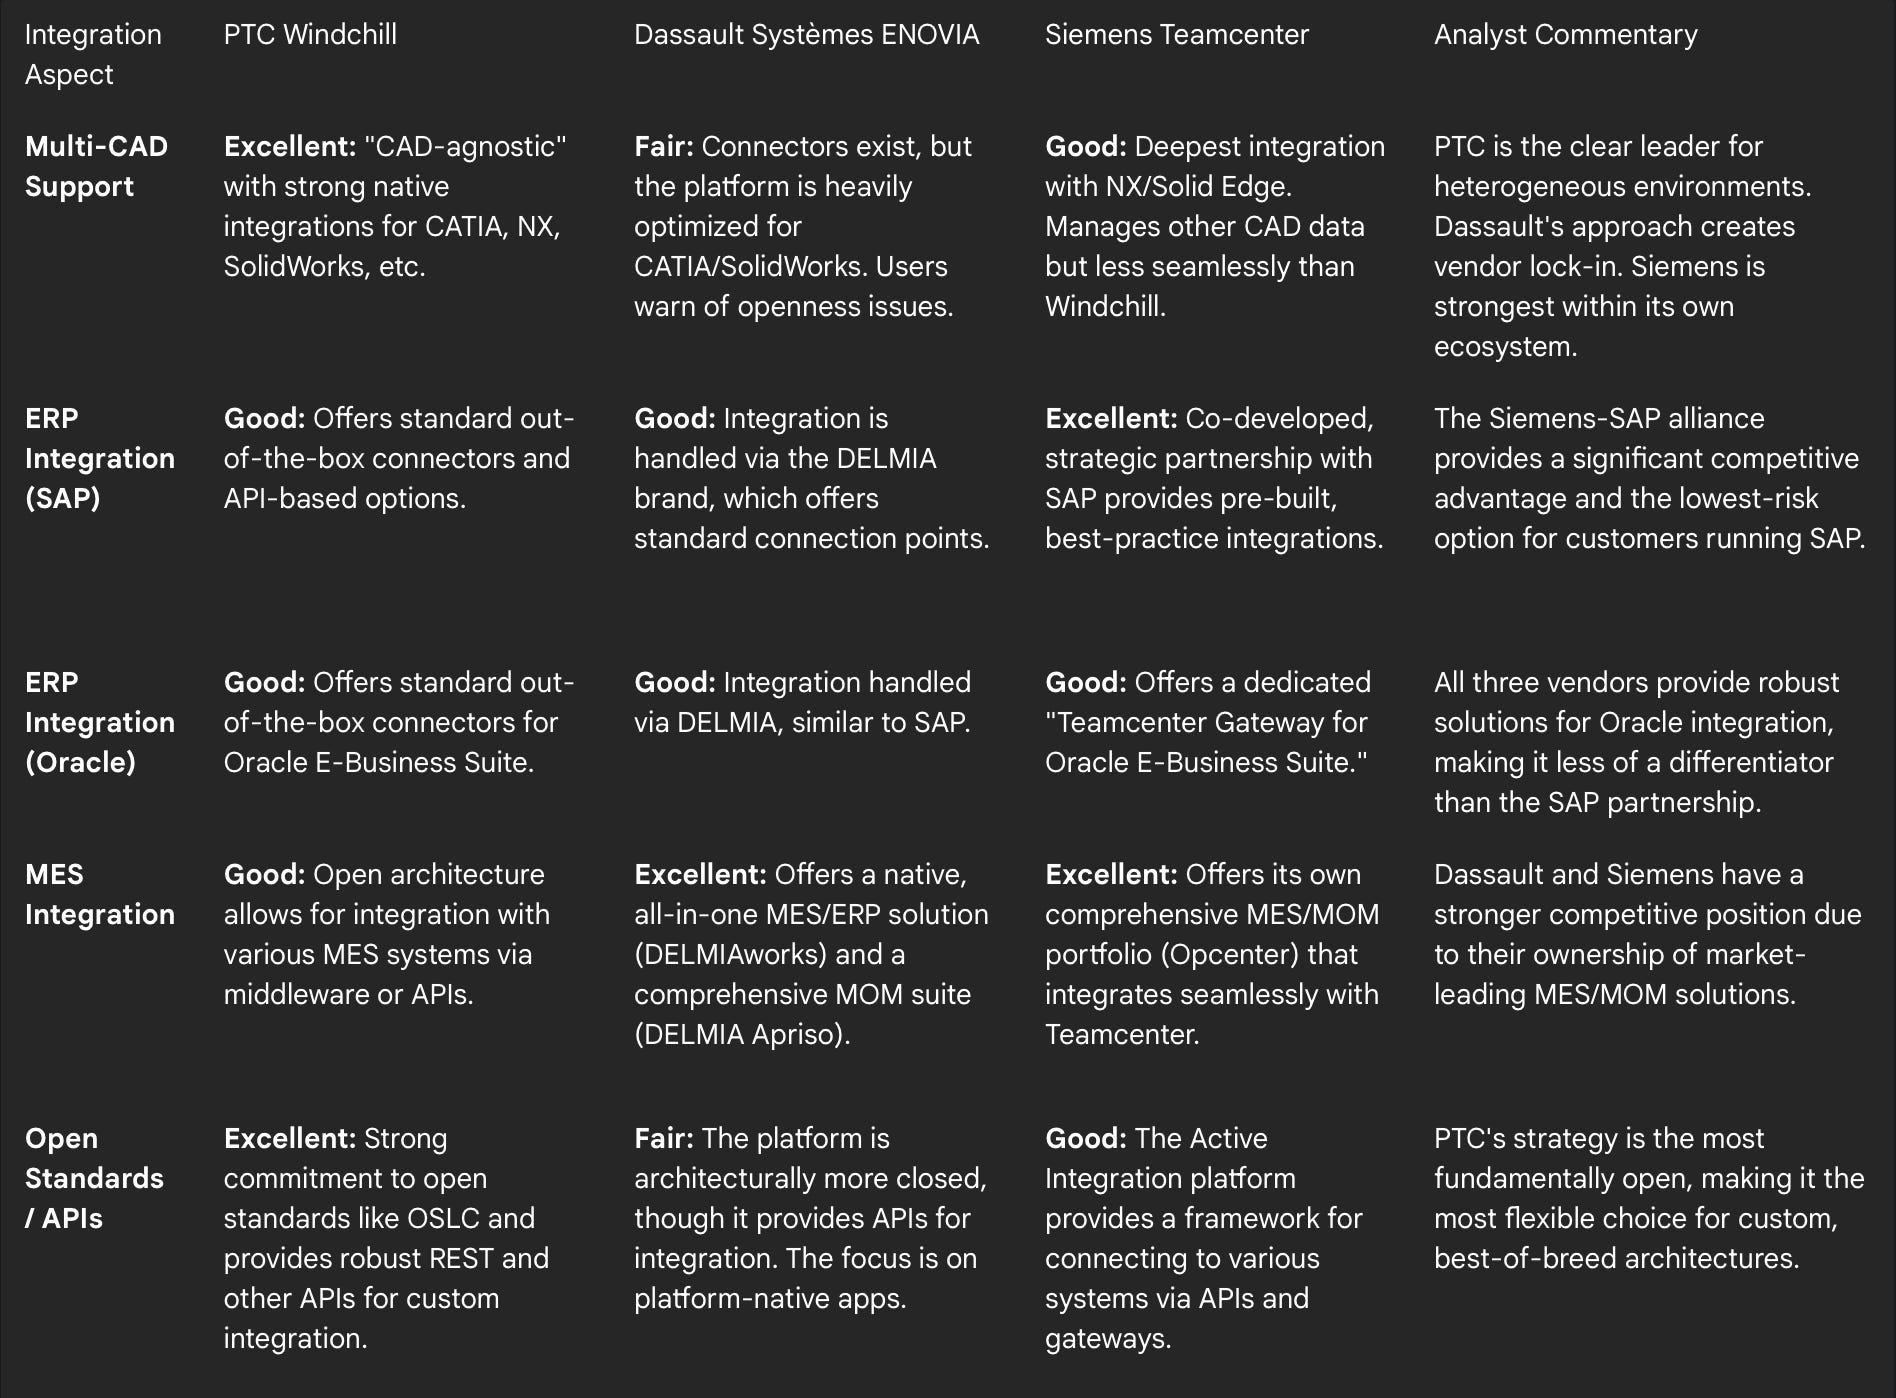
As noted, PLM is a growing market and there’s space for each of the Big 3, and one isn’t necessarily better than the other - in many cases the customer choice will come down to the specific circumstances. Dassault is operating more of a unified platform and it might make sense for some customers to standardise on it. Whereas customers pursuing more of a technology-open approach, for example, might look to PTC. Siemens is somewhere in the middle. While PTC doesn’t break out Windchill ARR specifically, PLM ARR (which includes Codebeamer and various other applications) has been growing around 15% during the same time the market has grown nearer 8%.
Here’s a clip from LiveWorx 2023. It includes a case study from Volvo AB (the trucks and construction business) showing how they use Windchill in reducing complexity (increasing SKUs while reducing parts):
ALM / Codebeamer
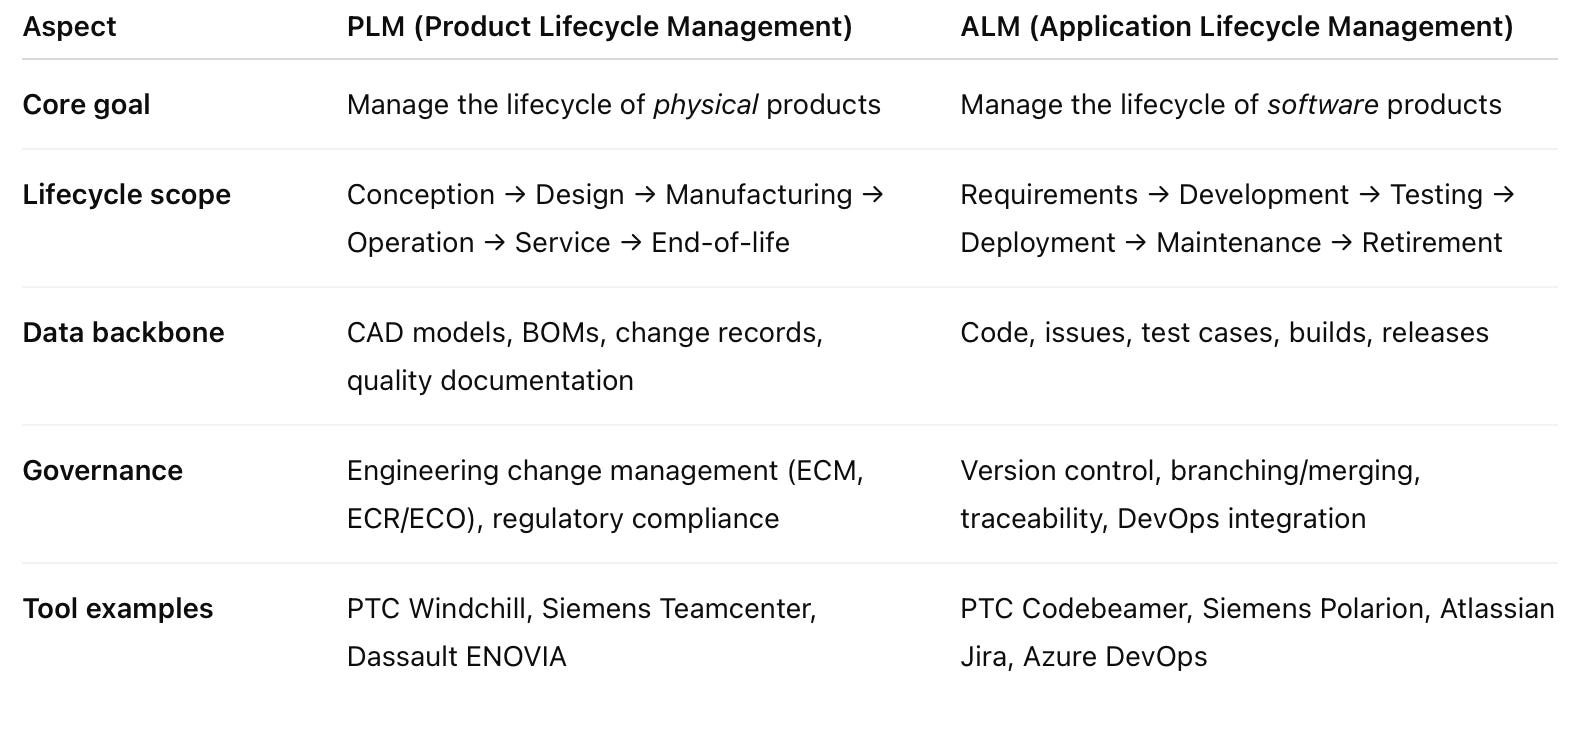
As an overly simplified shorthand you might describe application lifecycle management (ALM) as ‘PLM but for software.’ More concretely ALM extends PLM principles into the software domain: whereas PLM manages the digital thread of mechanical and electronic components, ALM governs the digital thread of software requirements, code, and tests — and their convergence is increasingly critical in digital-physical product development. As hardware becomes increasingly software-defined, the definition of ‘product’ then becomes somewhat blurred. And that’s why PTC acquired Codebeamer in 2022 - being the leading PLM provider, necessitates strong ALM capabilities too. When Codebeamer joined PTC it was doing around $15m in ARR and growing around 40%.
Here’s my ChatGPT cheat sheet:
If you’re curious to see what Codebeamer looks like in practice, check out this introduction webinar.
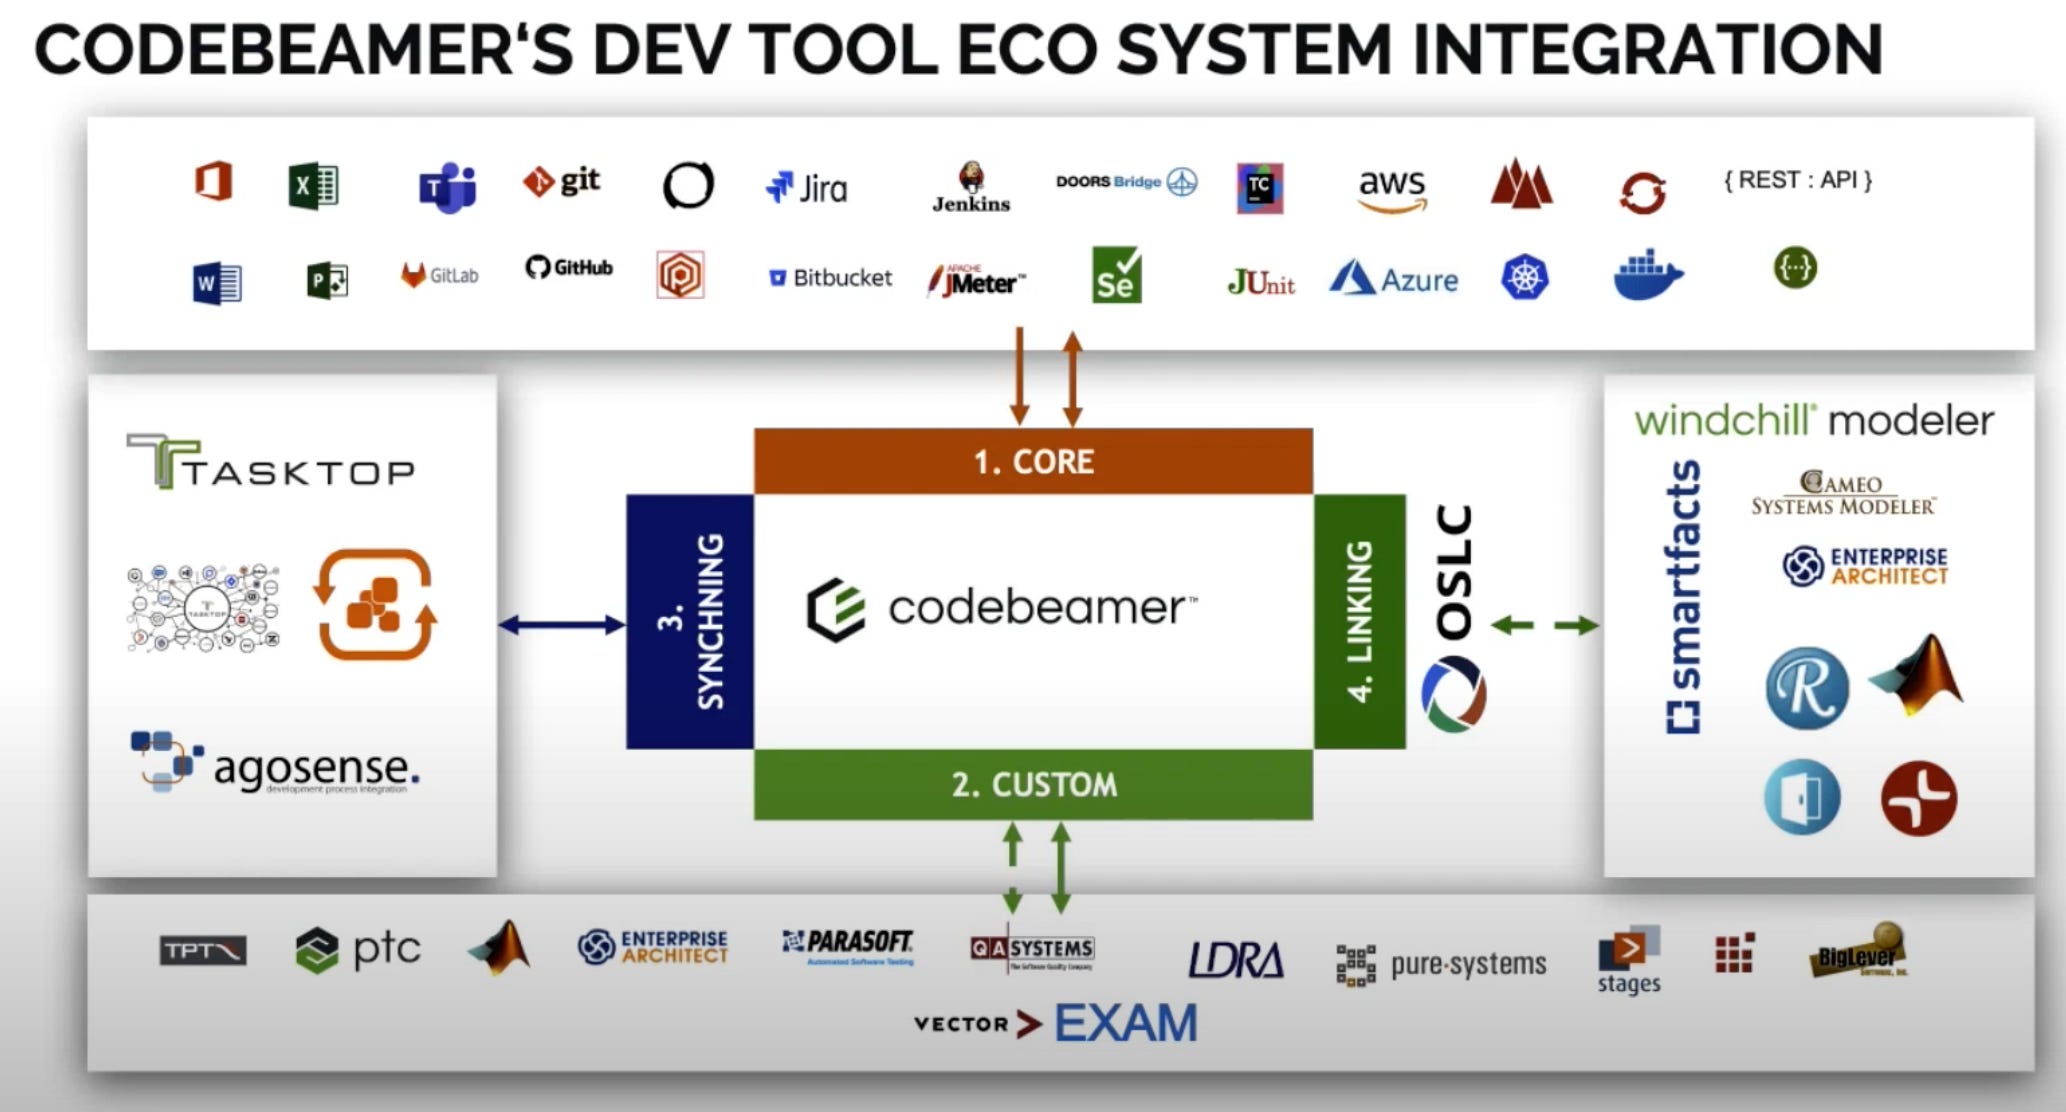
I think one of the more interesting things about ALM is that the market is more fragmented - there’s plenty of scope for more standardisation at enterprise scale, especially among industrial businesses of the sort in PTC’s target markets. Moreover, ALM in this setting is never ‘greenfield’ - it has to work with the other systems that are already there. And this plays to PTC’s philosophy of open standards and inter-operability:
And which of PTC’s acquisitions did Jim Heppelmann consider his best?
A difficult question because there are many good ones, but I think time will show Codebeamer to be the best. Why? Because PTC has now become very strong again in the automotive industry. Historically, we have been known as a sharp tool for powertrain CAD, but today the future of powertrains themselves is unclear. With Codebeamer, we become known as the software development tool for managing the ALM development process. It is a strategic highlight, enabling us to gain strong positions within leading OEMs and suppliers. In addition, it will eventually expand beyond the automotive industry and into virtually every industry. With that, the future of Codebeamer is extremely promising.
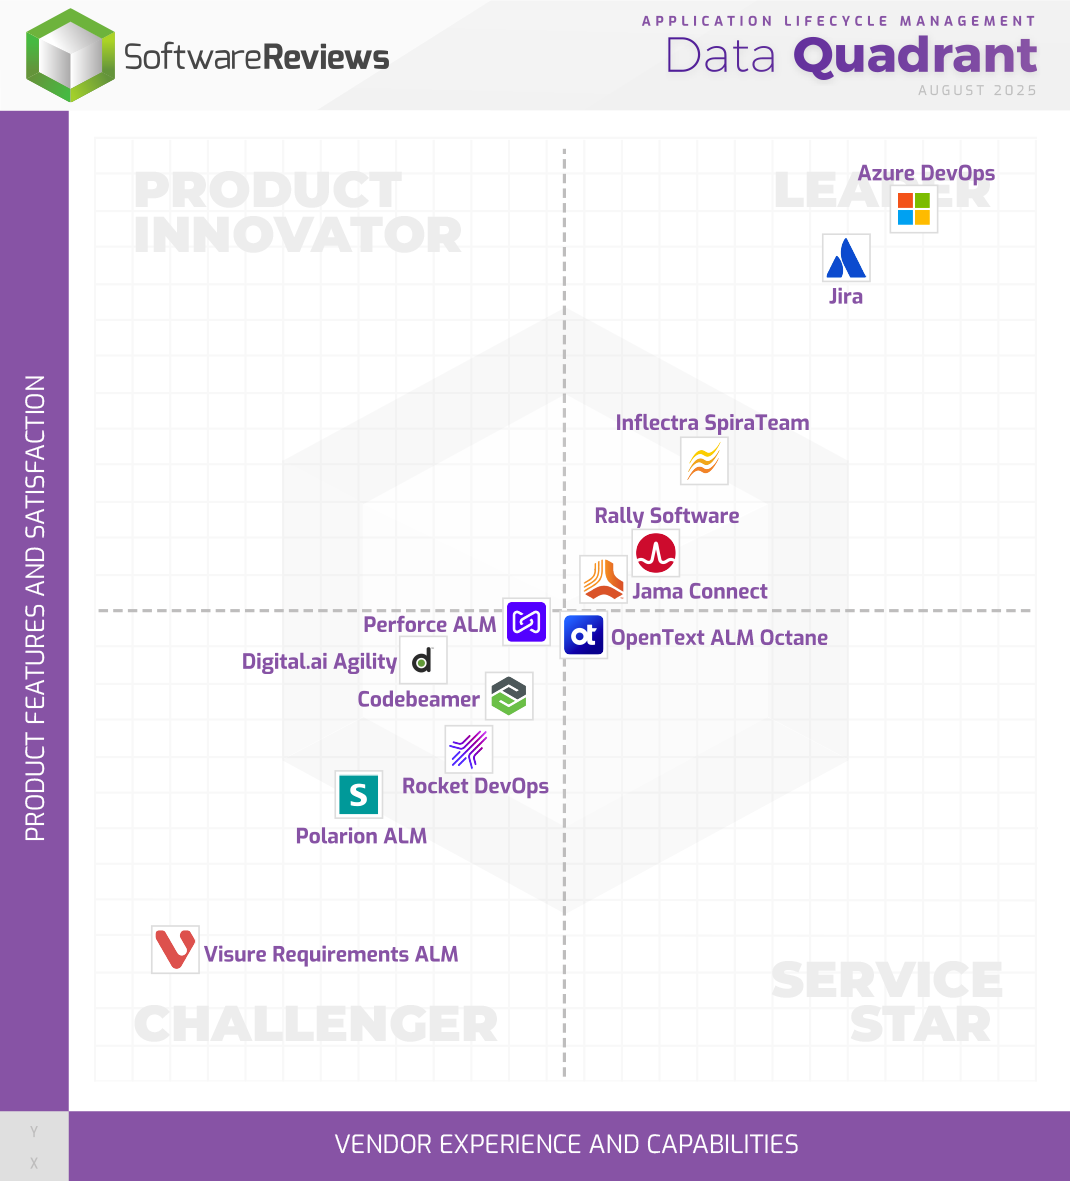
As noted, the enterprise ALM market itself is fragmented compared to PLM or CAD. It’s no surprise to see Microsoft and Atlassian with very popular products in the broader category - but PTC is not really trying to compete with them. Instead PTC is targeting manufacturing businesses within its five focus categories. And in fields such as automotive or medical devices, traceability and compliance are especially important - this is where Codebeamer excels. For existing Windchill users, the choice to use Codebeamer is close to a no-brainer, while Siemens and Dassault customers often use it too.
BMW Case Study
By serendipity (rather than design) I’ve spent rather a lot of time looking at both PTC and one of its major customers - BMW. As you may recall from Part I of the BMW deep dive, BMW embarked on a multi-energy strategy based on a single vehicle architecture - different drivetrain variants (ICE, PHEV, PEV) rolling down the same production lines in the same model. Also in Part III we talked about how BMW uses complexity itself as a source of competitive advantage. While newer competitors are standardising on fewer models and options to keep costs low, BMW does the opposite - more models, more customisability, while still managing cost effectively.
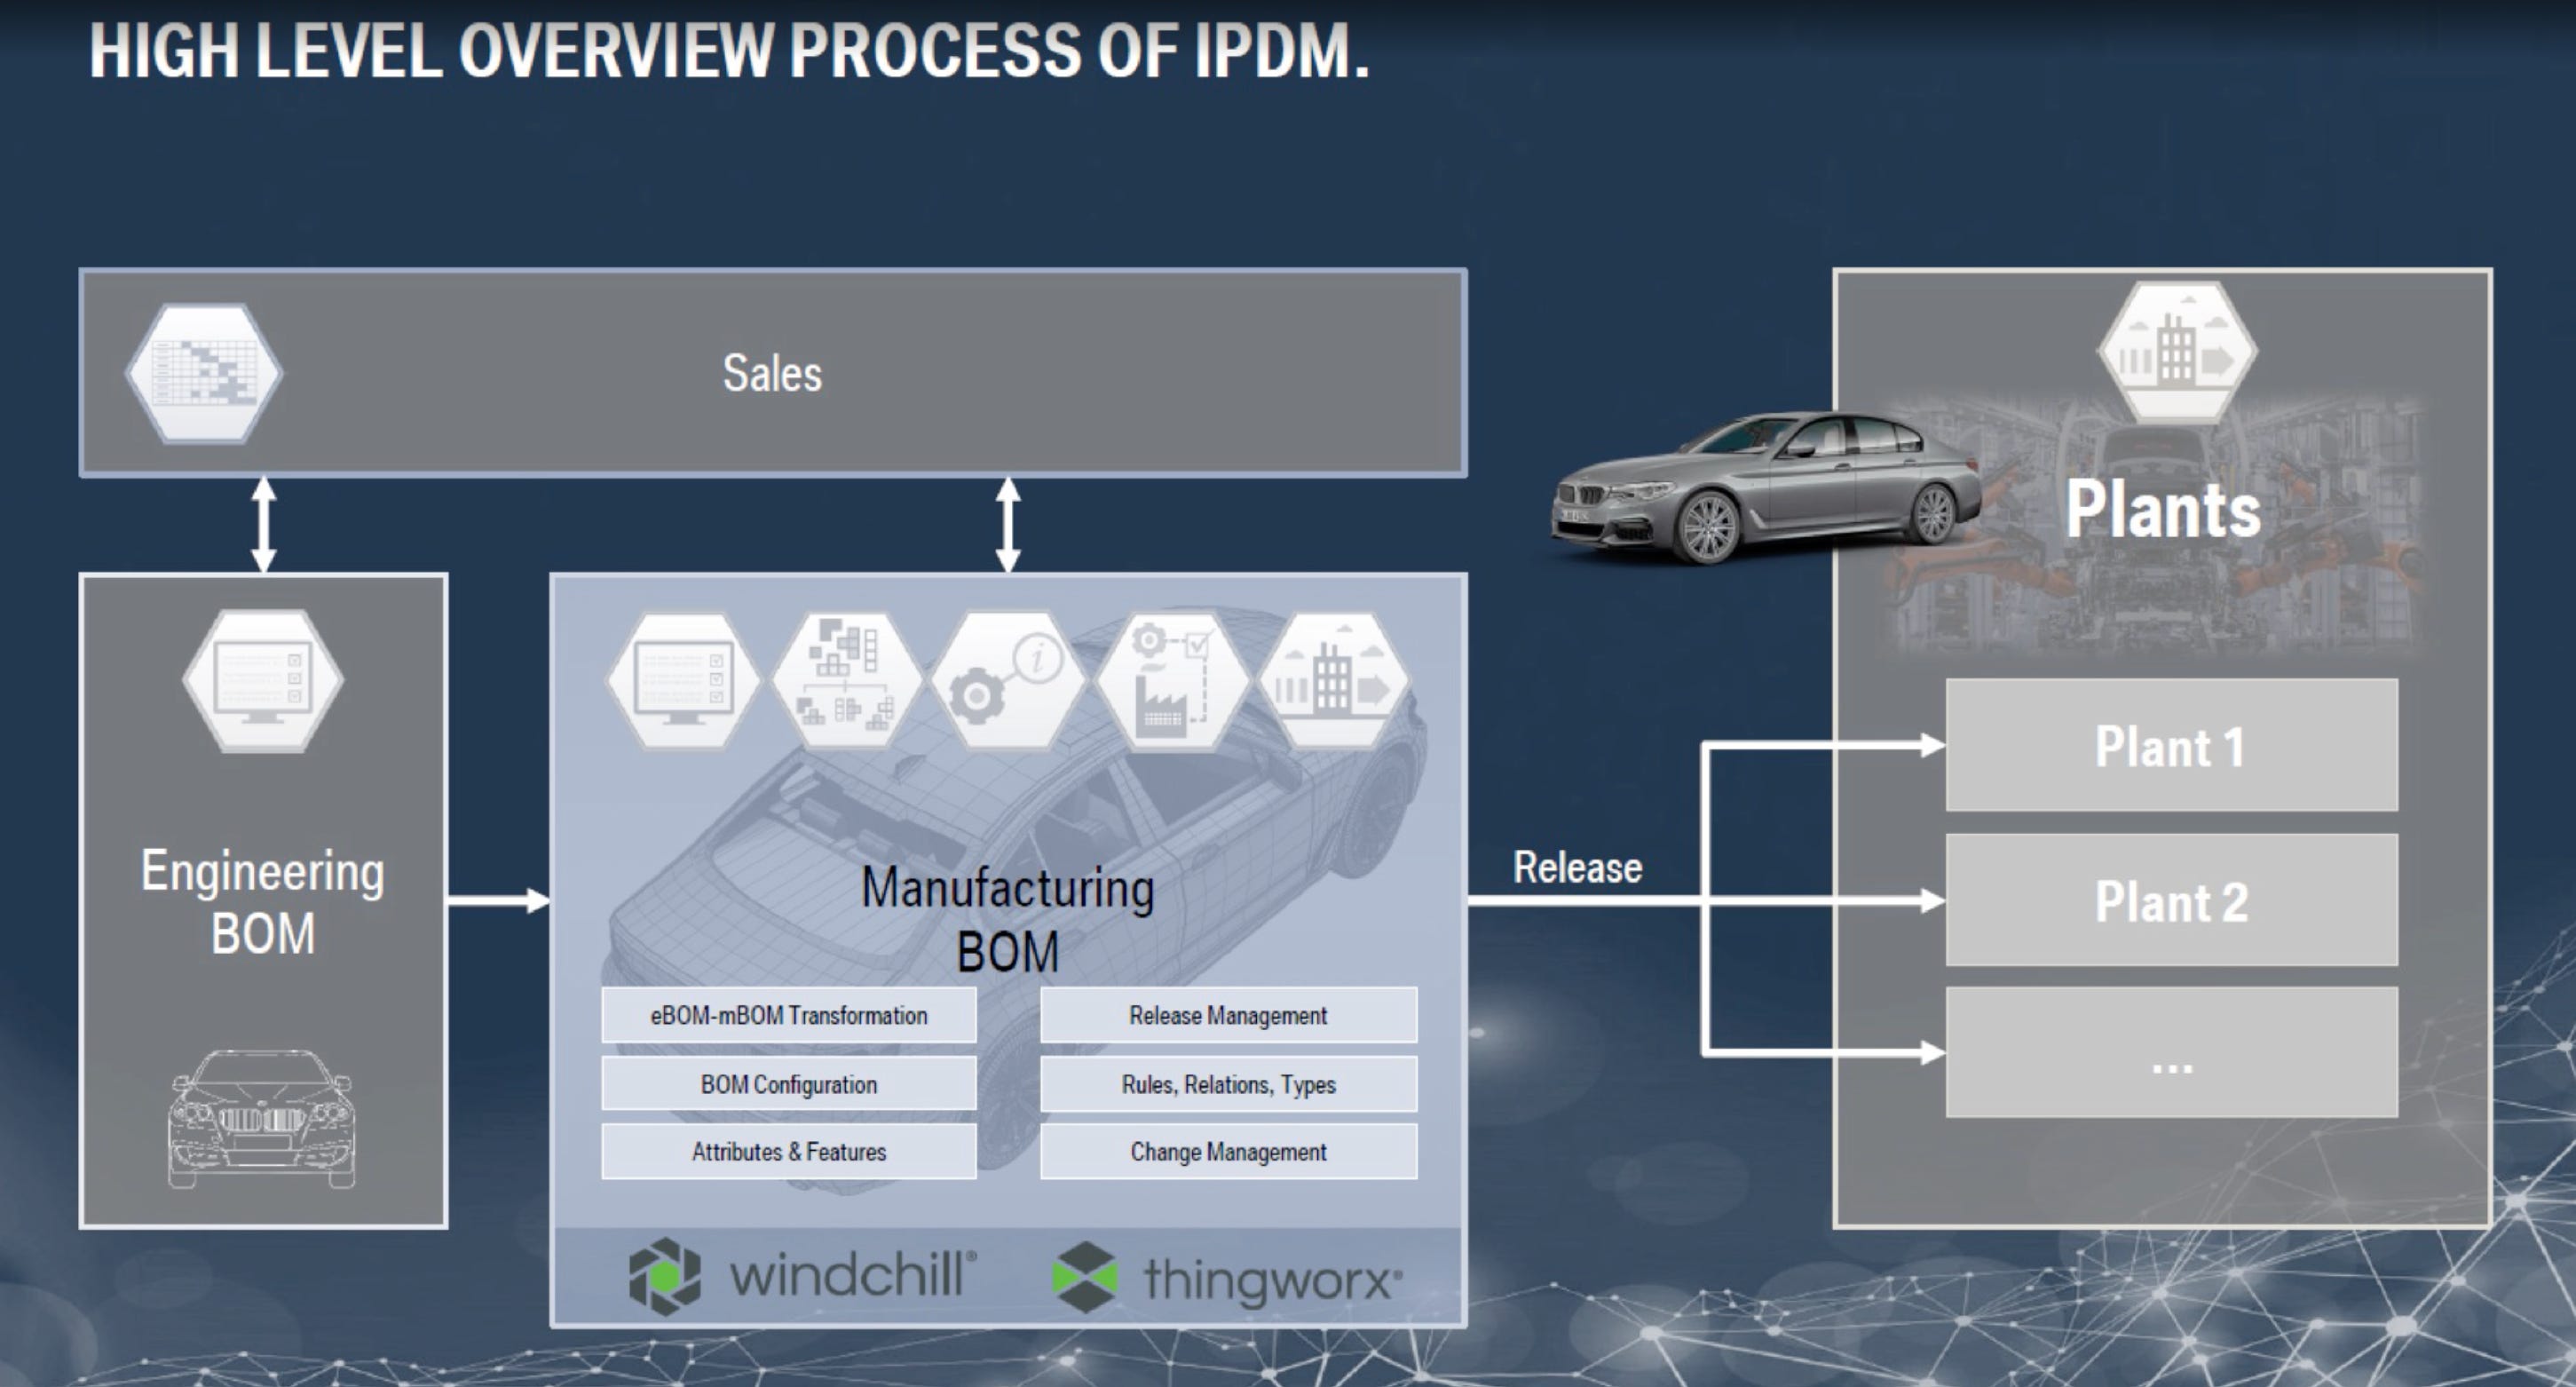
As part of the transformation and a shift towards Agile development, BMW adopted Windchill for manufacturing/production bill of materials, starting 2018 - displacing SAP and legacy systems. In managing complexity and a practically infinite number of possible vehicle configurations, Windchill therefore becomes indispensable:
BMW’s multi-energy strategy turned out to be the right one, and despite the increased complexity the company has outperformed almost all legacy peers since the automotive market peaked in 2017. But there’s more - as we talked about in Part II of the BMW deep dive, BMW has re-invented itself again. Starting this year BMW is launching 40 new software defined vehicles (SDVs) in 24 months - a speed that is unlikely to matched by anyone, including Chinese brands. When it begins first deliveries in the coming weeks, the new BMW iX3 Neue Klasse, might credibly be “the most advanced SDV on the market today”. Part of the reason that BMW’s software strategy is in such good shape lies in Codebeamer, which BMW first adopted in 2017 as part of its autonomous driving research before rolling it out more widely. You can hear the story here (video set to play at the right timestamp):
What the wise man does in the beginning, the fool does in the end: in 2023 VW adopted Codebeamer too as part of its effort to sort out its widely publicised software woes. Notably VW didn’t go with Dassault for ALM (who they use for CAD/PLM) - why? Because Dassault doesn’t have an equivalent of Codebeamer. I think it’s a safe bet there will be others - both in automotive and other industries trying to modernise. PTC didn’t acquire Codebeamer until 2022, but as noted, Heppelmann considers it his best acquisition.
CAD: Creo
The professional MCAD market has traditionally been viewed in tiers. Something like:
High-end / specialist: CATIA, Siemens NX, Creo
Mid-market / general use: Creo, Solidworks, Solid Edge (Siemens), Inventor (Autodesk)
MCAD market and Creo’s place within in
You could spend many hours researching and analysing the living daylights out of the CAD market (I have), but it wouldn’t be a constructive use of words here - I’m going to keep it high-level and a distillation of my findings. Ever since the early 2000s (and the woes of Pro/E, described in Part I) Dassault’s CATIA system and Siemens’ NX system have been perceived as the gold standard of high-end CAD. Both systems have origins in the aviation industry, stretching back to the 1960s/70s - to give you an idea of the potential staying power and stickiness of CAD systems. But Pro/E (later Creo) never went away, retaining a solid base of customers in industrial goods, medical devices and defence/aerospace (among others) who valued best-in-class parametric modelling capabilities. These days all three systems are widely used globally and across industries with complex modelling requirements and large component assemblies. In practise, many large manufacturing business use more than one system, while designers and engineers will retrain as they switch jobs and go from one system to the next. All three are incredibly powerful and capable systems (and each company will tell you their’s is the best). These are also the most expensive MCAD systems on the market - annual pricing for a seat can easily be upwards of $10,000 (even $20,000+) once you include optional features - that said, even with opaque pricing it’s generally no secret that CATIA is the most expensive.
Below the high-end you have general use mid-market systems where requirements are less specialist or demanding. They’re still very capable and powerful systems but more cost effective and potentially faster to use, which might be important for faster development cycles. The big beast here is Solidworks, which is pretty much the industry standard. Note that Creo straddles the high- and mid- range, due to its comparatively low entry level pricing of ~$3000 which is about the same as Solidworks. In recent years, would-be usurpers have emerged from below - Autodesk’s Fusion (formerly Fusion 360) and Onshape are cloud-based systems with much lower pricing (see below).
The MCAD market is approximately in the region of $11bn and split roughly evenly in value between specialised and general-purpose. While PTC’s overall share is relatively modest (<10%), since 2019 when the subscription model transition was completed PTC’s CAD ARR has been compounding at around 12% which is around twice the market. So why has Creo been outperforming? One of the reasons is the nature of the subscription model transition which itself has provided structurally higher growth as a matter of course (see Part I), and PTC threw itself into this process earlier than peers. But also recall the growth algorithm from Part I with up-sell sitting at the top. We talked about how Creo was designed to be modular - there are all sorts of modules/extensions beyond the basic package and a pipeline thereof. Moreover, pricing is relatively transparent for CAD world. Of course, Dassault and Siemens add new features too, but from what I can tell, PTC just tries to make it easy to turn them on (and off). Perhaps the most notable extensions (and those conferring the greatest competitive advantage) are Creo Simulation Live (CSL) and Creo Ansys Simulation (CAS) - both in partnership with simulation leader Ansys. Through a partnership with Ansys, PTC can offer best-in-class simulation capabilities within the Creo environment. Additionally, with CSL users can perform live simulations with near-instant feedback - which can make design and prototyping much faster and cheaper. CAS brings higher capability still within the Creo environment, but without realtime functionality. CATIA and NX offer neither live simulation with instant feedback nor Ansys within their CAD environments - and probably never will often Ansys. You see, both Dassault and Siemens decided to enter the simulation field through acquisition some years ago, thereby competing head-on with Ansys. As a non-combatant, PTC (and with its technology-open approach) was able to enter into partnership with Ansys - and so PTC has best-in-class simulation built into Creo, for a price of course. CSL is priced competitively at around $6,000 per license2 while its upstream use can reduce the need for higher priced capabilities downstream. In addition to the primary up-sell opportunity, it’s a nice advantage to have at the margin on those infrequent occasions when the customer is considering a change of system or directing investment where they have one than one.
If you want to go deeper into Creo/Windchill/Codebeamer integration on topics such as model based definition, this video with CTO Steve Dertien might be a helpful place to start.
CAD: Onshape
PTC has another CAD system: Onshape. One of the least visible parts of the business currently, it’s also one of the most exciting and disruptive in my view. PTC acquired Onshape towards the end of 2019 for $470m. ARR at the time was not disclosed. PTC’s own disclosures put ARR at ~$10m at the beginning of FY21 and over $15m a year later, after which they stopped breaking it out. In the recent words of founder John Hirschtick it’s still growing “pretty dramatically”. I assume Onshape ARR is currently in the ballpark of $40-50m and perhaps only 2% of PTC’s total. So why should we even care? I believe Onshape could grow to be larger than Creo eventually - actually I think it will. So it’s worth taking the time to explore in a little detail. Onshape’s origins and how it came to reside at PTC make for a compelling story and it’s worth getting into if you’re considering PTC long-term (also see further reading at the end).
Recall the quote from Part I where PTC’s CEO in 1997 said that Solidworks was flawed and unlikely to succeed. Well imagine my surprise when I realised Dassault’s CEO said something similar about Onshape a few years ago:
To make it simple: I think for Onshape it’s too late. We have far more licenses even on a browser today than what they can refer to.
- Bernard Charles (Dassault Systèmes CEO), 2019
The short version of the Onshape story is this: John Hirschtick founded Solidworks in 1993. The early team who built the company included John McEleney and numerous others. They raised $1.5m in venture money. Dassault acquired Solidworks in 1997 for $310m at around 12.5x revenue. SW was managed largely as a separate entity and Hirschtick and team remained there until 2012, at which time much of the original SW team left to start Onshape. From customer meetings, it had dawned on Hirschtick that there were all sorts of unacceptable challenges and issues with legacy CAD that were causing real problems - installations, versions, instances, file conflicts - that couldn’t be fixed without rebuilding it to be cloud-native. The necessary meeting of minds did not happen at Dassault, so he had to start a new company if it was going to happen. This time they raised $169m in venture money and took four years to build it - building cloud-native CAD turned out to be a tough engineering problem. One of the key insights they had was to build the PDM part of the system first, and then to build CAD around it - as opposed to adding the PDM to the CAD as an afterthought. And so Onshape is architecturally very different to other CAD systems on the market:
fully cloud native
Works on Mac or PC (most other CAD systems are PC only)
runs on anything without installation: desktop, notebook, tablet, smartphone (most other CAD systems require local installation on a high-performance PC/workstation)
no CAD files (no check-in / check-out)
Realtime co-editing of the same model/parts
Branching/merging for design exploration
Sharing - CAD models can easily be shared via link with colleagues/third-parties with edit/view permissions set accordingly.
Automatically updates every few weeks (always on latest version)
FeatureScript - with open source, users can create and share their own CAD features
Onshape App Store - integrated/connected apps and extensions from PTC (e.g. Arena PLM) and third-parties
Onshape is the Google Docs or Figma of CAD - it permits completely new and faster ways of working that are simply not possible on legacy CAD. It’s also about half the price of Solidworks (and recall you don’t need a high-end PC to run it). One of the (few) complaints you hear about Onshape is lack of features compared to Solidworks. While this was certainly true at launch in 2015, they are continuously adding new features and many of those considered absent previously are now there (e.g. CAM, Simulation, sheet metals etc). There’s also FeatureScript and the App Store.
Here’s a recent webinar hosted by John Hirschtick (now “Chief Evangelist” at Onshape) with Alternative Engineering Inc, discussing the reasons behind their move from Solidworks while demoing some of their complex Onshape models running smoothly on cloud infrastructure. Per AEInc. they save hundreds of hours per project, on Onshape compared to Solidworks:
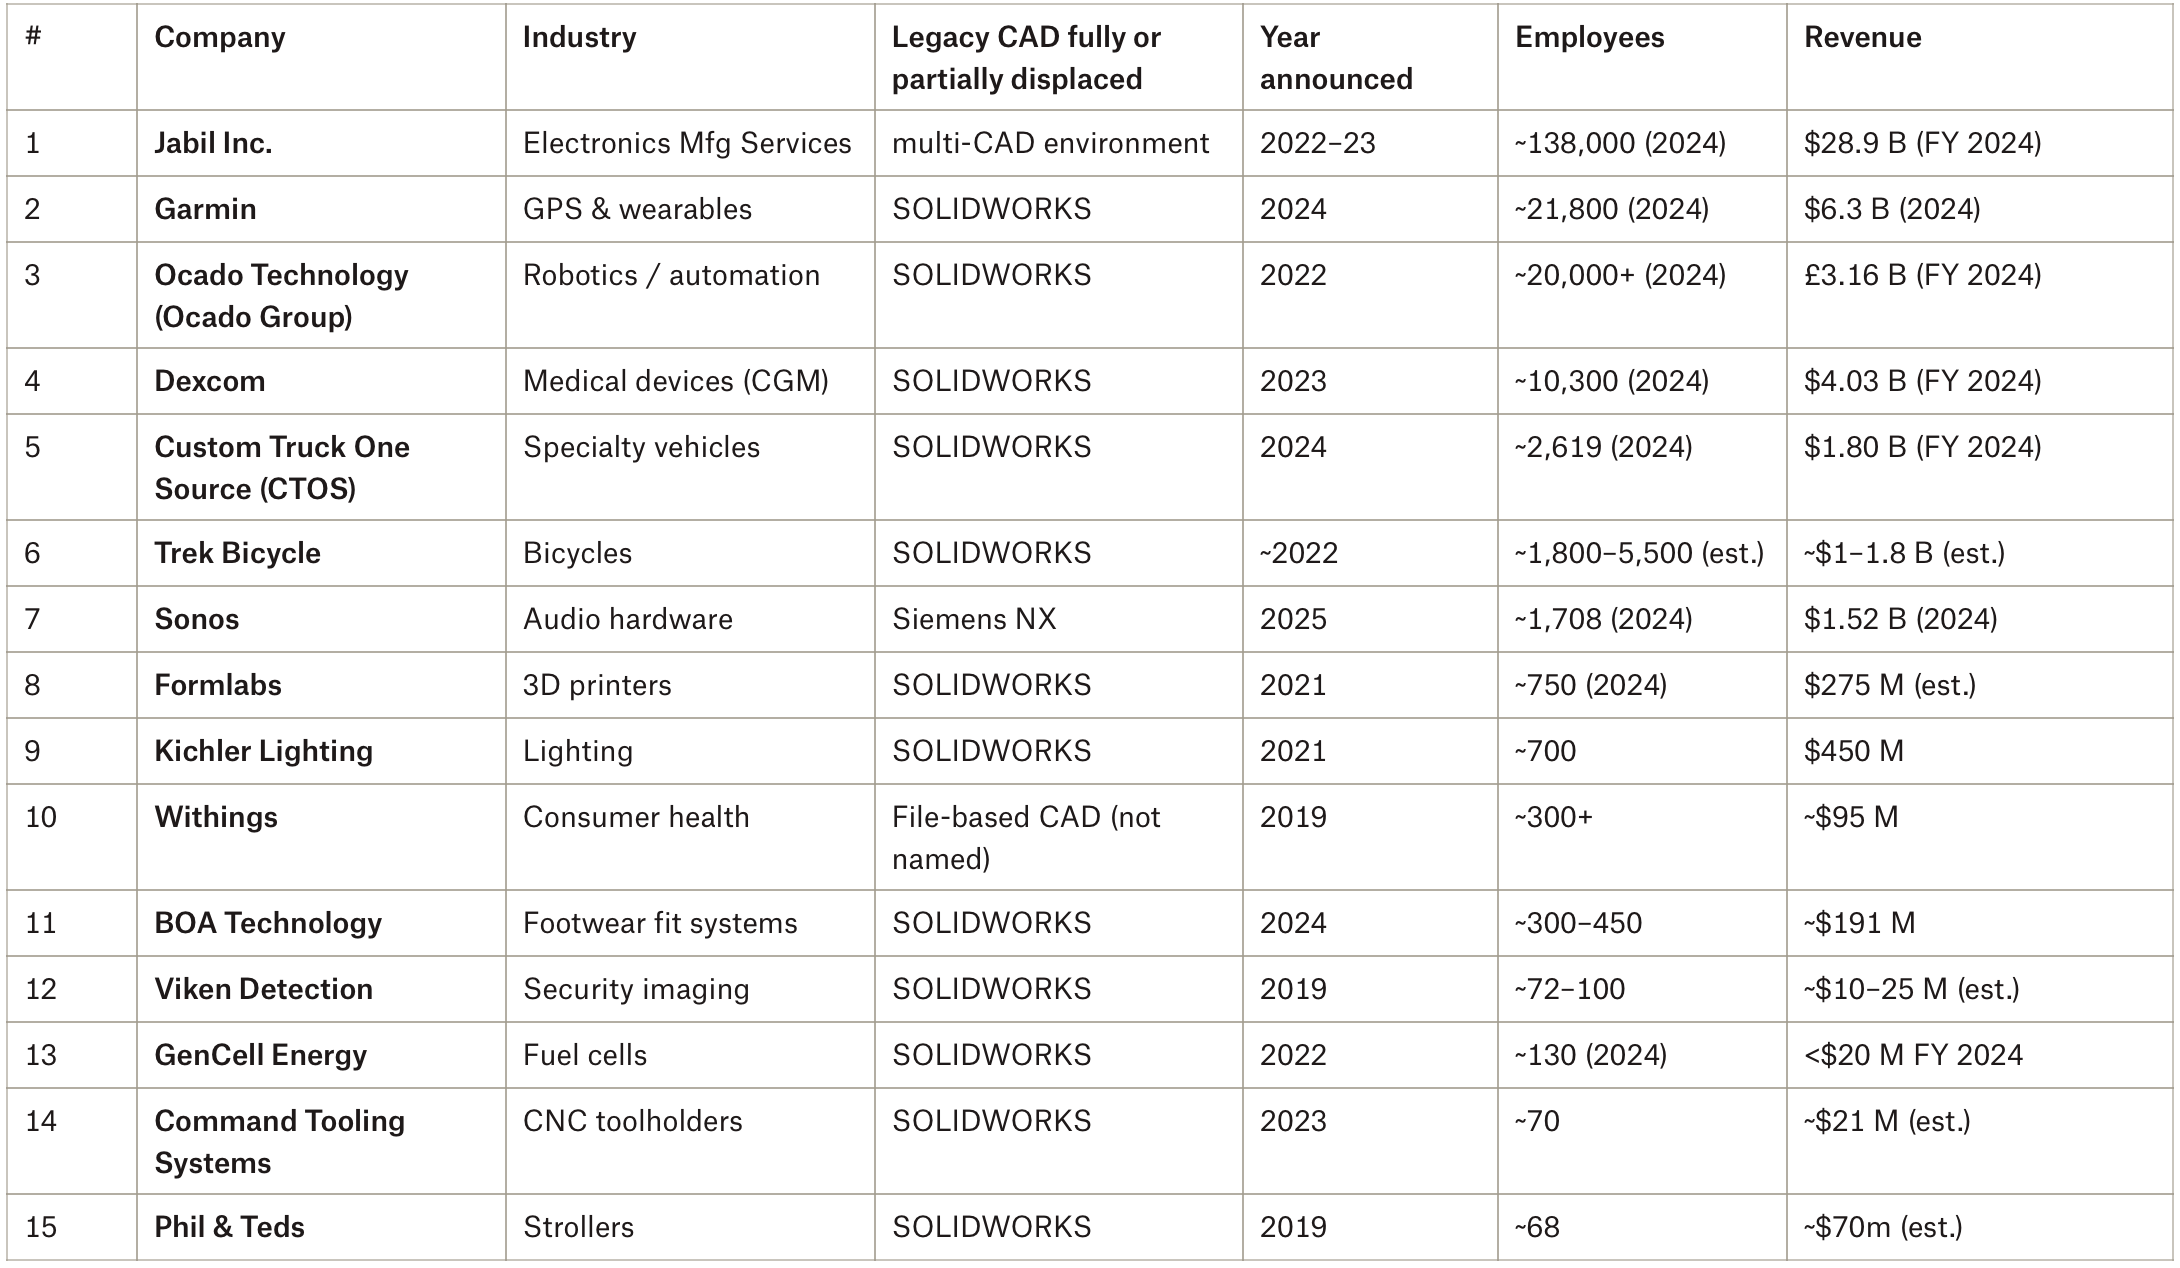
While it’s difficult to picture from such a small base, it seems more likely than not that Onshape will be a much larger business in future. It will just take time. As disruptive as Onshape is, CAD is incredibly hard to displace. This makes truly parabolic earlier-stage growth, equivalent to Figma’s, impossible to achieve - despite a similarly disruptive product. But customers are switching anyway - from Solidworks in particular - and Onshape is growing. Once engineers are onboarded and up to speed on the new way of working, they prefer it almost universally. So while uptake might be slower than Figma due to switching costs, those switching costs re-establish themselves once new customers are in - they’re not going anywhere else. I spent an hour one morning asking Gemini and ChatGPT to come up with a handful of businesses that had adopted Onshape and which CAD systems they had used previously. For the most part Gemini and ChatGPT came up with different names. While I spent a little time trying to confirm or clarify some details (e.g. on which legacy systems were used), I spent zero time trying to research a list of business names myself. See for yourself who is being displaced:
I see two further sources of growth emerging over time. The first is from the new generation of digital native engineers starting their careers or setting out to create their own businesses. Onshape is pushing hard on this door. In fact Onshape is free for anyone to use - try it for yourself, I have an account. The main difference with the standard paid plan is that you can only store your models publicly. The professional paid plan (~60% premium to standard) bundles advanced features such as CAM, simulation, rendering etc. Critically, there’s also a specialised free Educator program, with features for classes and assignments and bundled simulation functionality. Education signups currently run into the millions (in user numbers, if not revenue, growth truly has been parabolic). Then there’s the Onshape Startup Program - if your product design startup meets certain eligibility criteria you can have five professional seats guaranteed for one year (after which you can re-apply). Dassault, as you might imagine, also pushes Solidworks to students (for a modest price) and to startups - but there isn’t a free version available to everyone and neither is it cloud-native with all the associated benefits discussed before. This is where the battle for hearts and minds will be won - as Hirschtick likes to point out, younger people coming into the workforce will eventually have to be trained on how to use file-based systems if that’s what their employer still has.
The final source of future growth is from the gradual snowballing of features added to Onshape - over time I would expect Onshape to become a legitimate competitor to the high-end CAD systems.
A few years ago Jim Heppelmann popped up expectedly in the Onshape user forum. This is what he wrote:
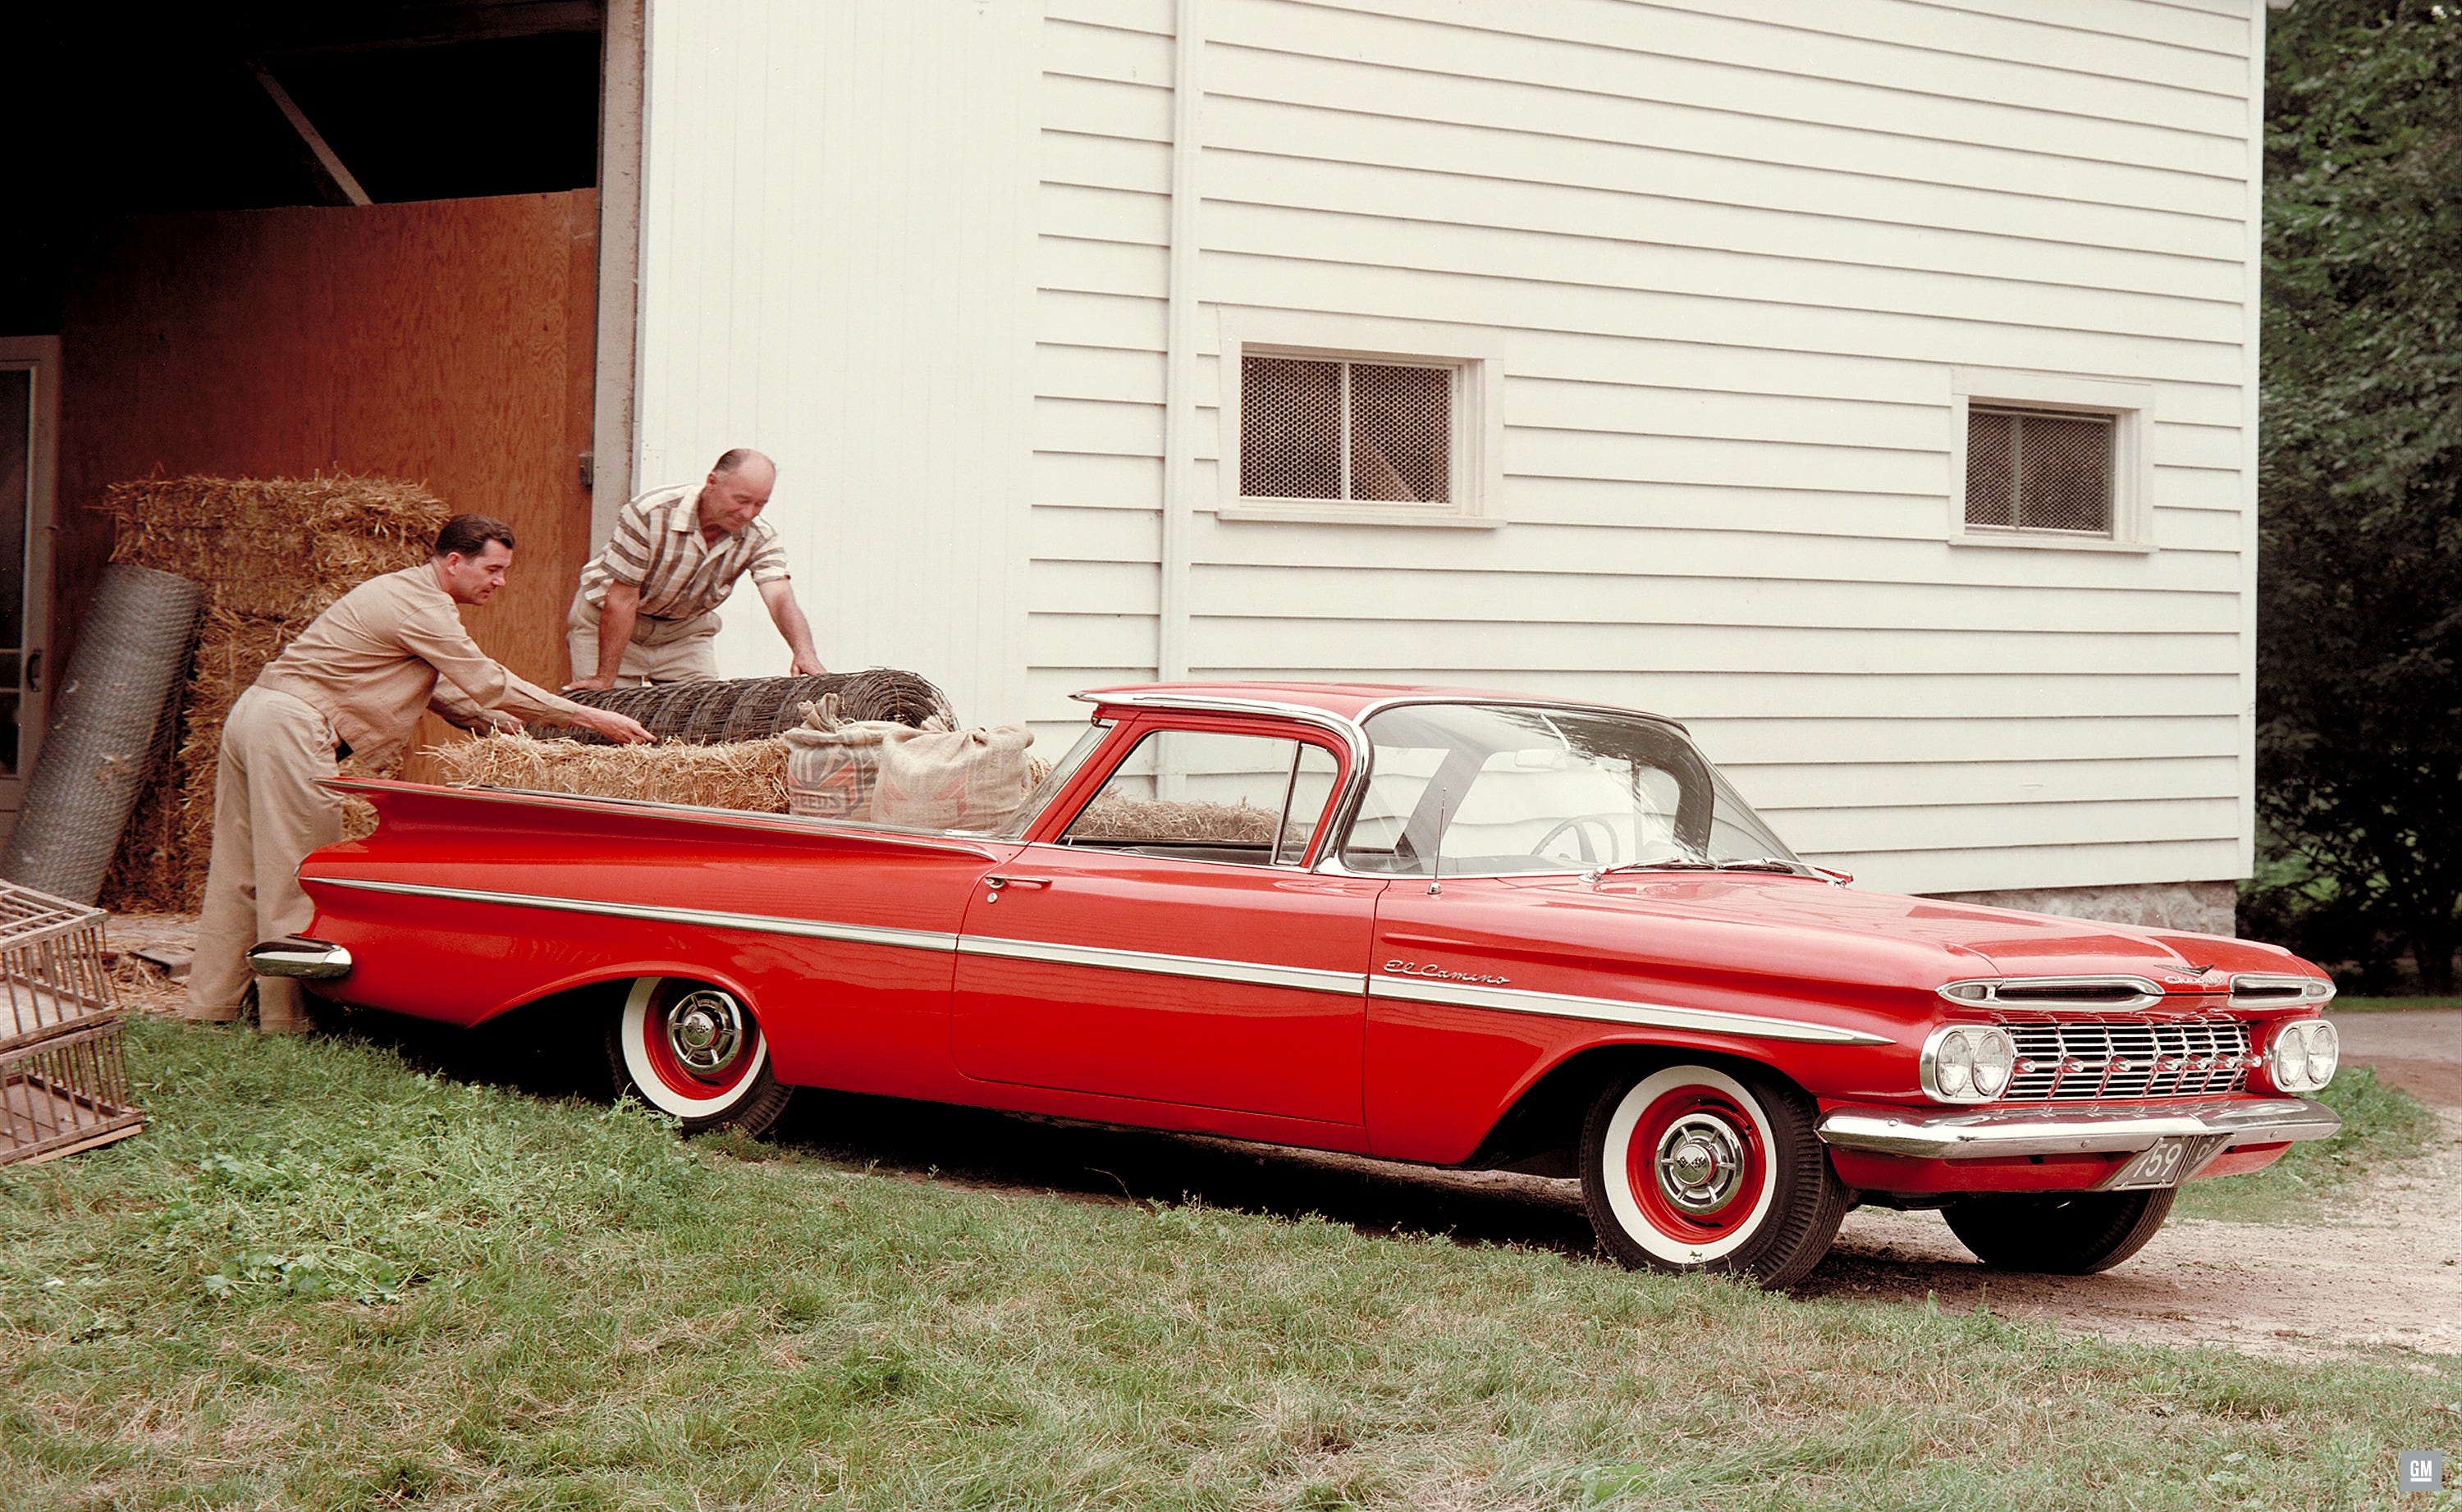
I fully believe Onshape and Creo will both be alive and well decades from now, and both will be market leaders. They will share a lot of code, but will have important differences and focus on somewhat different objectives. Sort of like a sedan, an SUV, and a pickup truck are all just automobiles that provide transportation, but with important nuances that attract different buyers. The differentiation will NOT be high-end versus low-end as it is at Dassault and Siemens, because there is no glass ceiling for Onshape and we want both products to be very advanced and powerful. The simple answer is that we want to focus Onshape/Arena on Agile Product Development (i.e., develop hardware like you develop software using Scrum, etc.) while Creo/Windchill focus more on "platforms" (i.e., companies that have broad portfolios of products that share many common elements and therefore configuration management rules the day and drives the CAD system). Maybe some users will switch from Creo to Onshape as time goes on, or vice versa, but our goal is that far more will switch from Solidworks and other systems that simply lack the magic that Onshape and Creo share via Atlas. The point is Creo and Onshape are not merging together (no Chevy El Camino in our future) and neither is going away. Not now, not ever.
Sidebar: Atlas & a word about SaaS
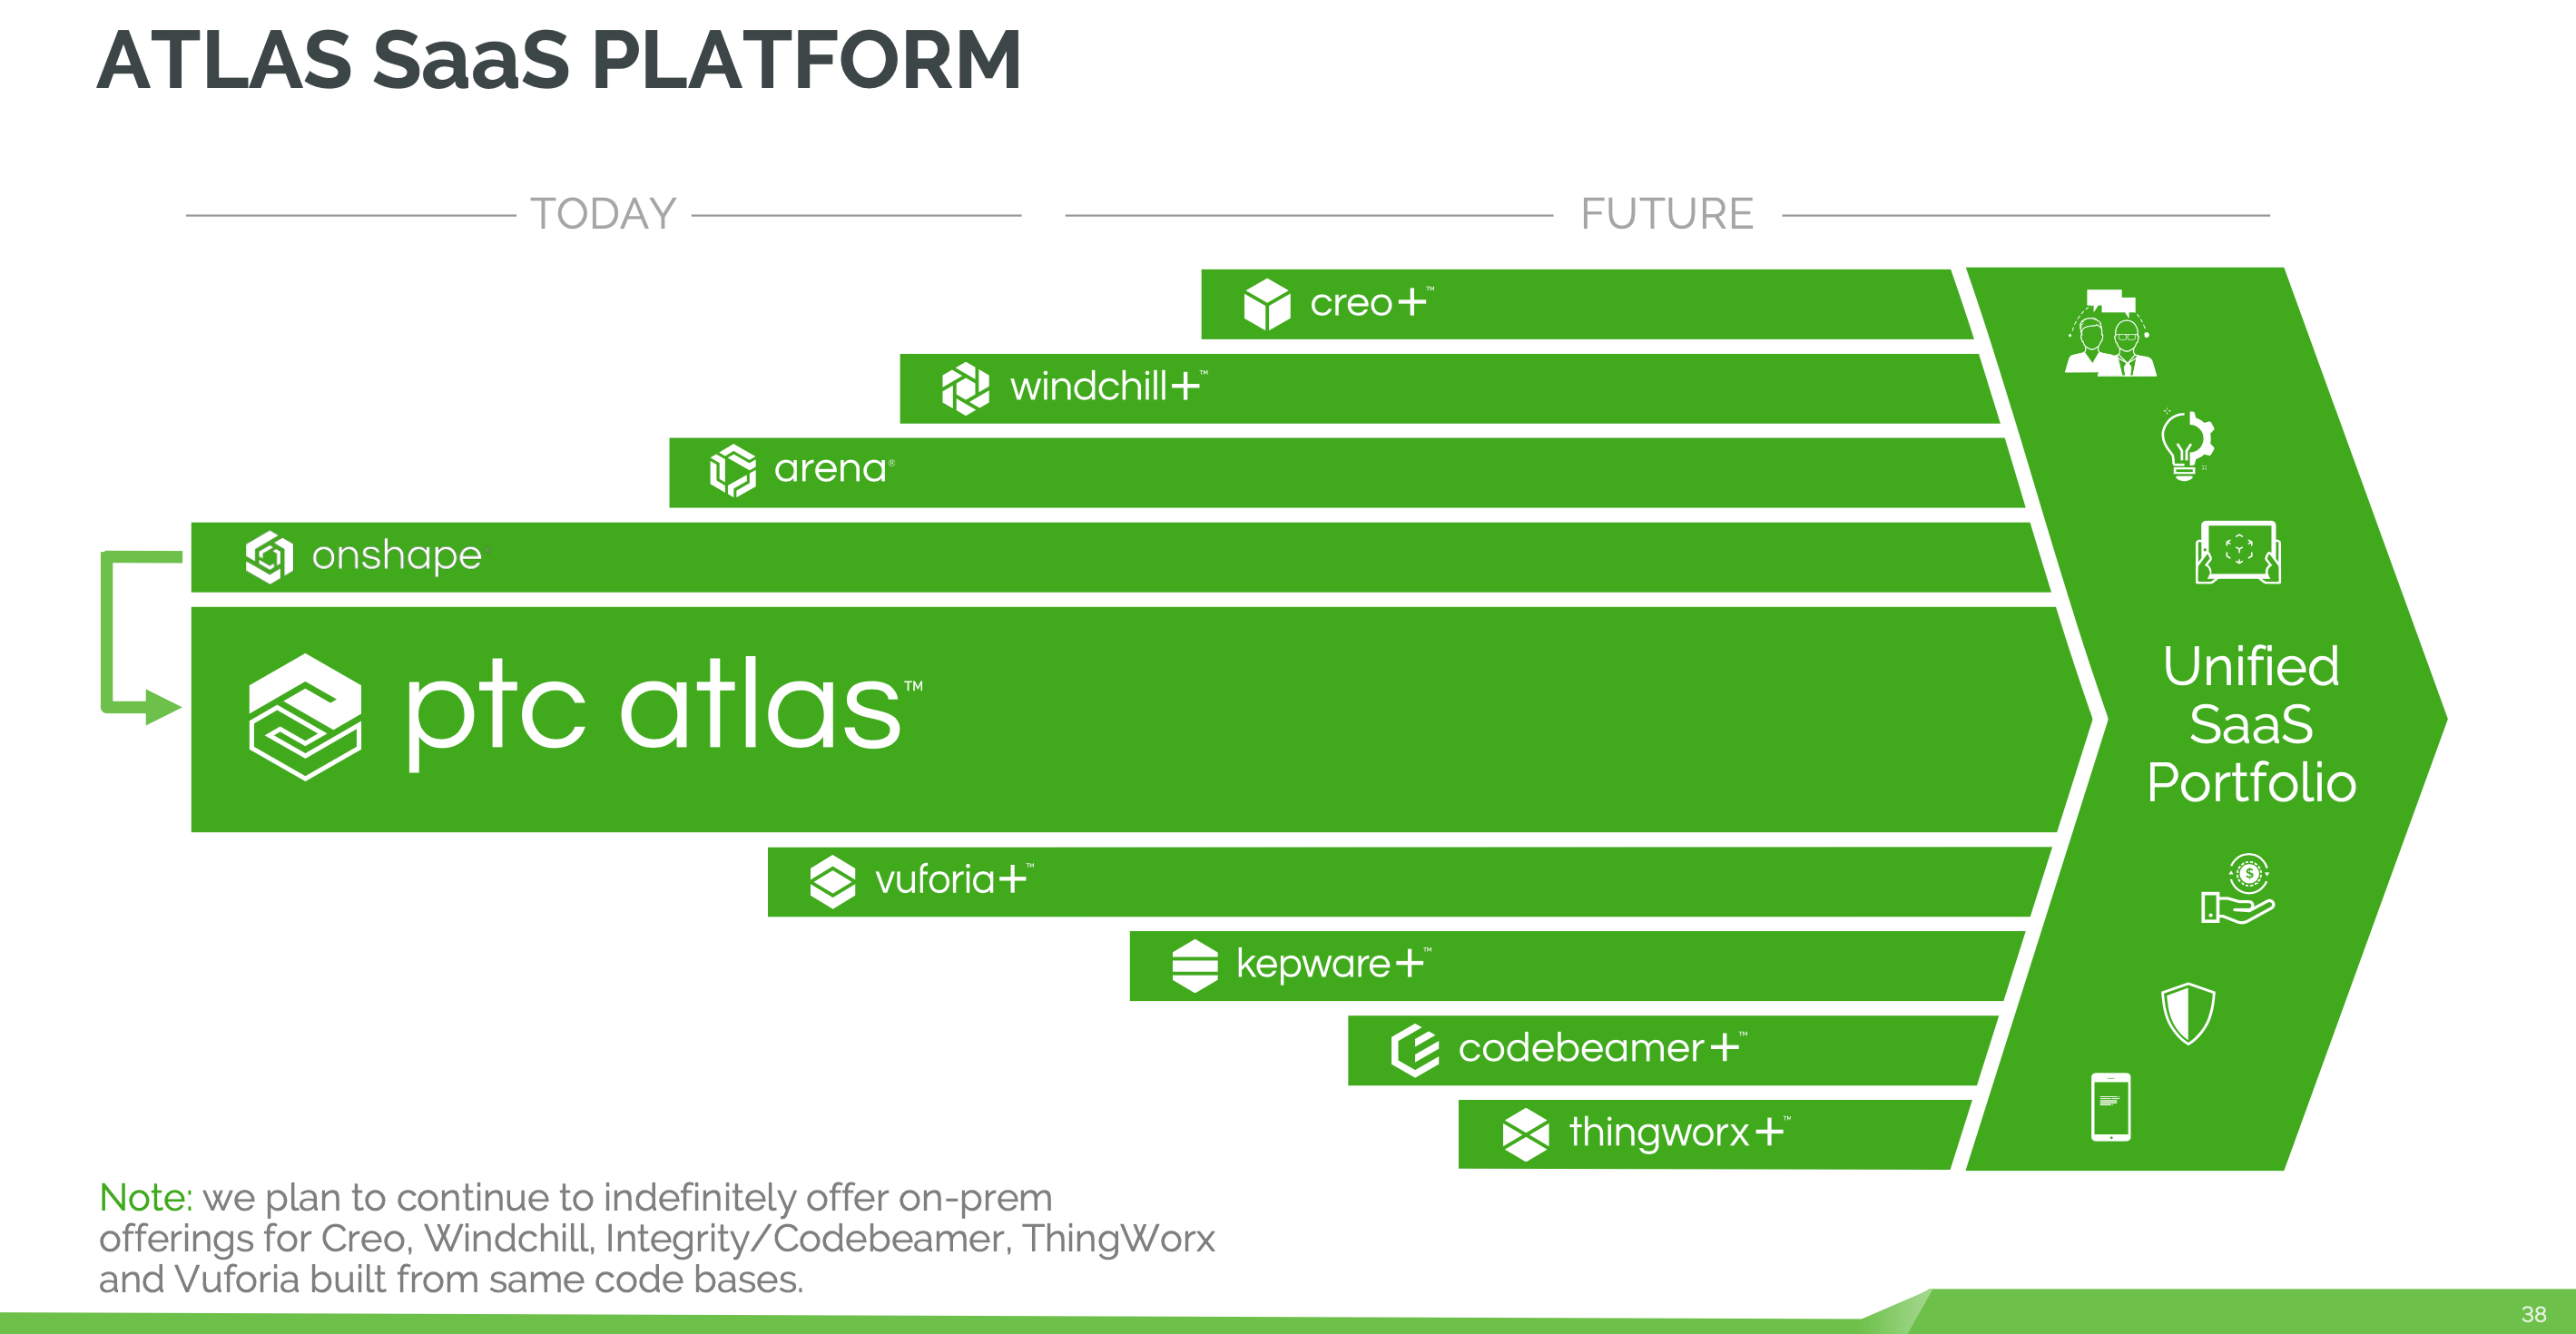
Atlas is PTC’s term for Onshape’s cloud architecture, which they have adopted as the underpinnings for much of the rest of the portfolio:
It’s worth recalling the distinction between ‘Velocity’ and the rest of PTC (‘Digital Thread’). Velocity comprises Onshape and PTC’s cloud-native PLM product, Arena. I have chosen not to go deep into Arena in this post, but PTC have positioned it as the natural choice for Onshape users rather than Windchill - having said that I’ve just learnt that they’re working on an Onshape/Windchill integration due to customer demand so watch out for developments there. Here’s Heppelmann again, at the point of retirement last year:
We have positioned Onshape and Arena for Agile product development, especially aimed at startups, new companies or new divisions of existing companies, i.e. players who want to run product development like speedboats instead of ocean-going ships. Fast and flexible. In general, the entire software development industry has moved to Agile as a development methodology, but on the hardware side, they haven’t. Almost no companies develop cars, airplanes or construction equipment using Agile techniques. They use waterfall or stage-gate techniques. So, we’re going to focus Onshape and Arena on the cutting-edge new product development method called ”Agile” and enable companies to simultaneously use Agile on both the hardware and software sides of their product development processes.
Not only are Onshape and Arena managed separately, they also run on AWS, whereas PTC’s ‘plus’ products run on Azure. More on Onshape/Arena for Agile product devlopment:
Starting a couple of years ago, PTC began to release its two core CAD/PLM systems with cloud versions, using the Atlas architecture - denoted by 'plus/+’ to signal that it’s the same software as before but with additional features brought by the cloud. Windchill+ is the more SaaS-like of the two, with the various benefits you would expect such as lower IT overhead and regular updates. Creo+ is more of a hybrid system with a local client installation still required but augmented by cloud functionality. For example, despite still being file-based, Creo+ offers similar realtime collaboration and branch/merge features to Onshape - so far as I know, competitors cannot do this yet in quite the same way:
ServiceMax
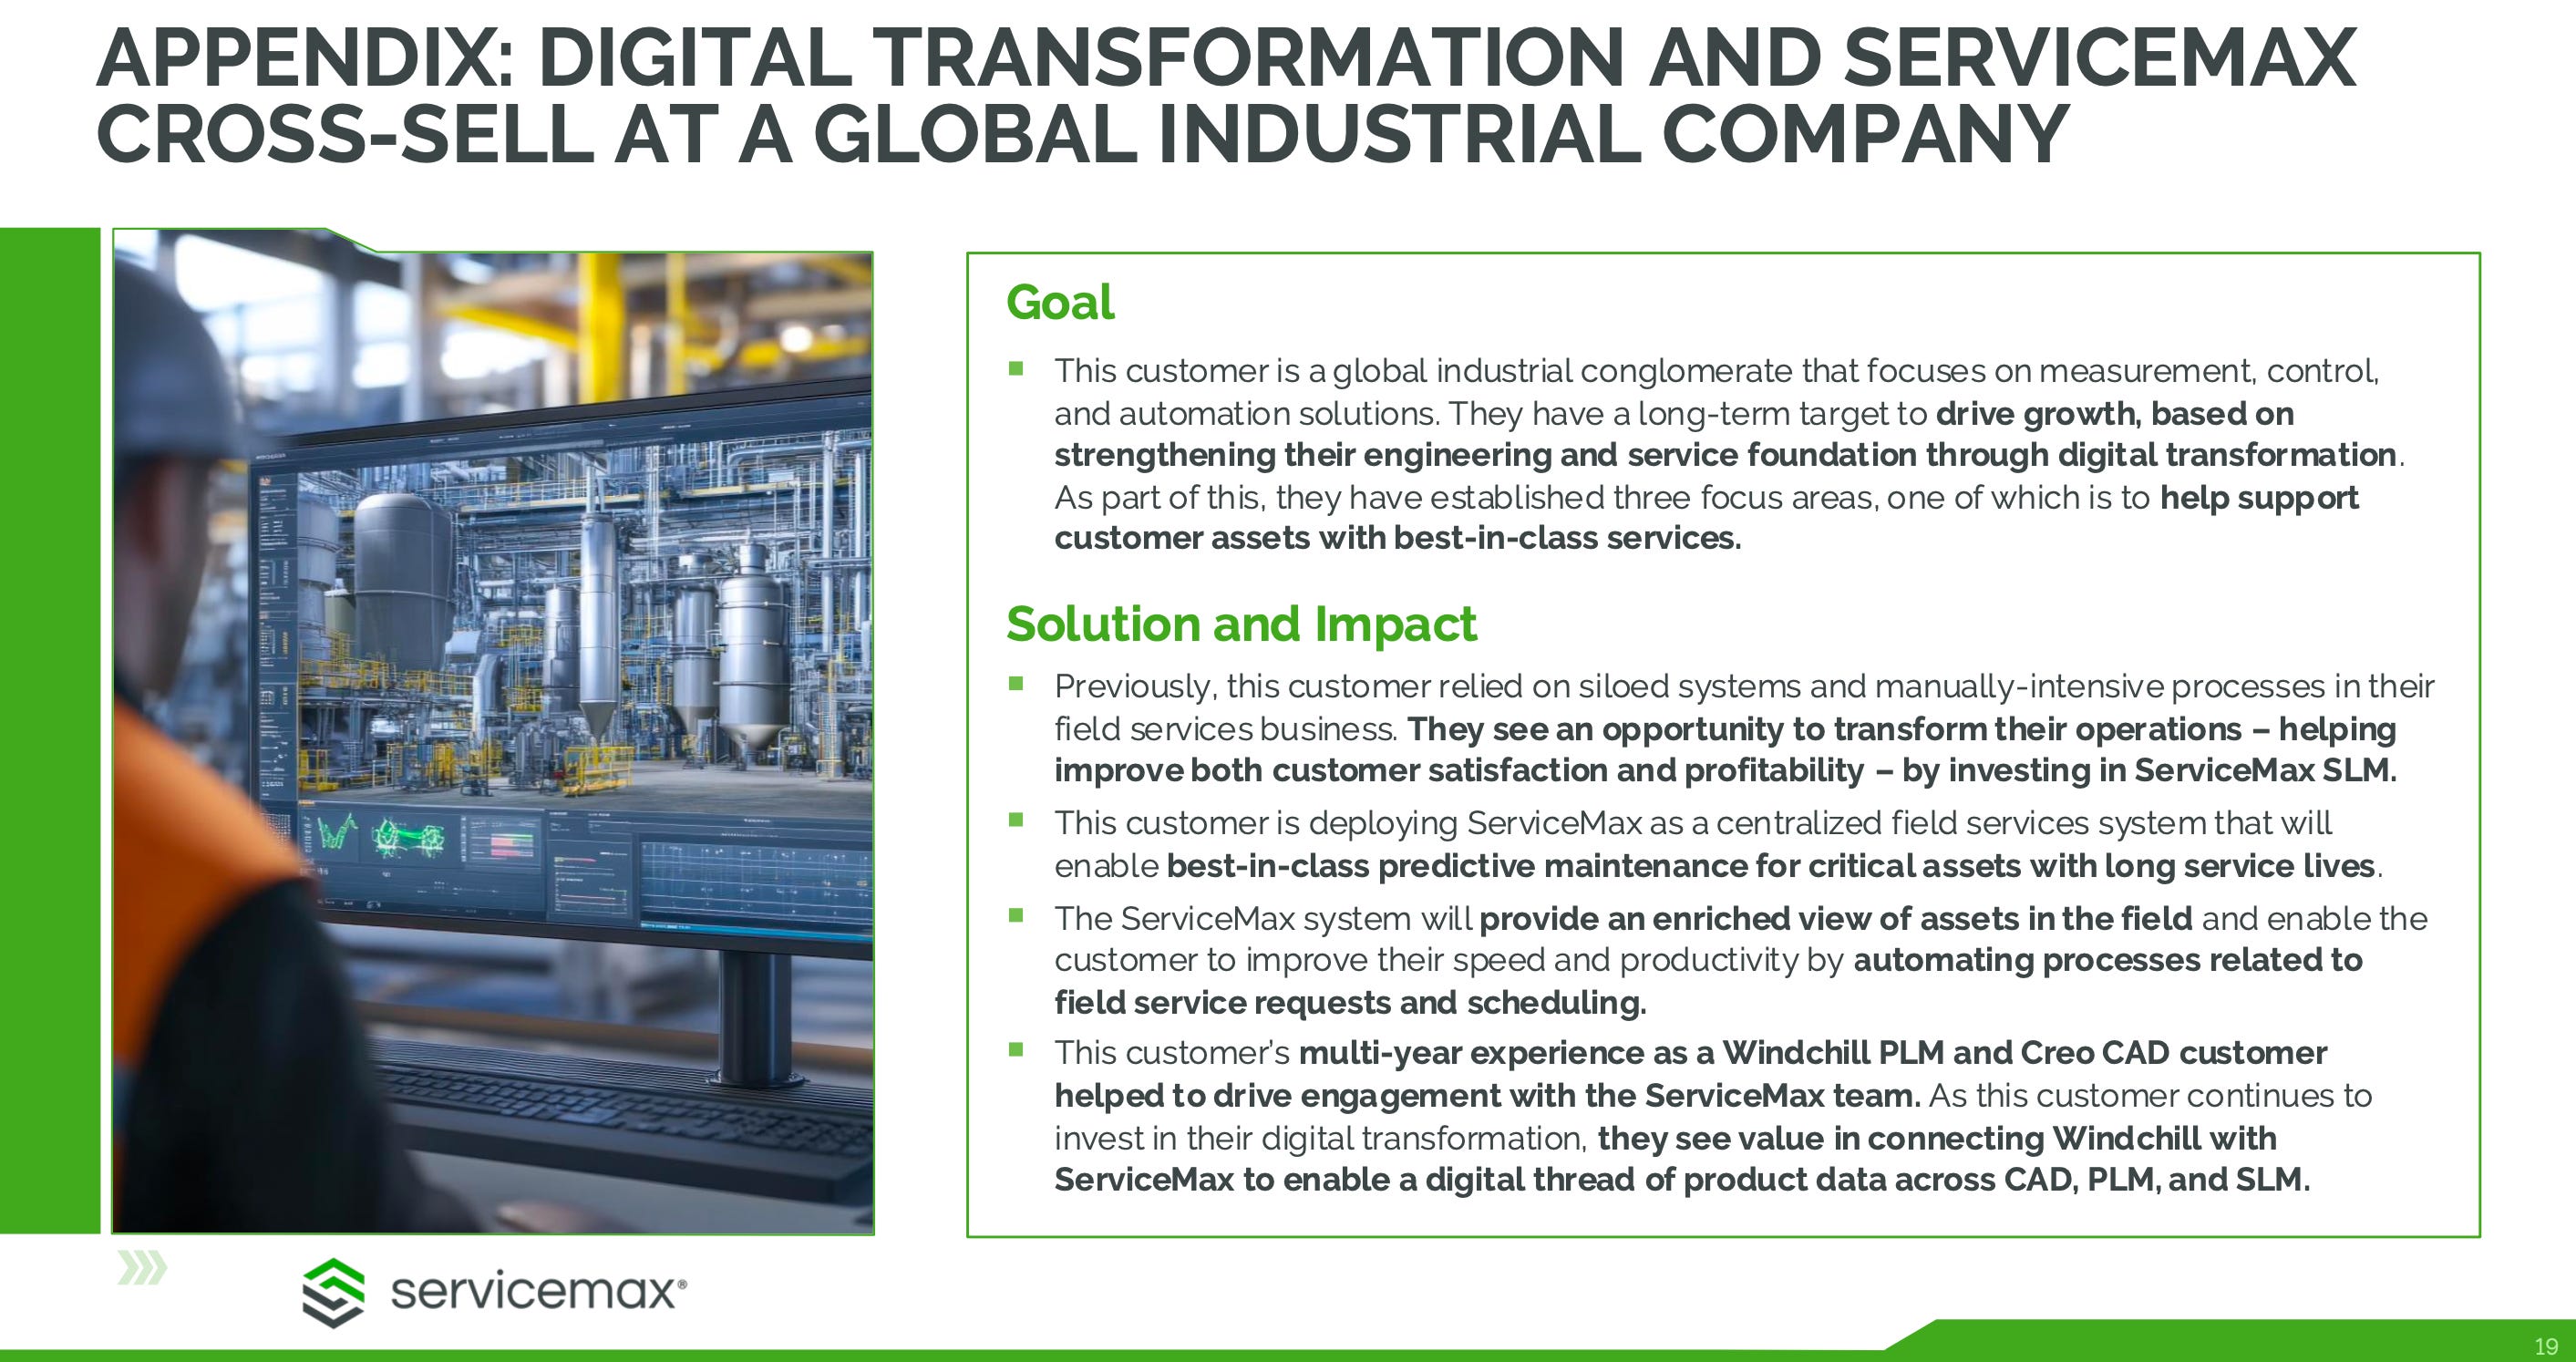
And now a brief word about the last of the products I’m going to look at - ServiceMax. Along with Onshape and Arena, ServiceMax is PTC’s third product that is delivered purely by SaaS although it sits within the Digital Thread group rather than Velocity. With ServiceMax and other solutions such as Windchill, Servigistics, Arbortext and ThingWorx PTC has the most complete vision among its peers of linking design through to parts optimisation through to predictive maintenance and field service management (FSM) - ServiceMax being the last part of the thread and the missing piece when PTC acquired it in 2022. It’s a particularly relevant solution for long-lived asset-centric product businesses where equipment stays out the field for extended periods and where service revenue can, in fact, surpass the original equipment cost over time. Industrial equipment and machinery, large medical / life science equipment, lifts/escalators, power infrastructure, aircraft engines - highly pertinent to PTC’s existing customer base and areas of focus.
FSM is technically a fragmented market. While the enterprise software majors have solutions tied into their core offerings, the closest alternative to ServiceMax in terms of asset-intensive industries is IFS:
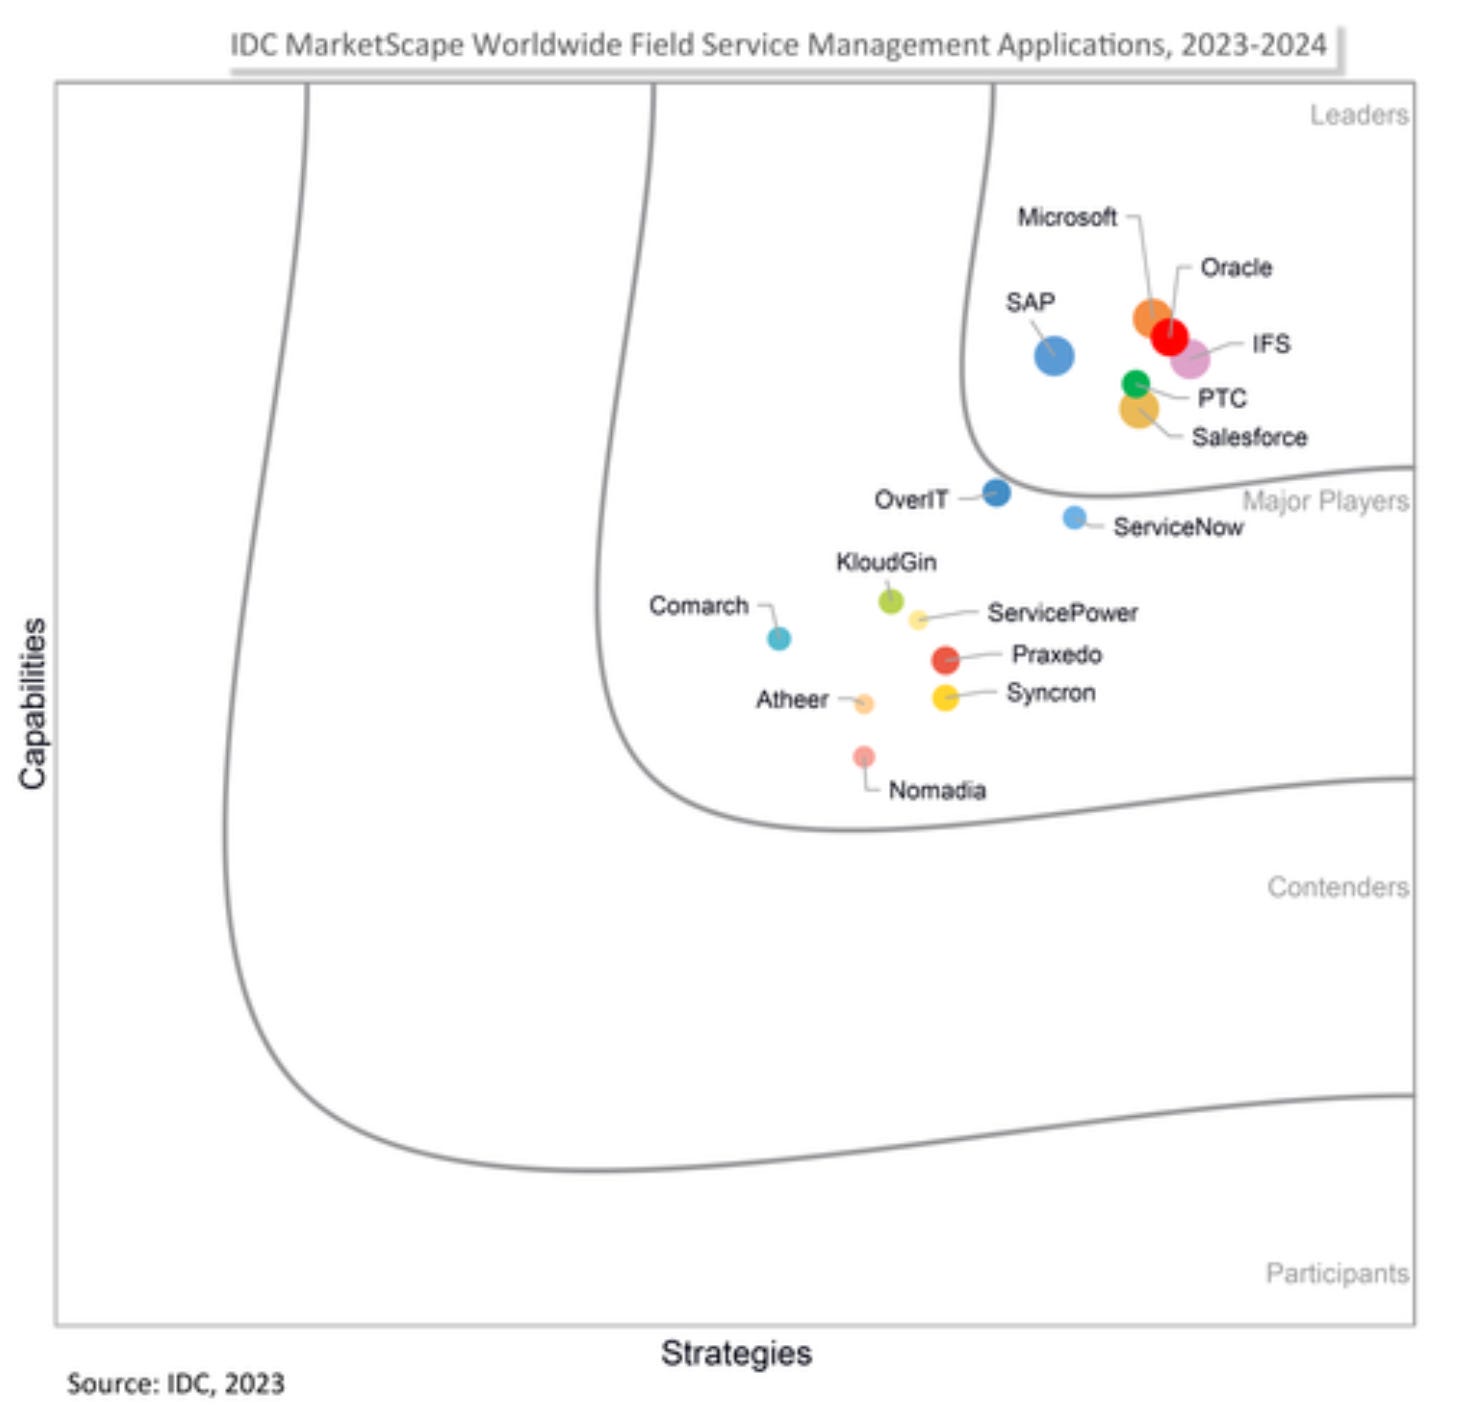
Various estimates put the FSM market in the region of $4 to $6bn and growing low-double digits.3 When ServiceMax joined PTC it was doing ~$160m in ARR and growing mid-teens.
At the basic level ServiceMax covers work order management, scheduling, dispatch, and mobile field service (including smartphone/tablet apps for field engineers). But it becomes significantly more powerful when integrated into Windchill, Servigistics, Arbotext and other services - technicians always have the latest engineering and configuration data and up-to-date service documentation embedded directly into workflows, all alongside optimised parts availability. It all provides for a tighter feedback loop between design and field engineering.
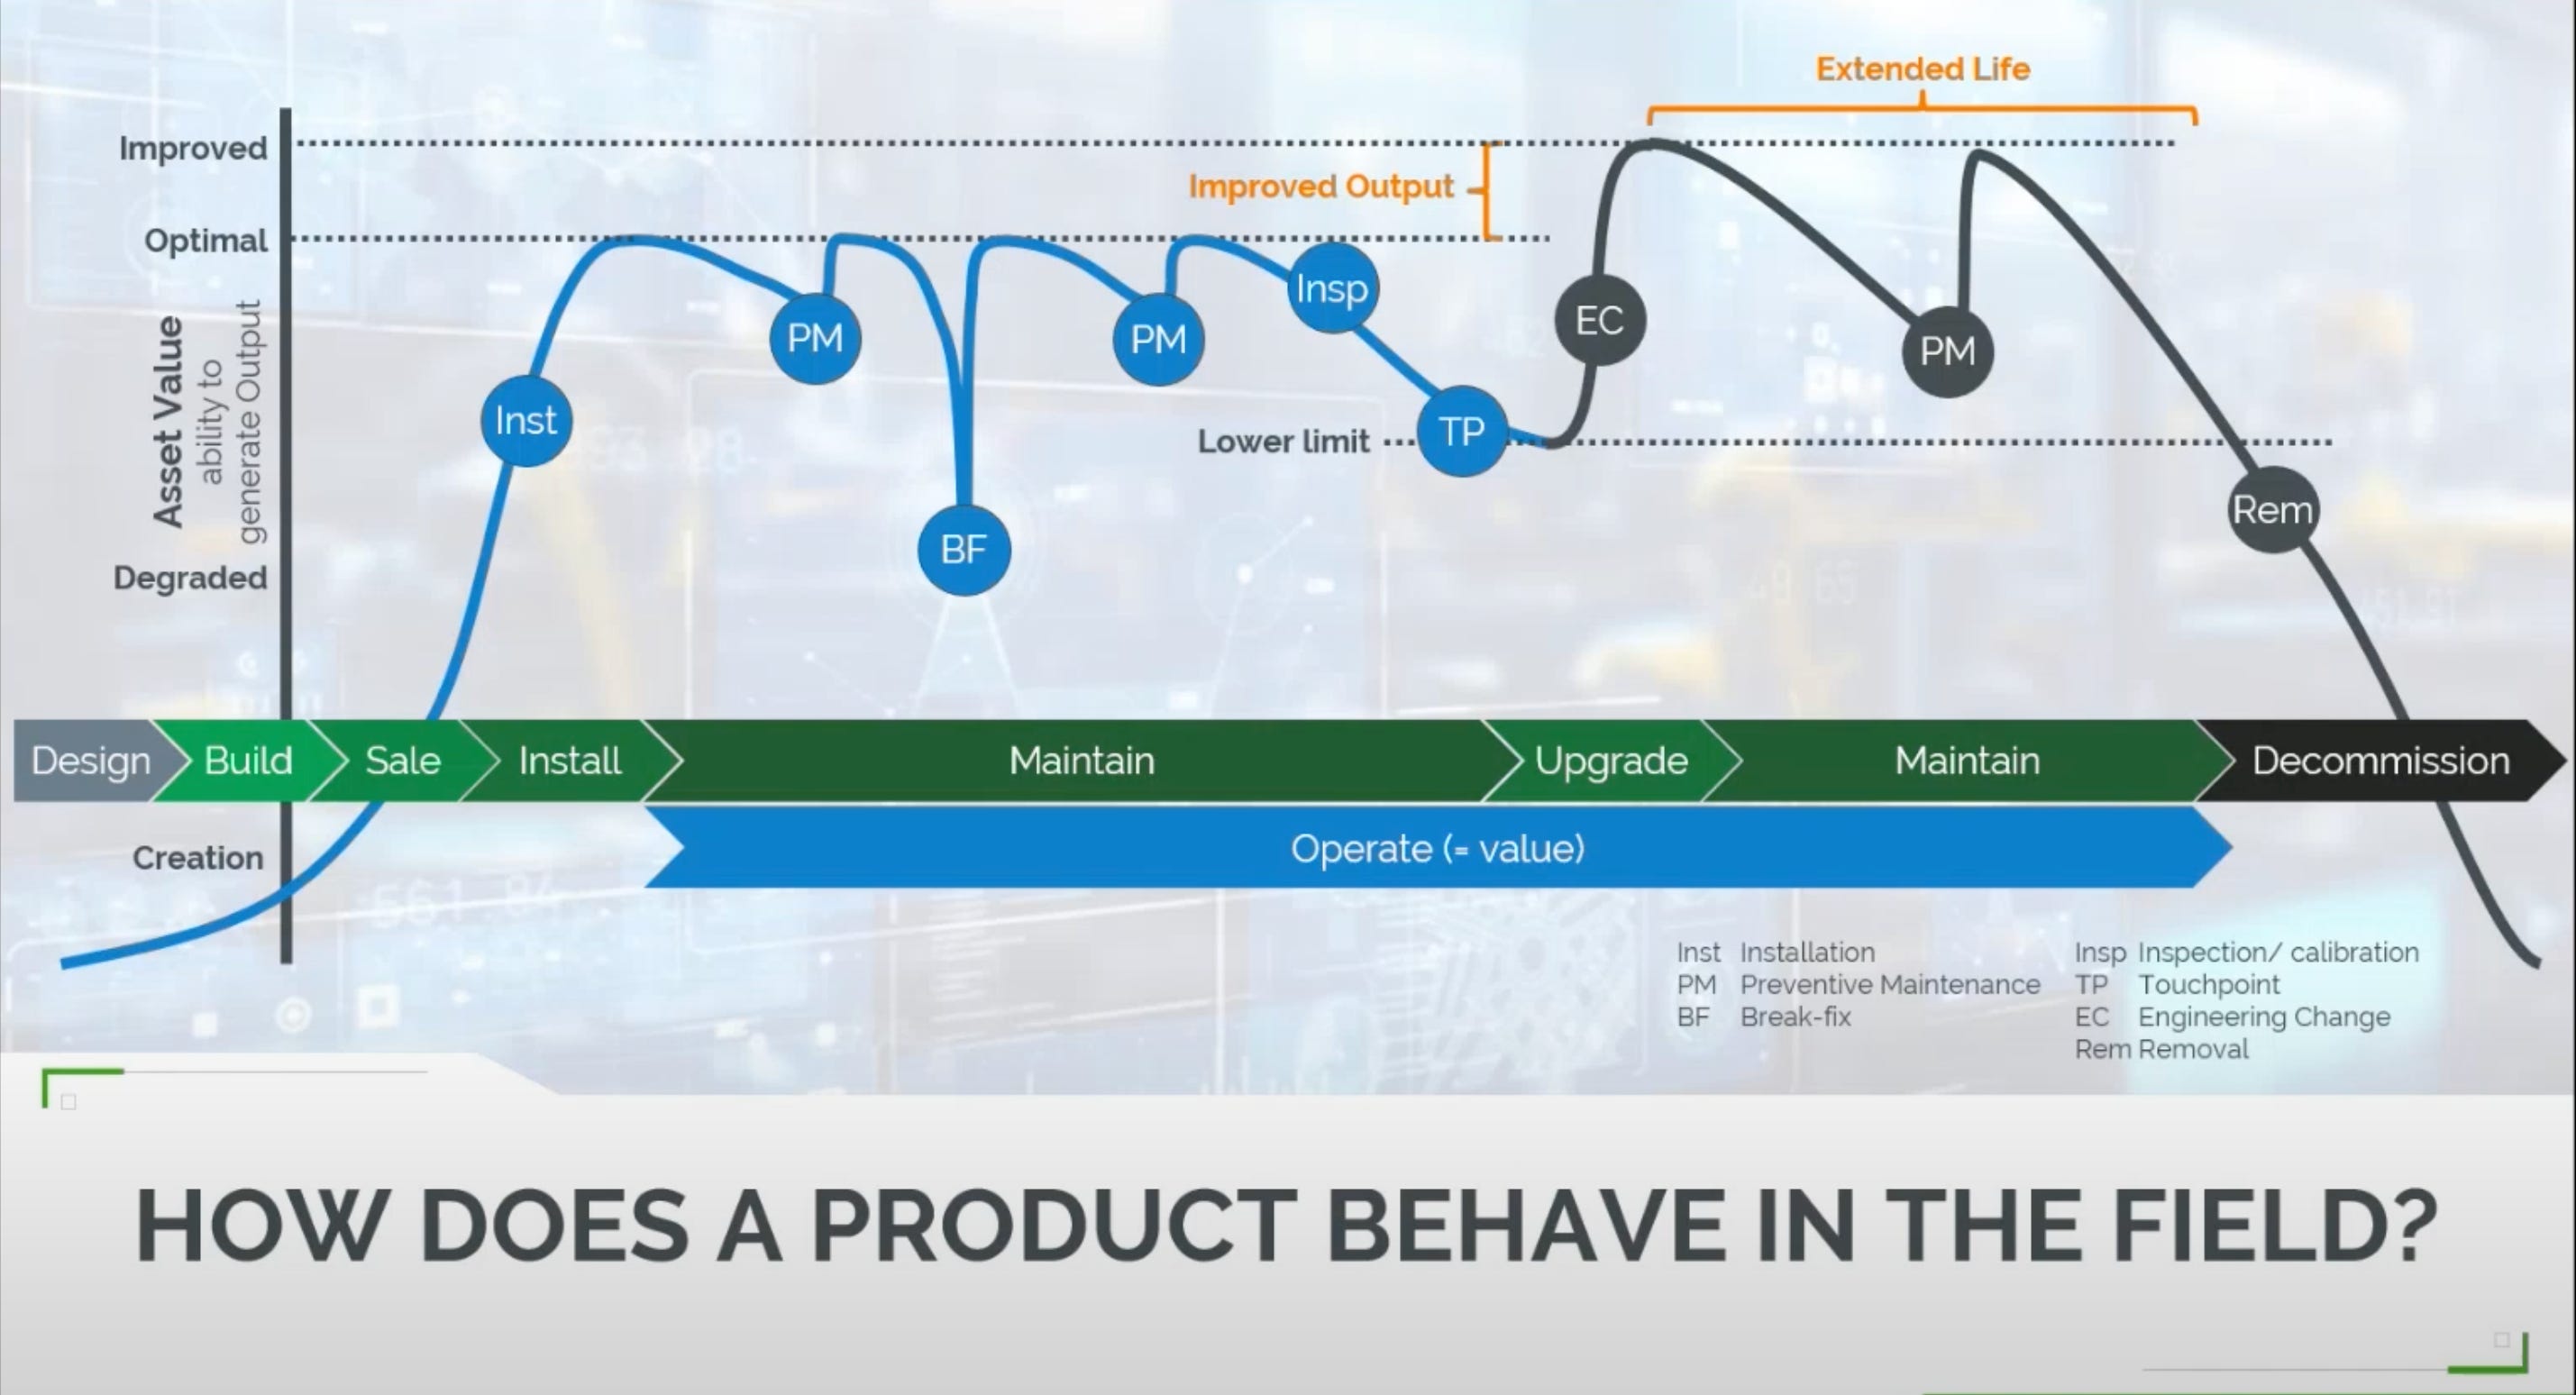
Given that PTC’s principal competitors are largely absent from this space, PTC has a pretty unique advantage in selling to asset-centric customers now - including cross-sell to existing Windchill and Creo users:
AI Strategy
Going back some years, PTC was already adding incremental AI functionality to its lineup - including generative design. Creo has offered generative design since 2019, following the acquisition of Frustum.
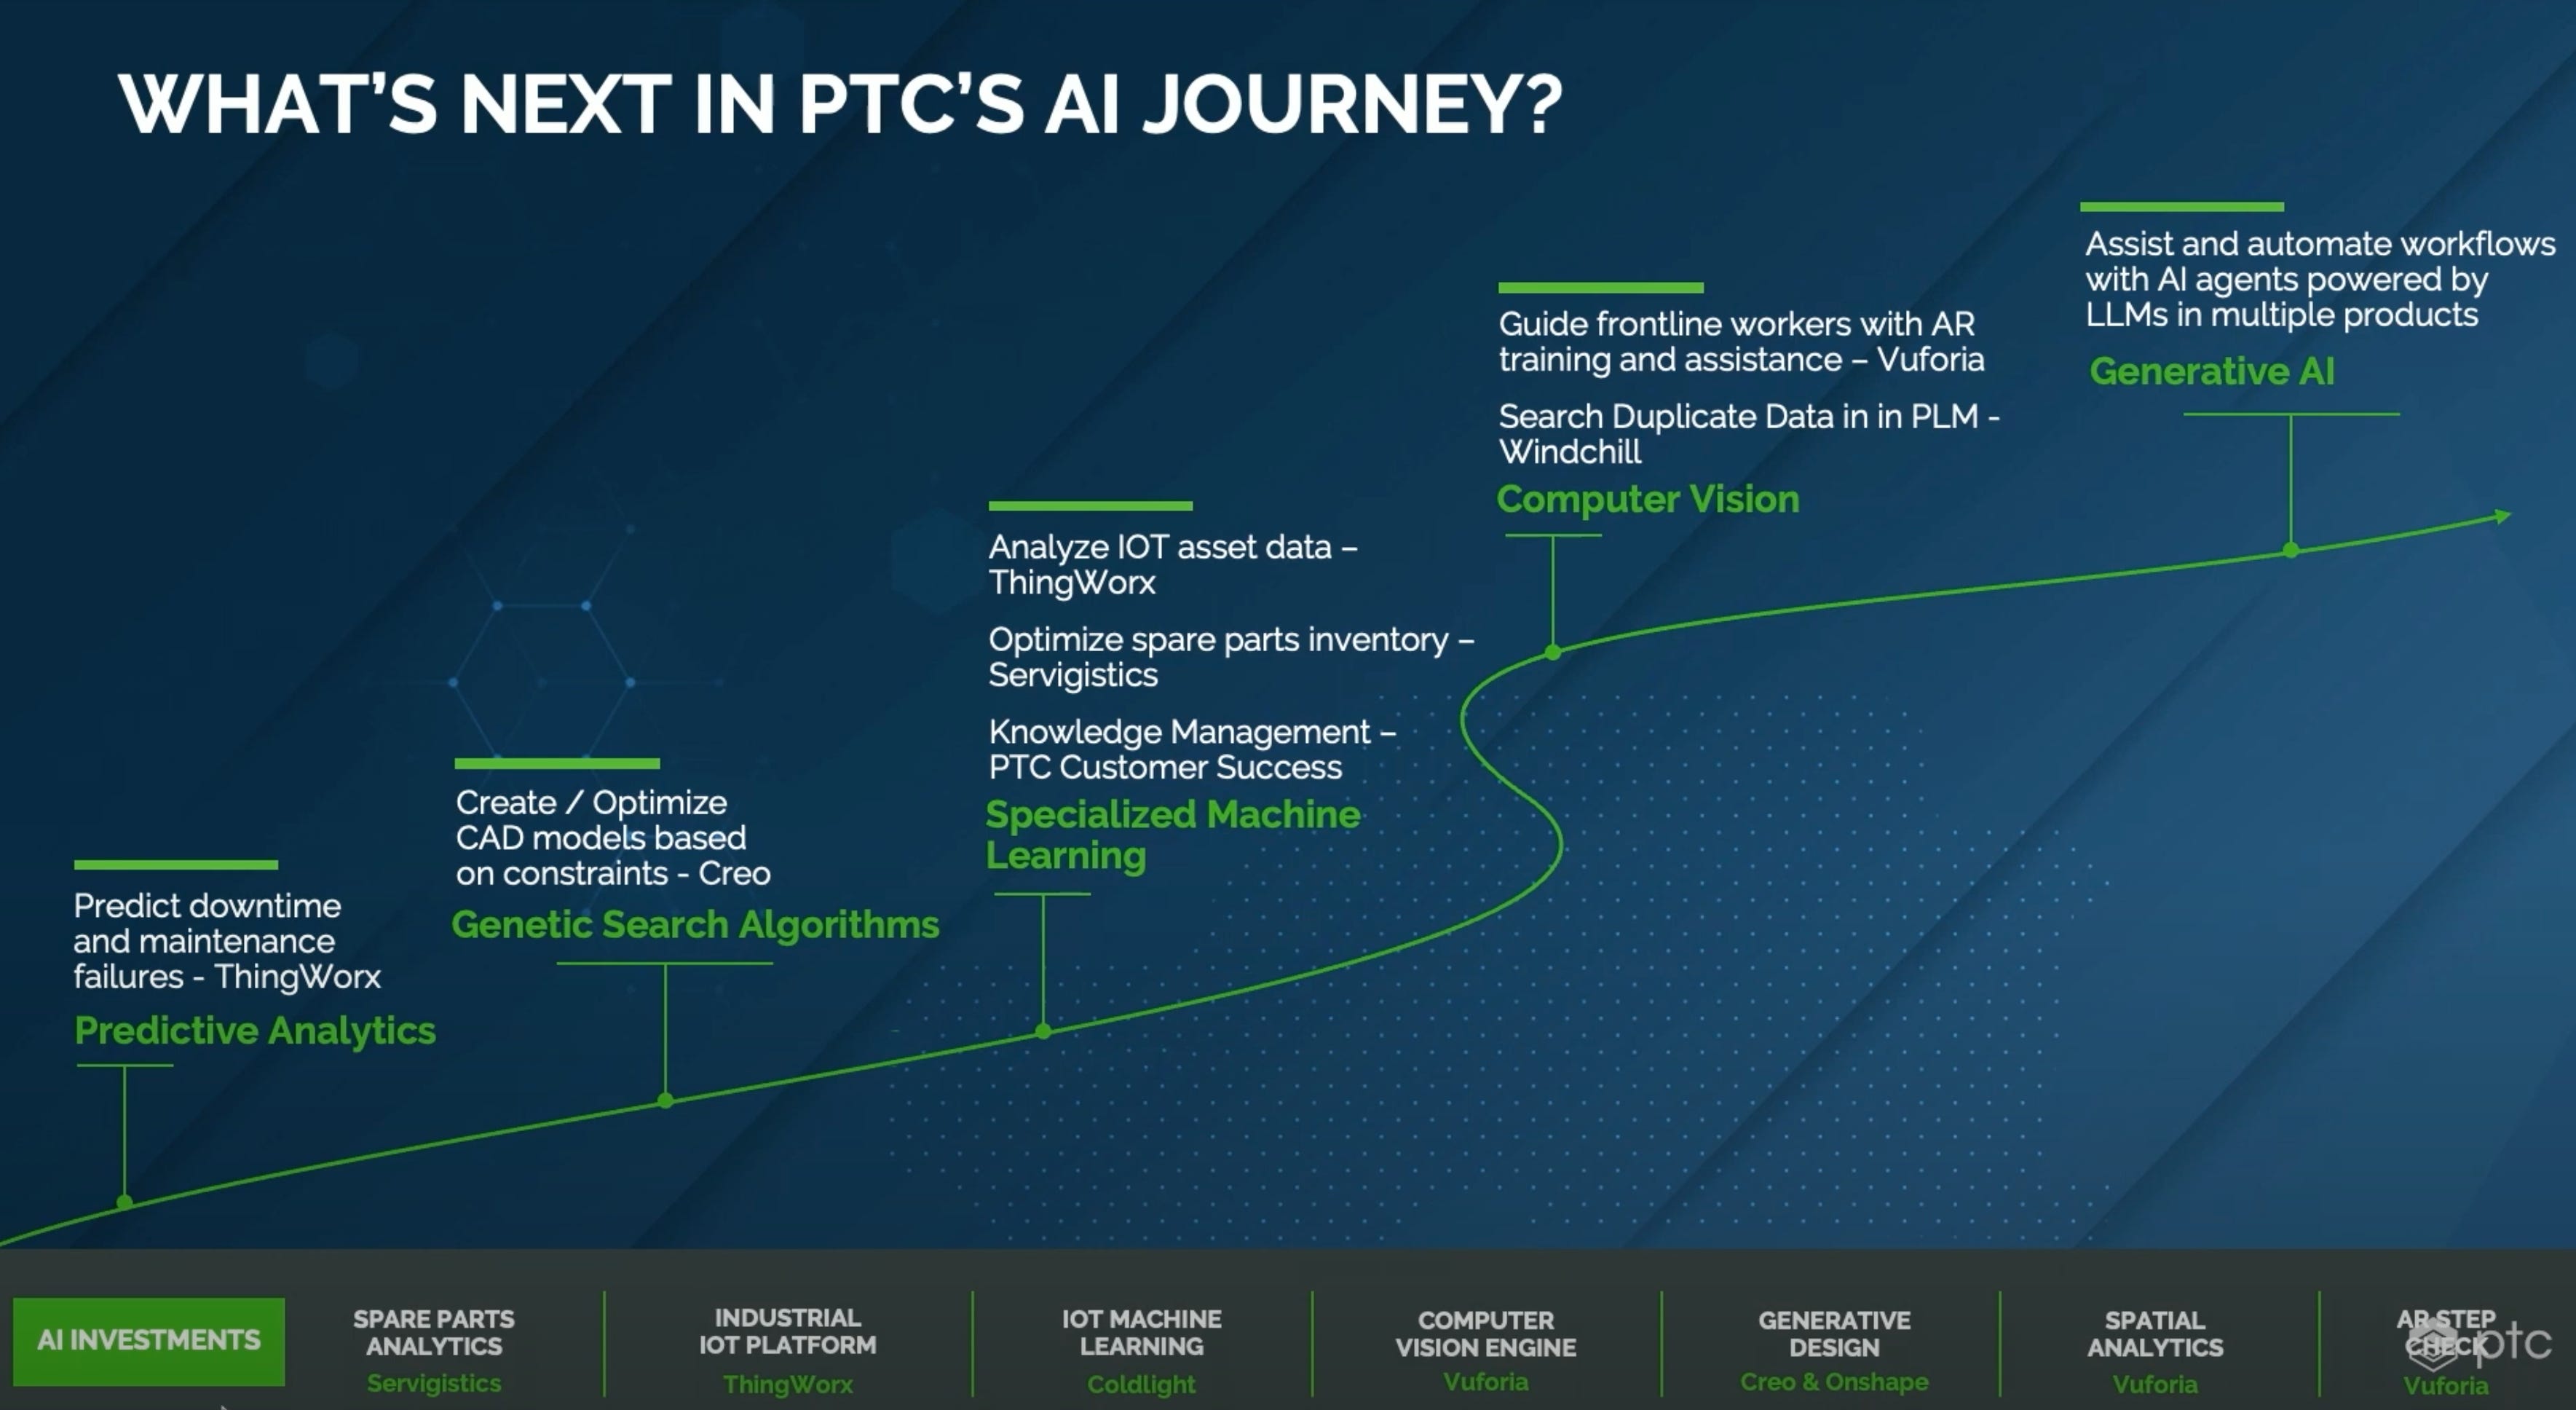
In the immediate aftermath of the LLM Cambrian Explosion, PTC’s approach was to take its time to suss things out before saying anything concrete about AI strategy. But more recently, new features have started to emerge either in beta or general availability:
Windchill Document Vault Agent: enables engineers to extract relevant product-related information from documents stored in Windchill
ServiceMax AI: field service assistant to answer questions about a specific job or asset, automate manual documentation and schedule tasks
Codebeamer Copilot: an intelligent assistant, helping engineers create new requirement specifications and test cases using specific data and business context
Onshape AI Advisor: an assistant for navigating Onshapes CAD/PDM feature set
Leo AI for Onshape: AI copilot for technical questions and design decisions
Arena AI Assistant: AI assistant to answer user questions and deliver step-by-step guidance
PTC hasn’t said all that much directly to investors about the AI strategy (at the time of writing) except that there’s a strong roadmap coming for 2026. And as noted in Part I, the rollout of AI features is also starting to come up as part of the pricing discussion. What is exciting about PTC’s position is the centricity of Windchill to the structured data foundation of customer products and their associated lifecycles - it’s a key layer at which to introduce data-driven features (i.e. ‘AI’). But while PTC haven’t said too much to investors yet, they do seem to be talking to customers about it - and it’s clear there’s a lot of thought and effort going into it. In particular I recommend this (unlisted) customer session with Ayora Berry VP and AI Product Leader from a few months ago:
This more recent short video with Product EVP Kevin Wrenn is also helpful. I’ll provide some of the key points as to what is currently known about the strategy and the sorts of things we might expect to see announced in the year ahead.
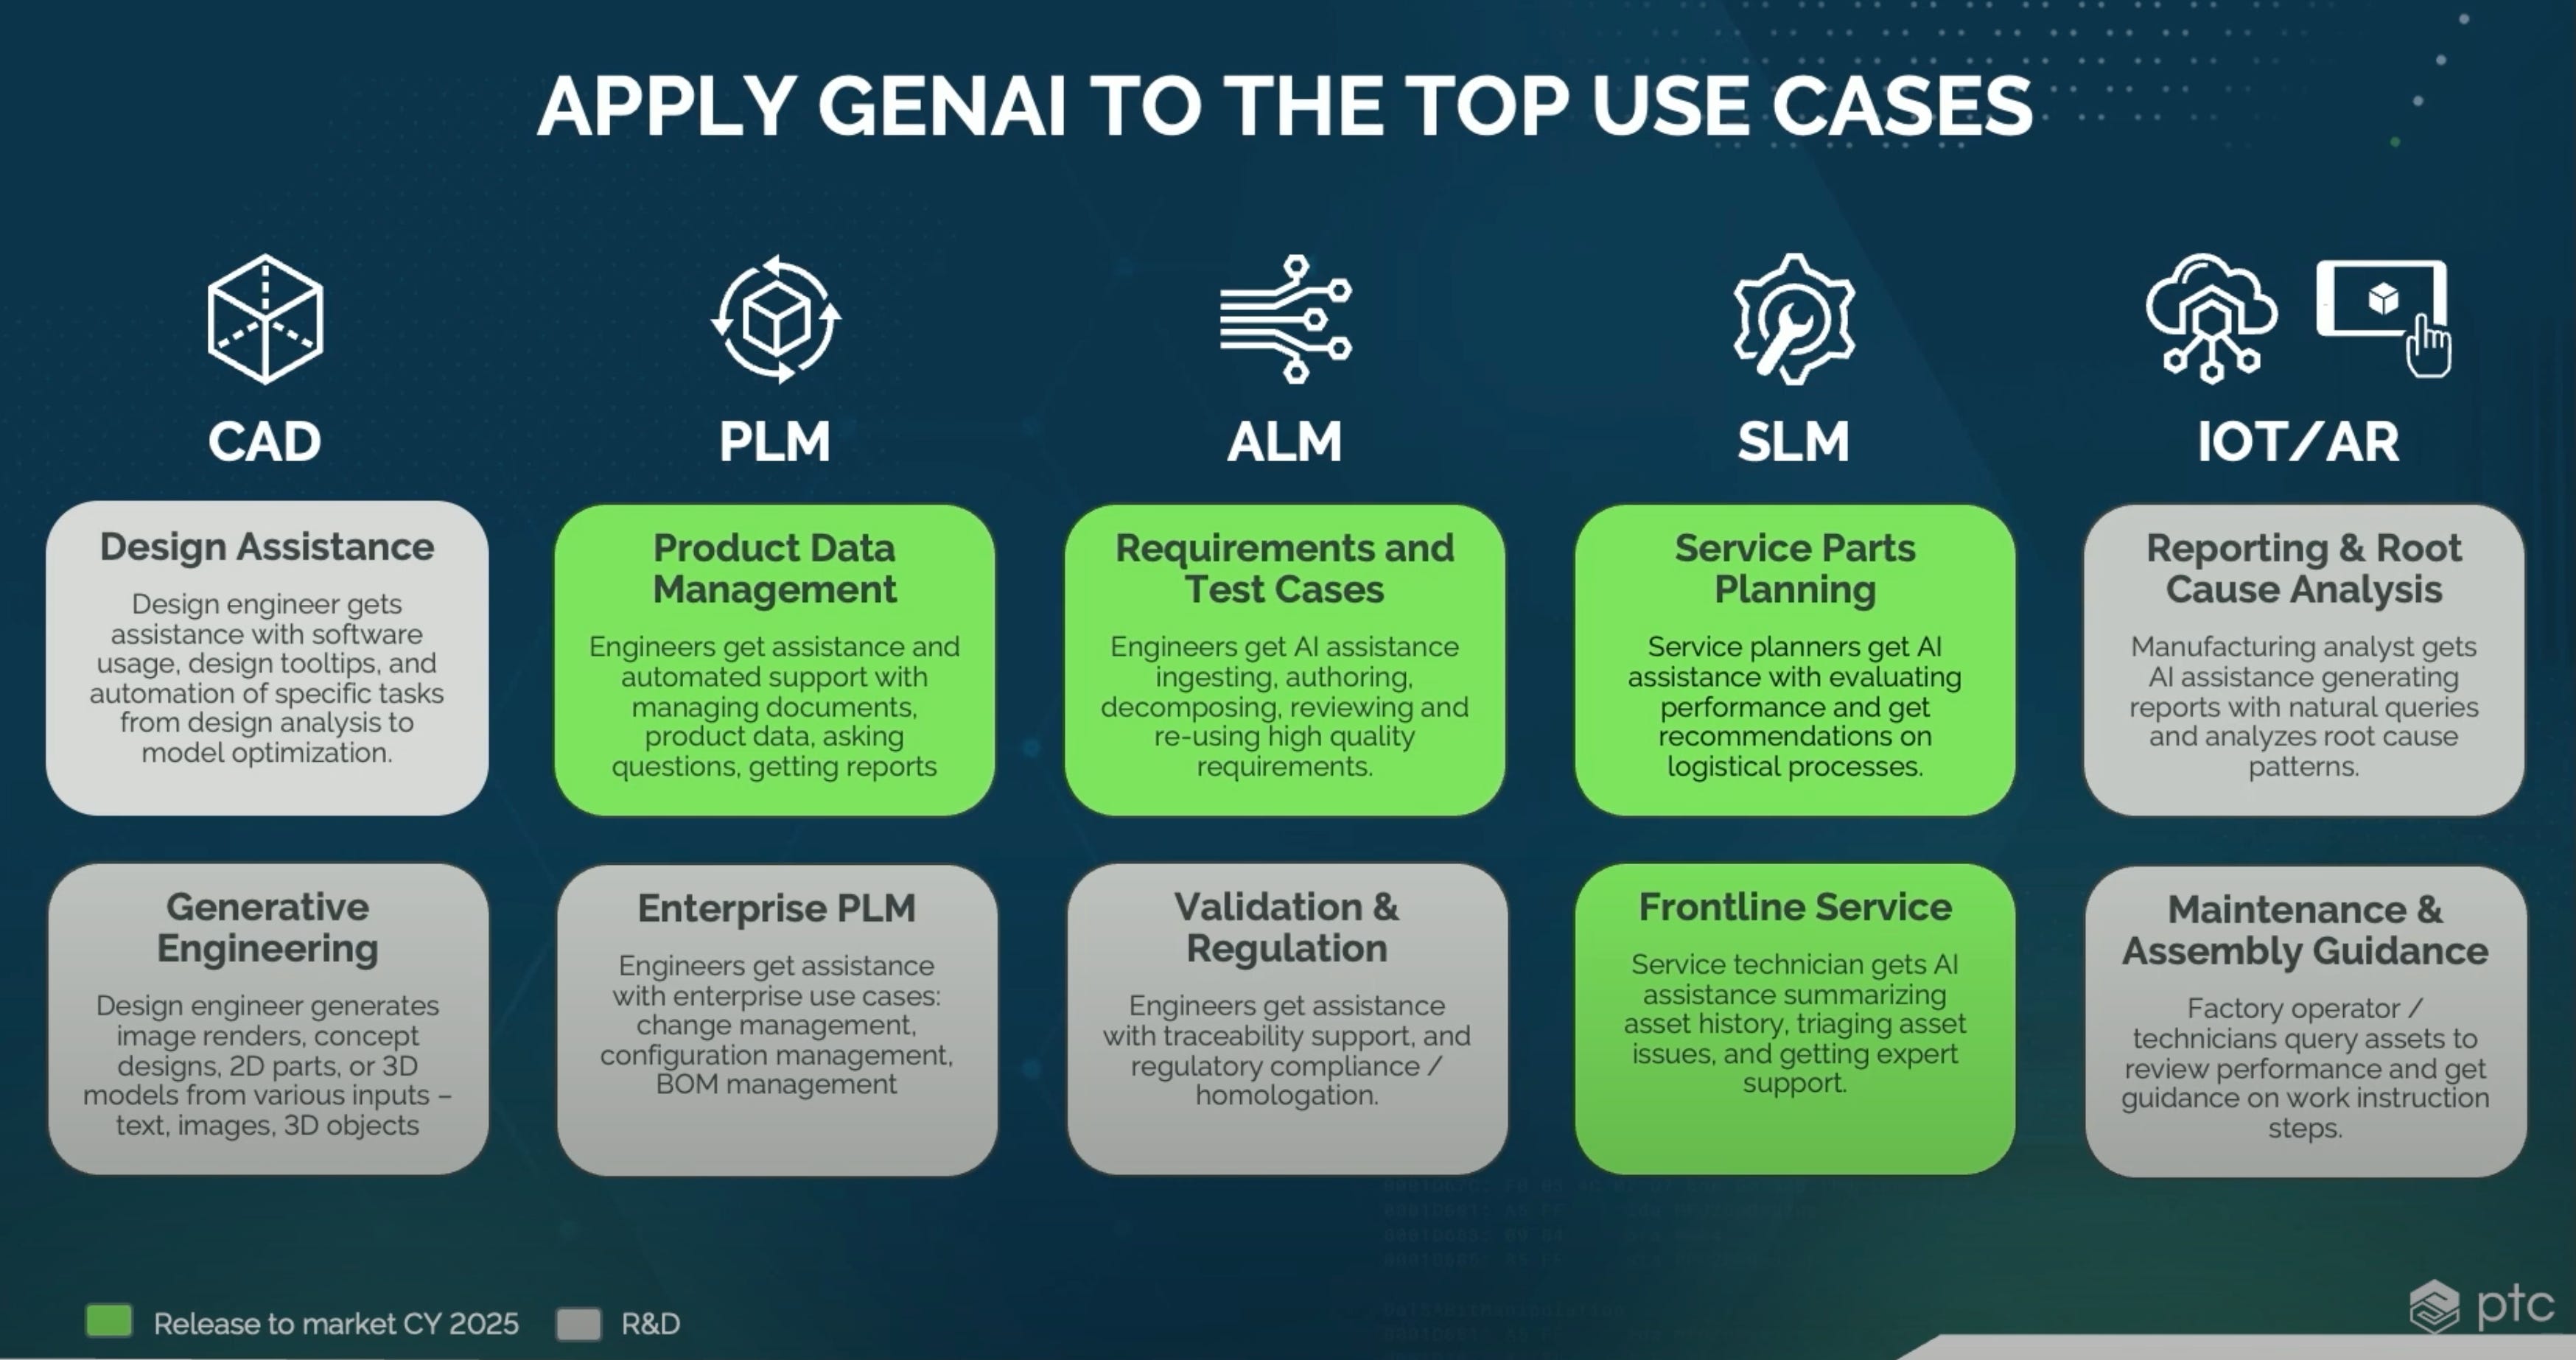
Importantly, PTC is thinking intelligently about use cases rather than trying to glue on AI features as an afterthought. In all cases to improve and speed up existing workflows and/or lower COGS - at least to begin with PTC believes that engineers don’t want to leave established systems. But the idea is to build confidence, with the ability to farm out an increasing number of task to agents over time.
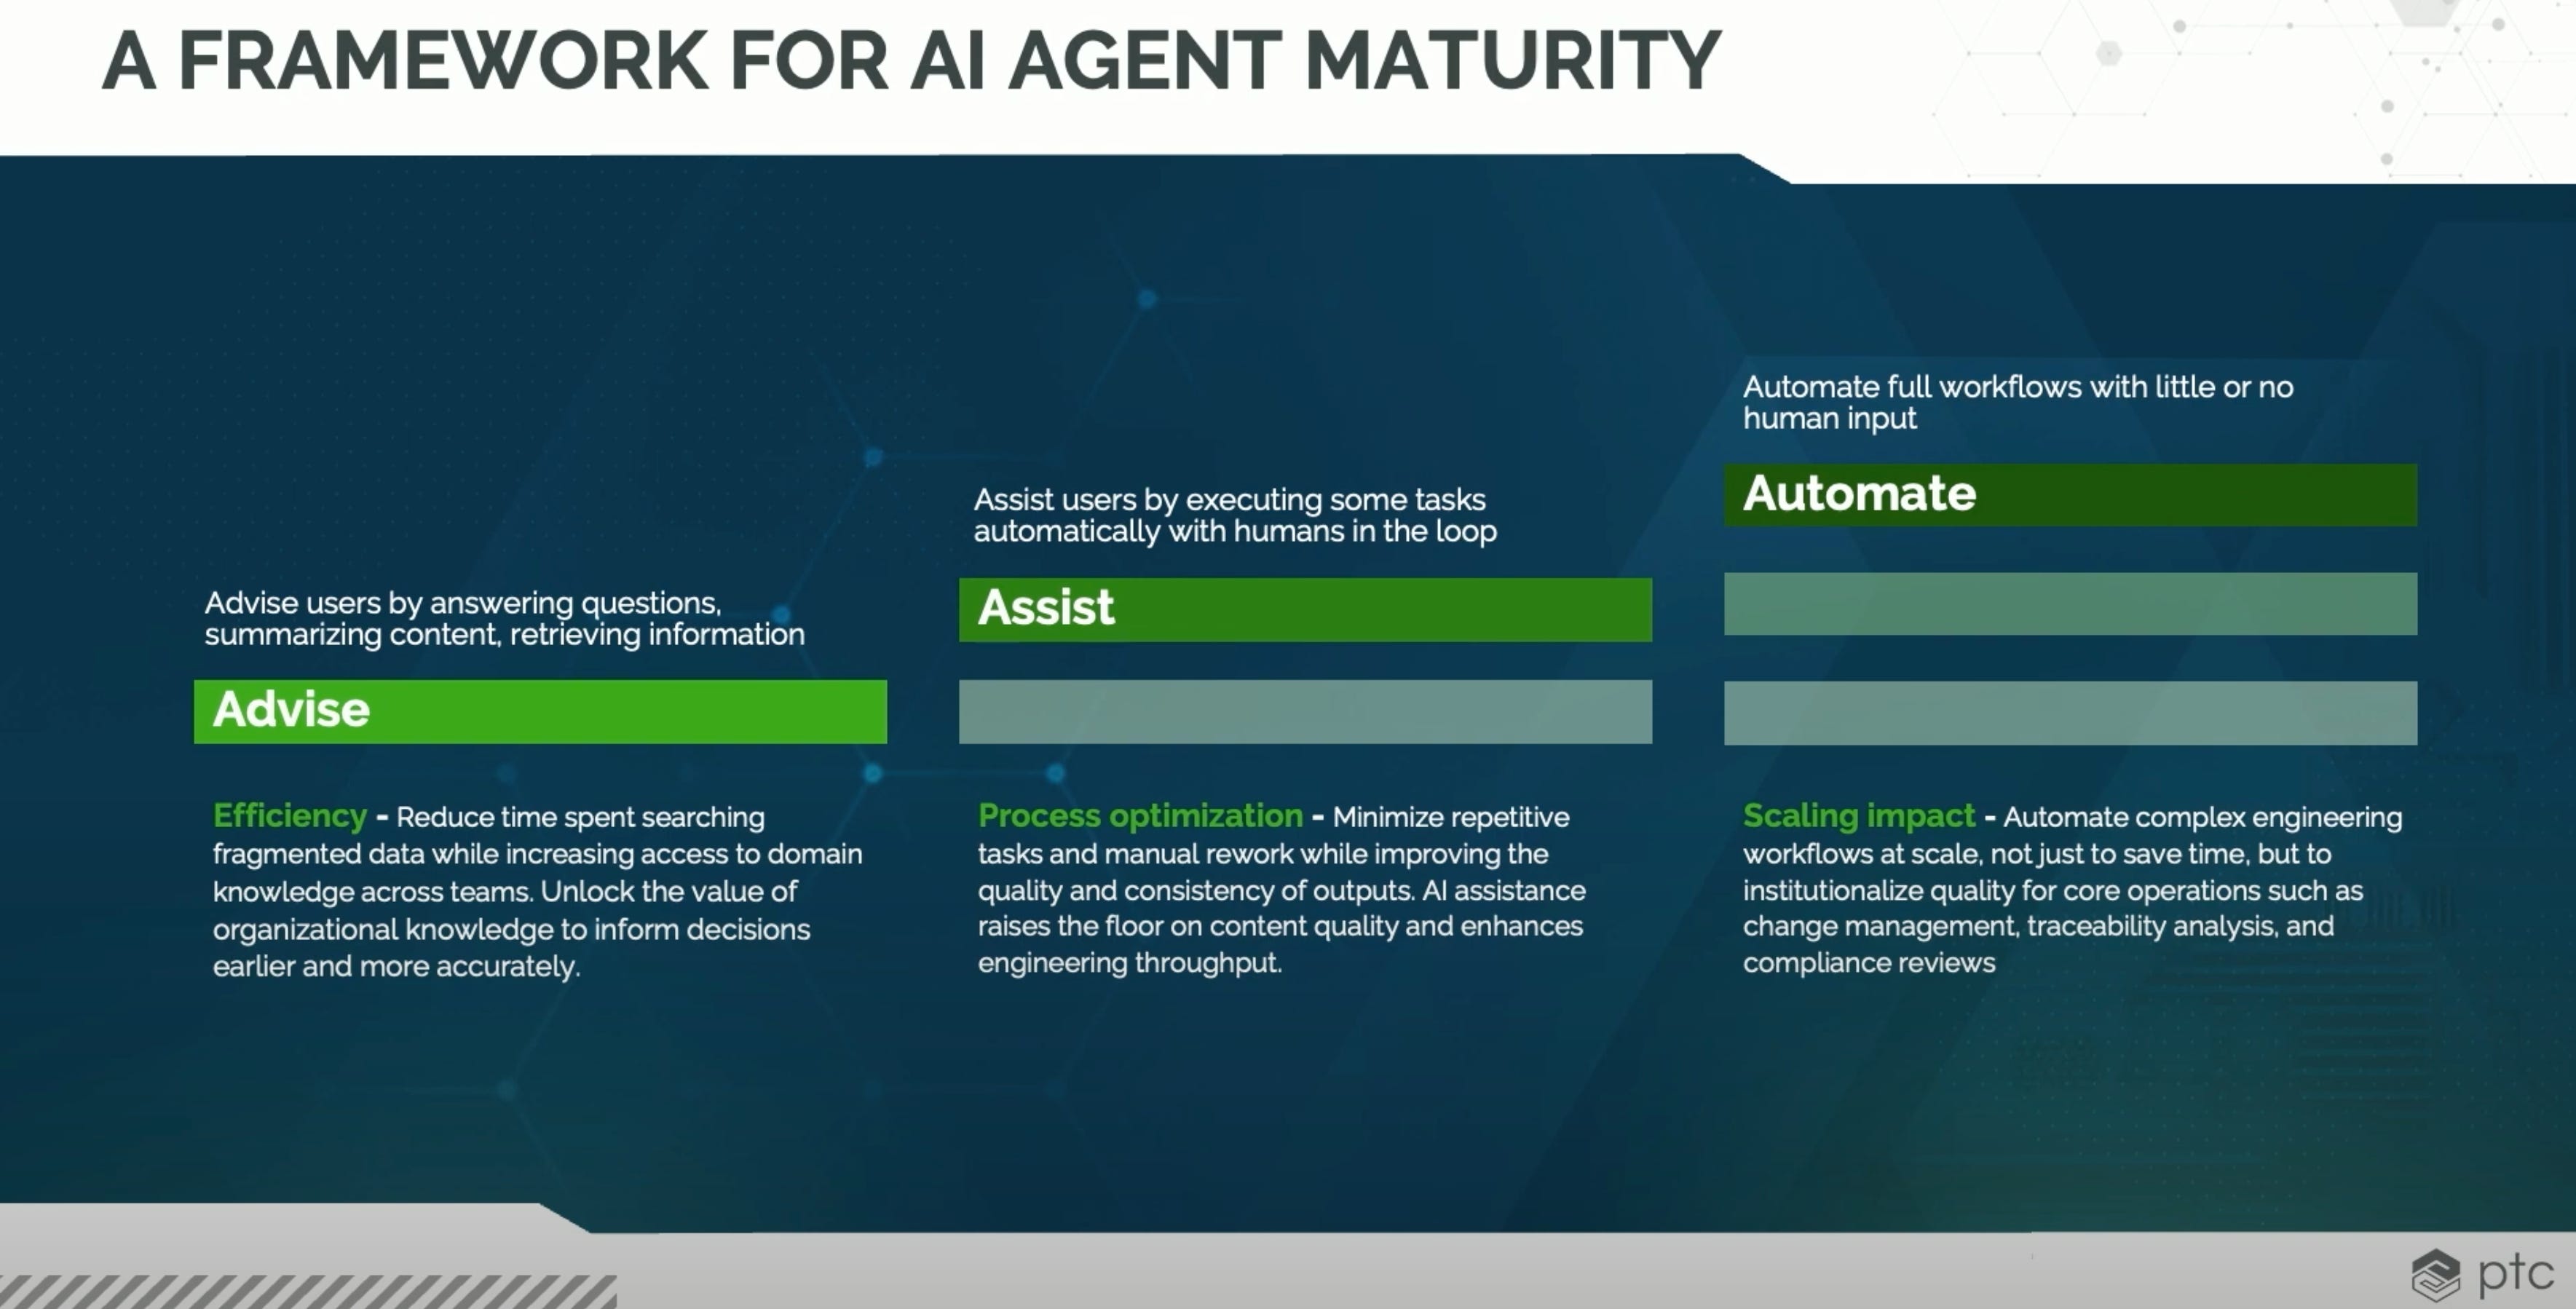
The philosophy runs to three layers: Advise, Assist and Automate. You can see these in action with the existing releases, particularly on the advise and assist side.
Coming to automation, the vision is to have numerous agents working on particular functions…
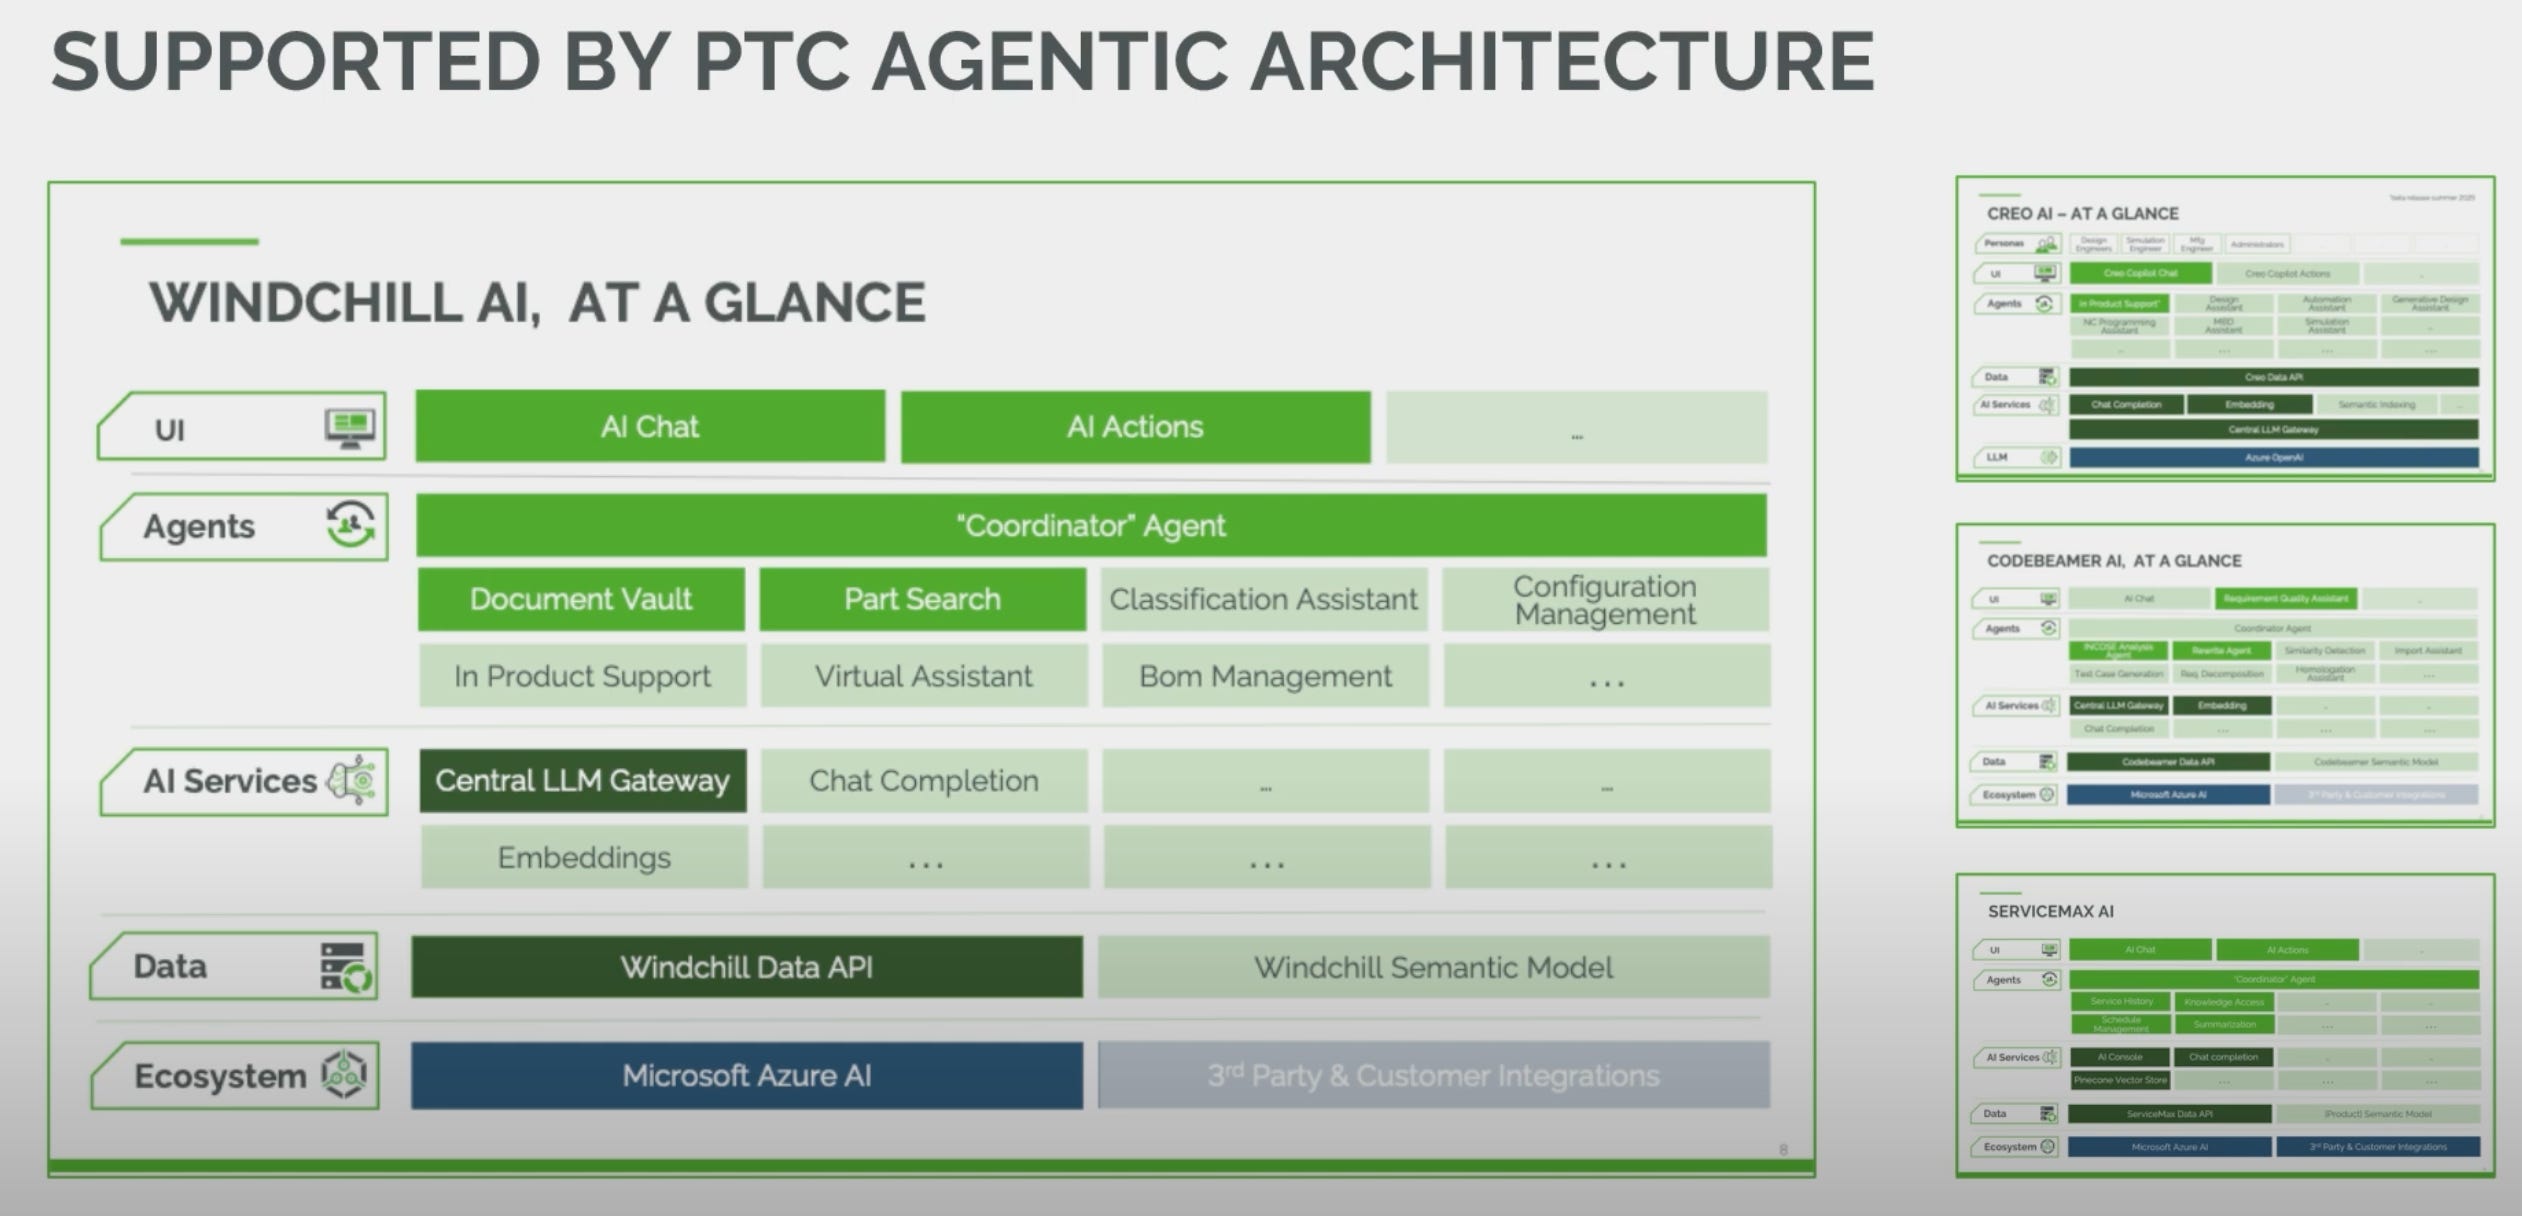
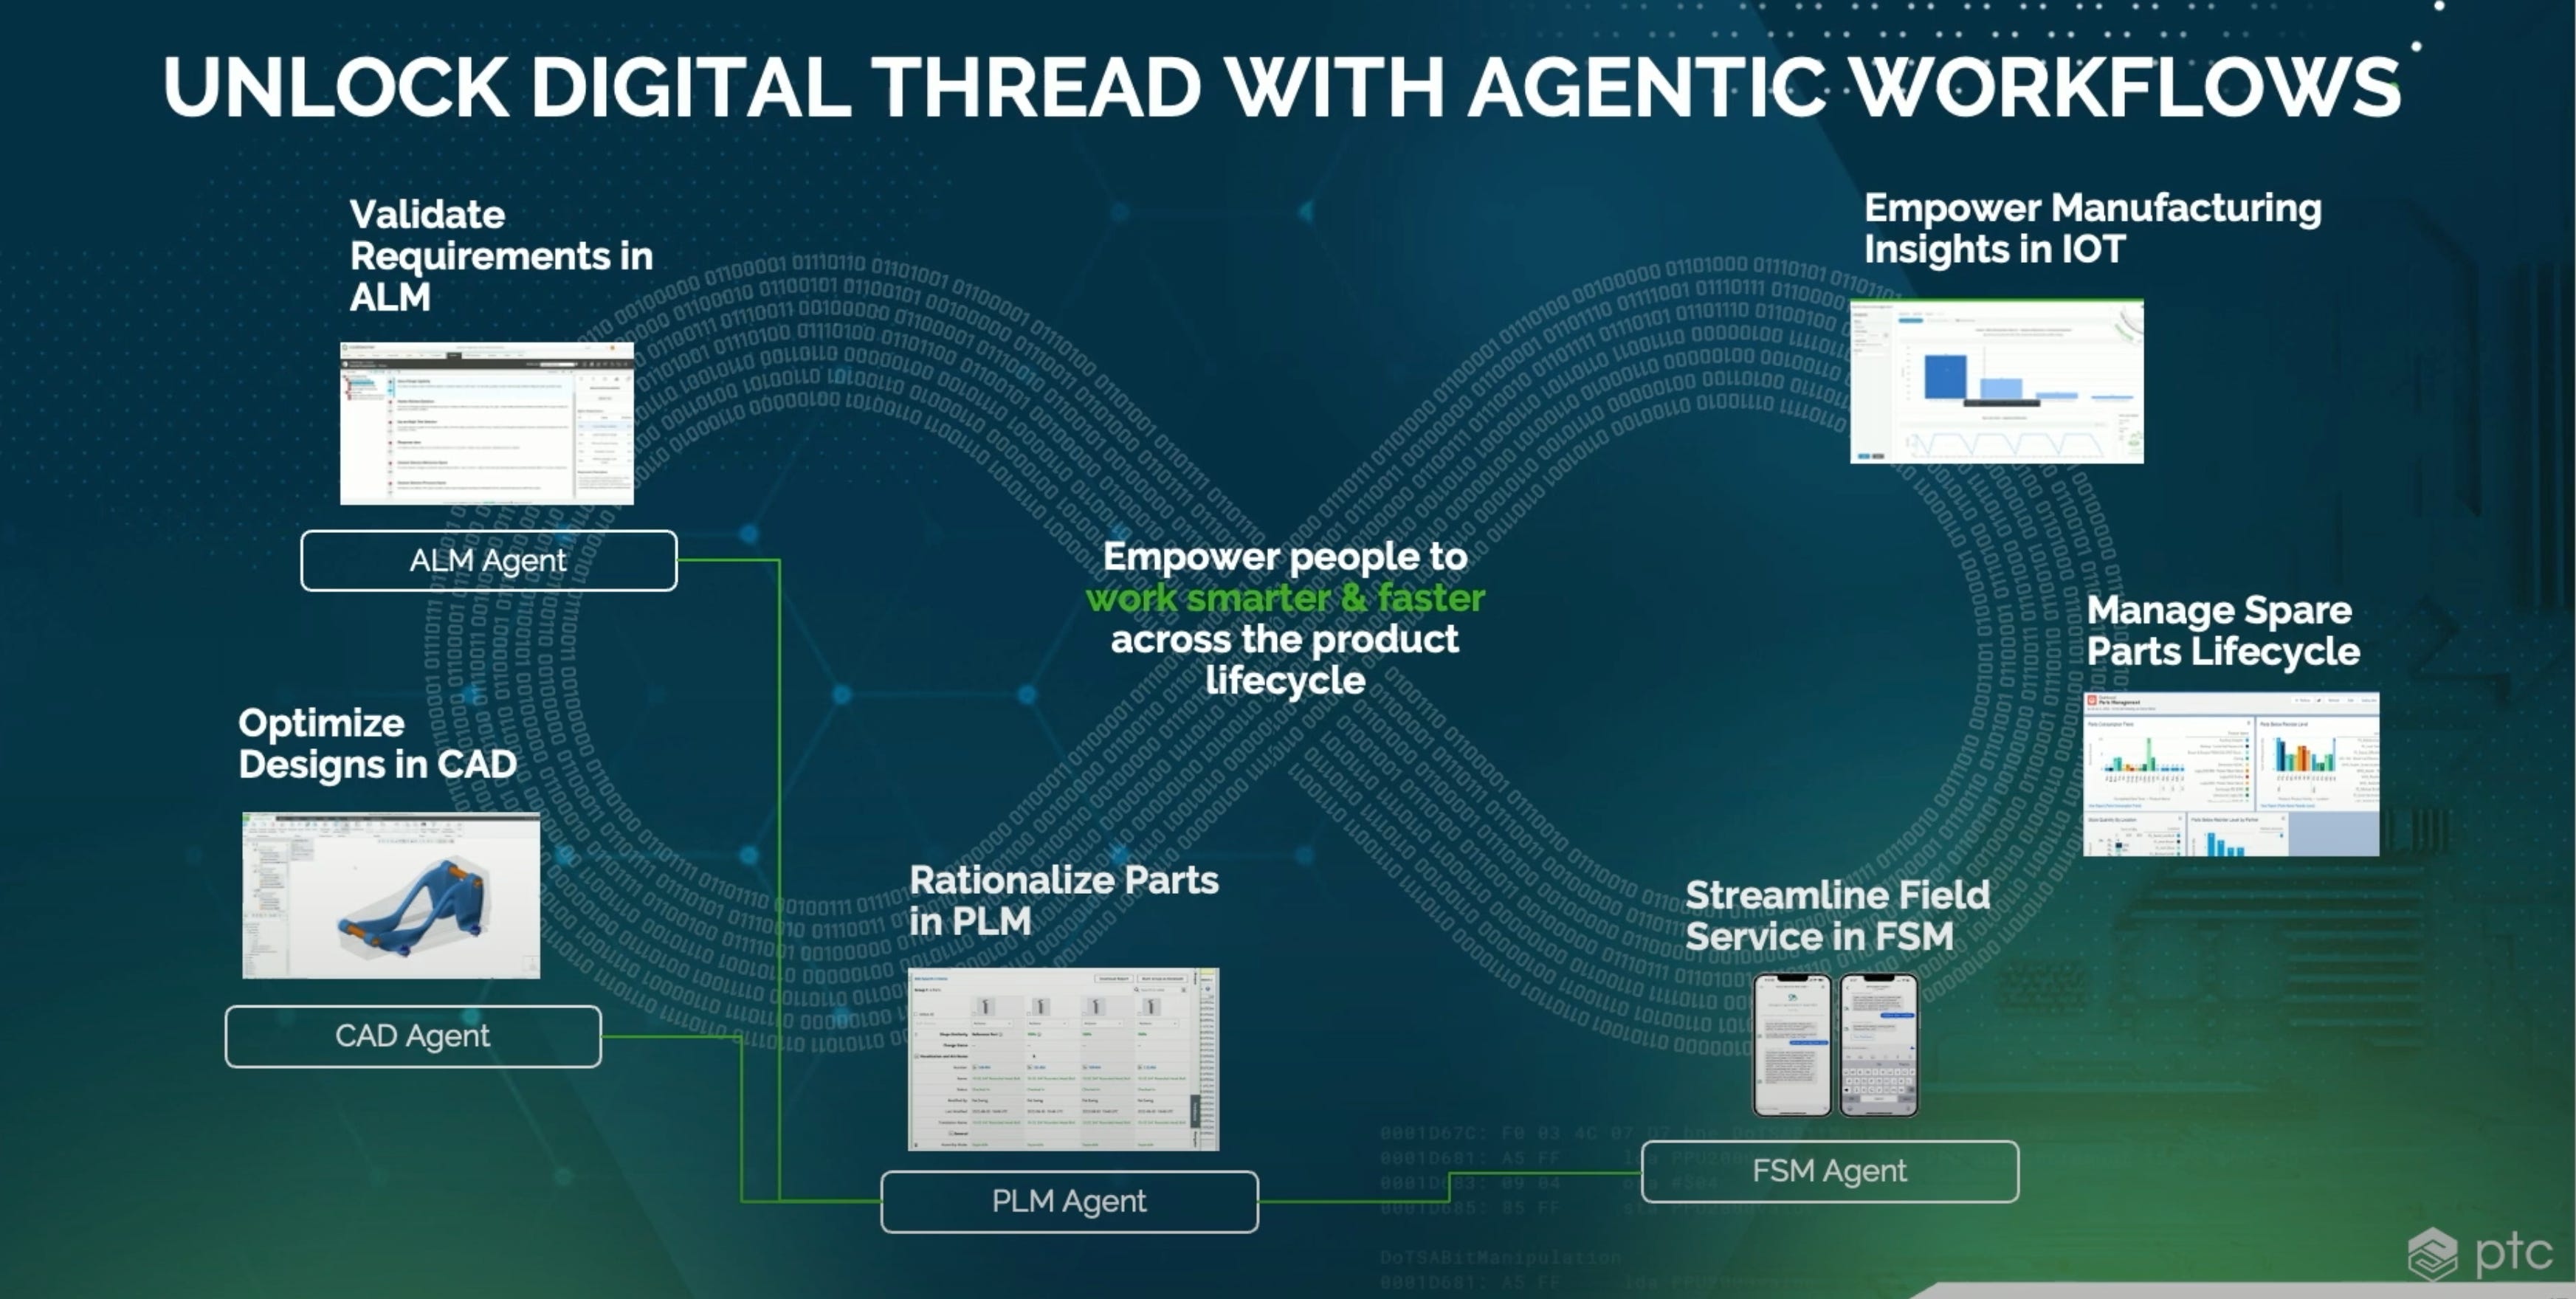
…and then to co-ordinate the agent architecture across the suite, so that agents can work with each other. Kevin Wrenn gives two examples in his video: 1) if you’re looking for duplicate parts in Windchill, the Windchill agent can co-ordinate with the Codebeamer agent to find duplicate requirements so these can all be rationalised at the same time; or 2) if an engineer is looking at parts in Windchill, the Windchill agent can co-ordinate with the ServiceMax agent to find their repair history to inform the next generation design. In this vision, the agents themselves become part of the fabric of the digital thread:
Regarding pricing, PTC is telling customers to expect add-on pricing for AI features currently, with charges applied beyond a specified token budget. However, a consumption model is envisaged within 3-5 years.
Financial Considerations
As noted before, I acknowledge that NFTBC readers have their own approaches and methodologies when it comes to valuation - so NFTBC is fairly high level from a financials and valuation perspective. Want I want to do here is highlight some of the more important considerations I think you should know about and some of those feeding into my own thinking on valuation.
ASC 606 / ARR / Free Cash Flow
If you’re new to PTC, one of the most important things to familiarise yourself with is the relevance of accounting standard ASC 606 to PTC’s financials. It’s worth getting to grips with because PTC’s revenue and EPS numbers can lead you astray, as can shorthand metrics like P/E. Until relatively recently PTC didn’t even provide a non-GAAP EPS number, but then started issuing them to stop investors from being led even further astray by largely made-up consensus EPS numbers.
ASC 606 determines how PTC must account for on-premise software subscription revenue, which in the grand scheme of things is relatively unusual - most software is generally either delivered via license/support on-premise or via cloud subscription off-premise. While some other companies also have some on-premise subscription revenue, at PTC it forms the bulk of the business currently - there aren’t too many close equivalents.
CFO Kristian Talvitie has discussed the effects of ASC 606 on numerous occasions, as well as the relevant metrics for understanding the company - the 2021 Investor Day is a good place to start:
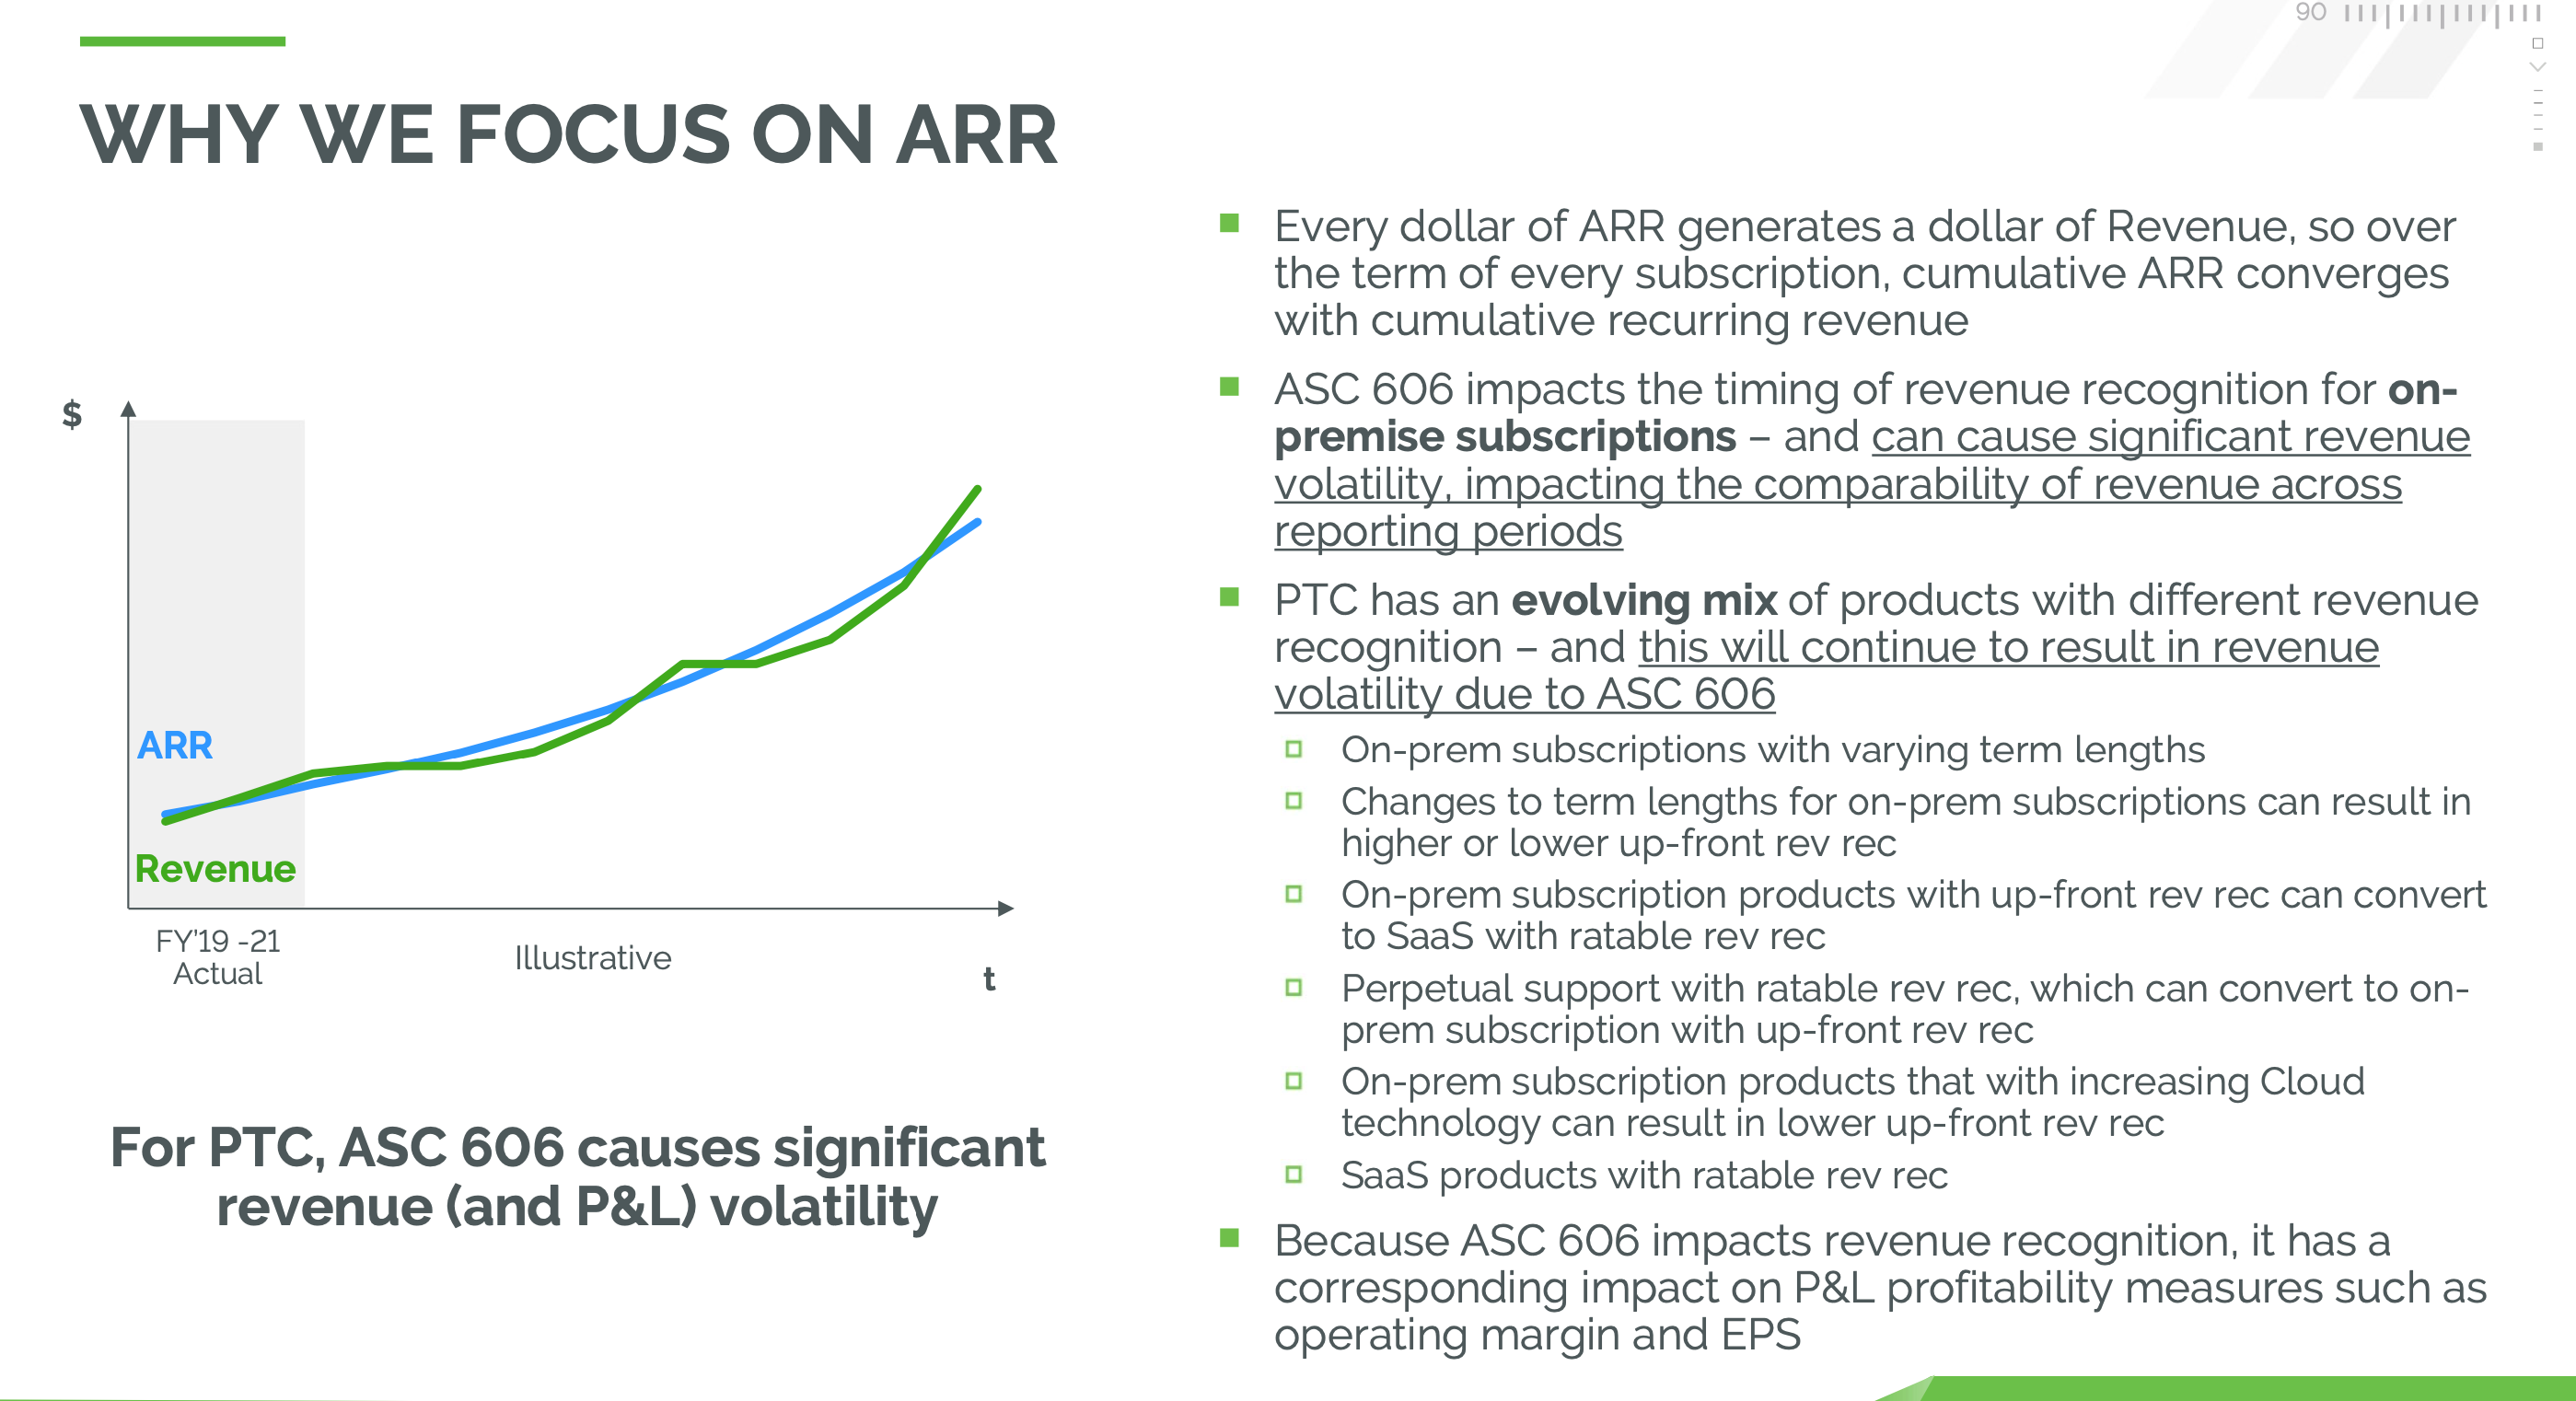
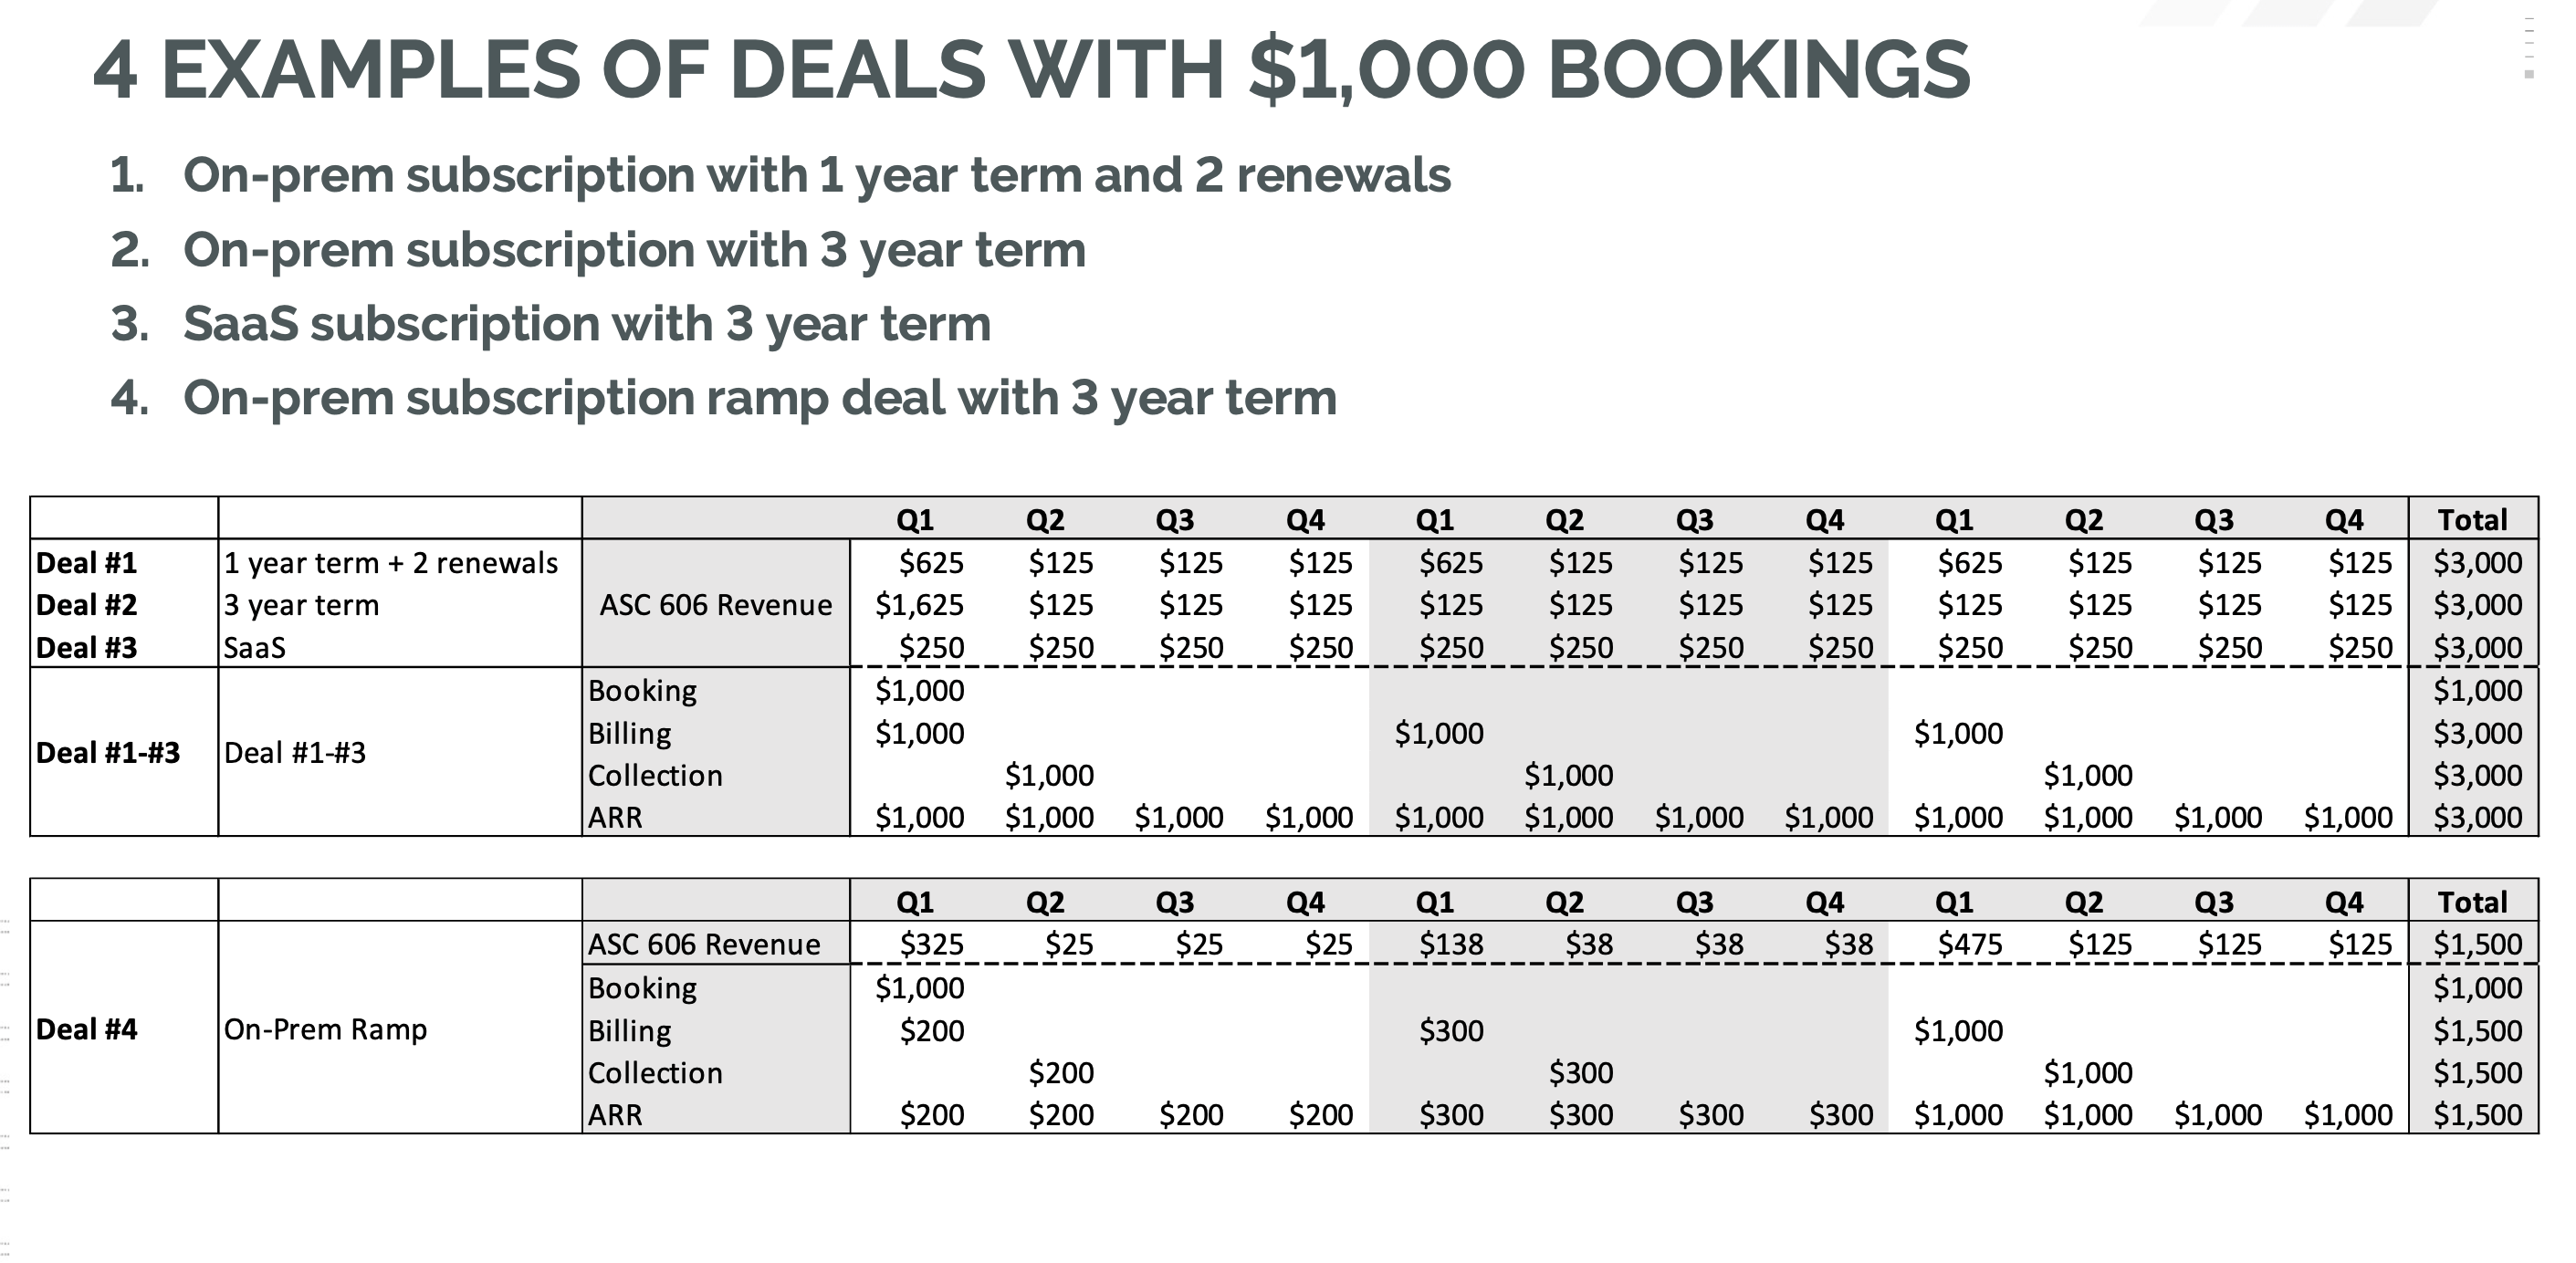
While revenue and ARR do marry up over time, ARR is the more appropriate representative of actual cash receipts from customers in any one financial year. Similarly, free cash flow represents the economic outcome of the business in a financial year much more closely than revenue-derived net income.
Growth Algorithm
Except for 2025, PTC has been growing ARR organically in the region of 11-15% and free cash flow well in excess of this:4
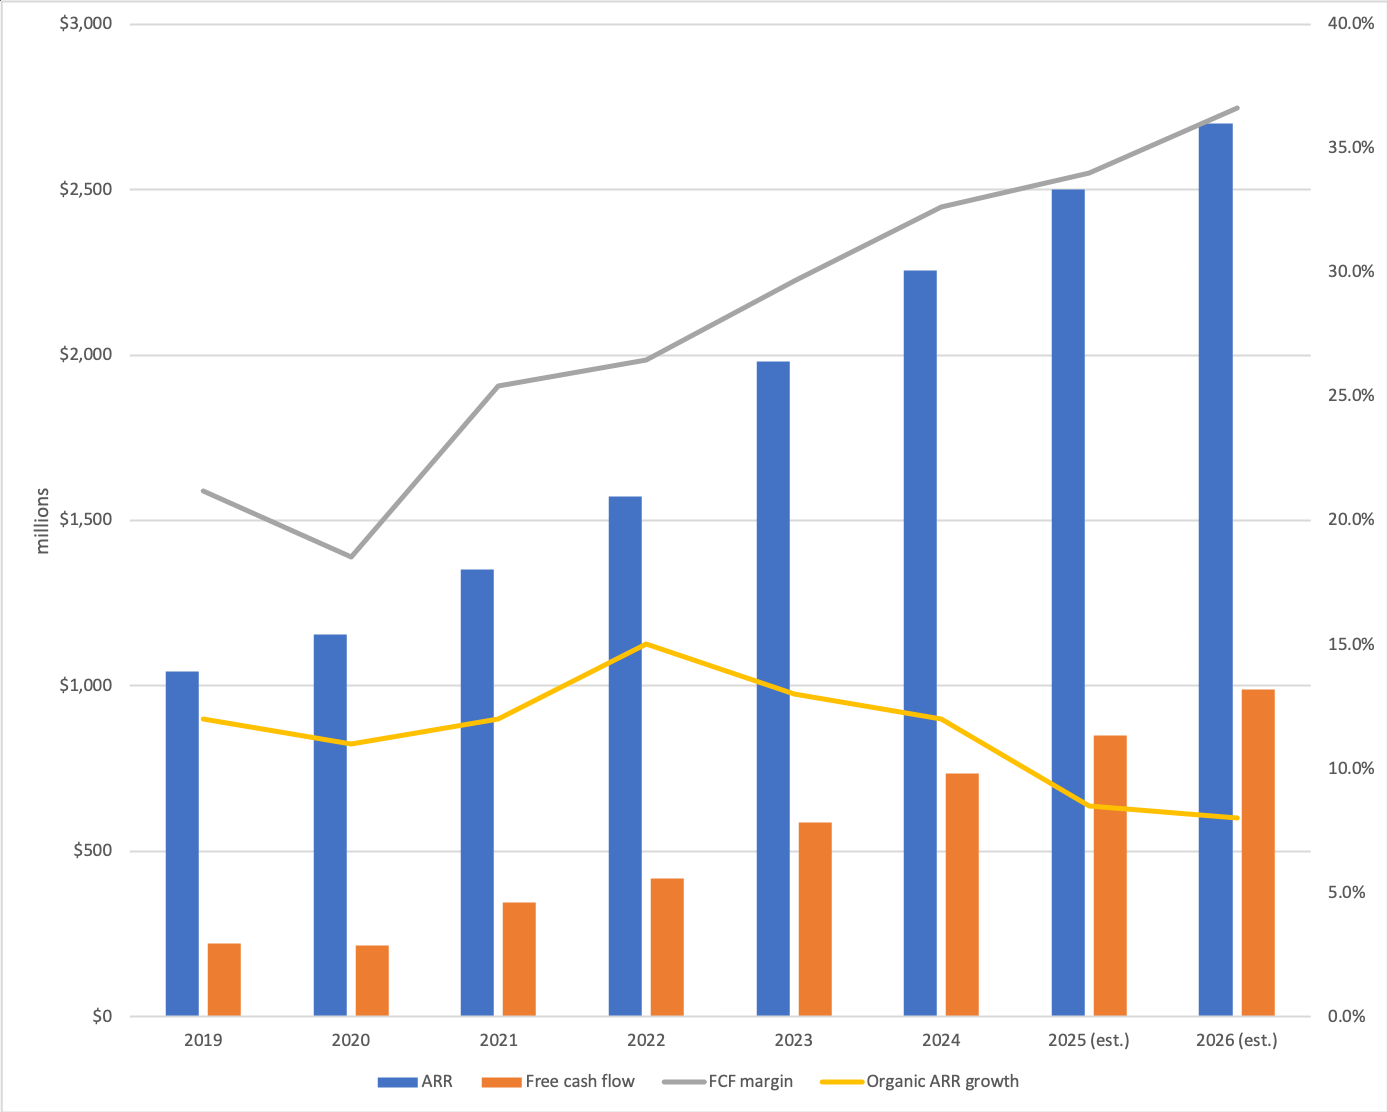
If we consider that the CAD market is growing mid-single digits and the PLM market is growing ~8%, with respective weightings of ~40% and ~60% PTC’s base ARR growth could be in the region of 7%. As noted in Part I up-sell, expansion and cross-sell are the principal drivers of PTC’s growth algorithm, implying that they could be behind the 5-6pp of additional growth that PTC is realising in a typical year. Our product review has hopefully helped to shed some light on how they achieve this - e.g. driving expansion of Windchill outside of engineering departments and into the enterprise, cross-sell into Codebeamer and ServiceMax and up-sell into Creo modules such as Simulation Live etc. As we covered in Part I, management’s stated intention is to sustain organic ARR growth in the low-double digits and the new go-to-market strategy is their plan for ensuring this. There are additional growth levers emerging as well:
Pricing: currently lower down in the growth algorithm relative to peers, it looks like PTC is shaping up to do more here in conjunction with the new go-to-market and AI feature roll-out. Impact: near- to medium-term
New logos: currently at the bottom of the growth algorithm due to the entrenchment of CAD/PLM competitors, we have discussed how Onshape could start to contribute meaningfully as it scales. Impact: medium- to long-term
SaaS conversion to Windchill+ / Creo+: PTC talk about a 2X (or more) uplift in ARR from on-premise to SaaS. Under Heppelmann, PTC used to talk about a 3pp average tailwind from SaaS over a 10 year adoption S-curve. While Barua has distanced himself the 10 year ambition, he’s still committed to making the transition happen and as of 2025 we’re in the foothills of the S-curve. Impact: medium- to long-term
With this context, the prospect for sustained double-digit ARR growth seems favourable to me. PTC’s other commitment in the medium-term is growing opex at roughly half the rate of ARR, which translates into ~1.5-2pp of margin expansion per year and free cash flow growth in the mid-teens assuming ~10% ARR growth. PTC is, of course, already a very profitable business - but I see no particular reason why it cannot become even more profitable given its competitive position. As discussed in Part I, a combination of an improved purchasing environment, traction in the go-to-market strategy and pricing action could result in a period of mid-teens ARR growth, translating into high-teens free cash flow growth.
Last, let’s talk about share count and what it could mean for per-share free cash flow growth. For the whole of FY24 and FY23 PTC decided to cease share repurchases to pay down debt following the ServiceMax acquisition - this led to a 1.2% and 0.9% increase in share count respectively due to share based compensation. PTC’s policy is to return excess cash through share repurchases, and given that debt has now been paid down, they are resuming repurchases. Additionally, management view the portfolio as largely complete at this time and the focus has shifted to organic growth - through this lens, most of PTC’s free cash flow would be ‘excess’. With ~$1bn of free cash flow targeted for FY26, PTC will be in a position to repurchase up to 4% of its shares per year at current prices - perhaps on a net basis they might be able to reduce share count by 1.5-2% per year, again bolstering the hypothesis for durable per-share free cash flow growth at least in the mid-teens.
Concluding Remarks
And so concludes the PTC deep dive! I think we’ll be hearing plenty more about the go-to-market strategy as well as the AI roadmap in the months ahead. We’ll have PTC’s fourth quarter earnings update in early November, and I wouldn’t be surprised if they announce an Investor Day - there hasn’t been one in a couple years and historically these have been in November or December. Stay tuned at NFTBC for more updates in due course.
Thanks for reading. As always, get in touch if you have comments or questions.
Further Reading
John Hirschtick is about the closest thing there is to CAD royalty and is always interesting to listen to. He still spends much of this time talking to customers in order to figure out how PTC can make Onshape better. I include here some interviews/podcasts that I enjoyed.
Note, Gemini’s score for PTC on MES integration is bit of a misnomer - Dassault and Siemens have their own MES product (PTC does not), and no doubt want customers to use it.
~50% of alternative options
Chart does not include professional services which constitutes ~5% of revenue or perpetual license which is negligible at this stage.
Another really interesting deep dive, in a sector I’ve not explored before. Lots to think about.